11.09.2026
C’s Get Degrees (of Pain)
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…


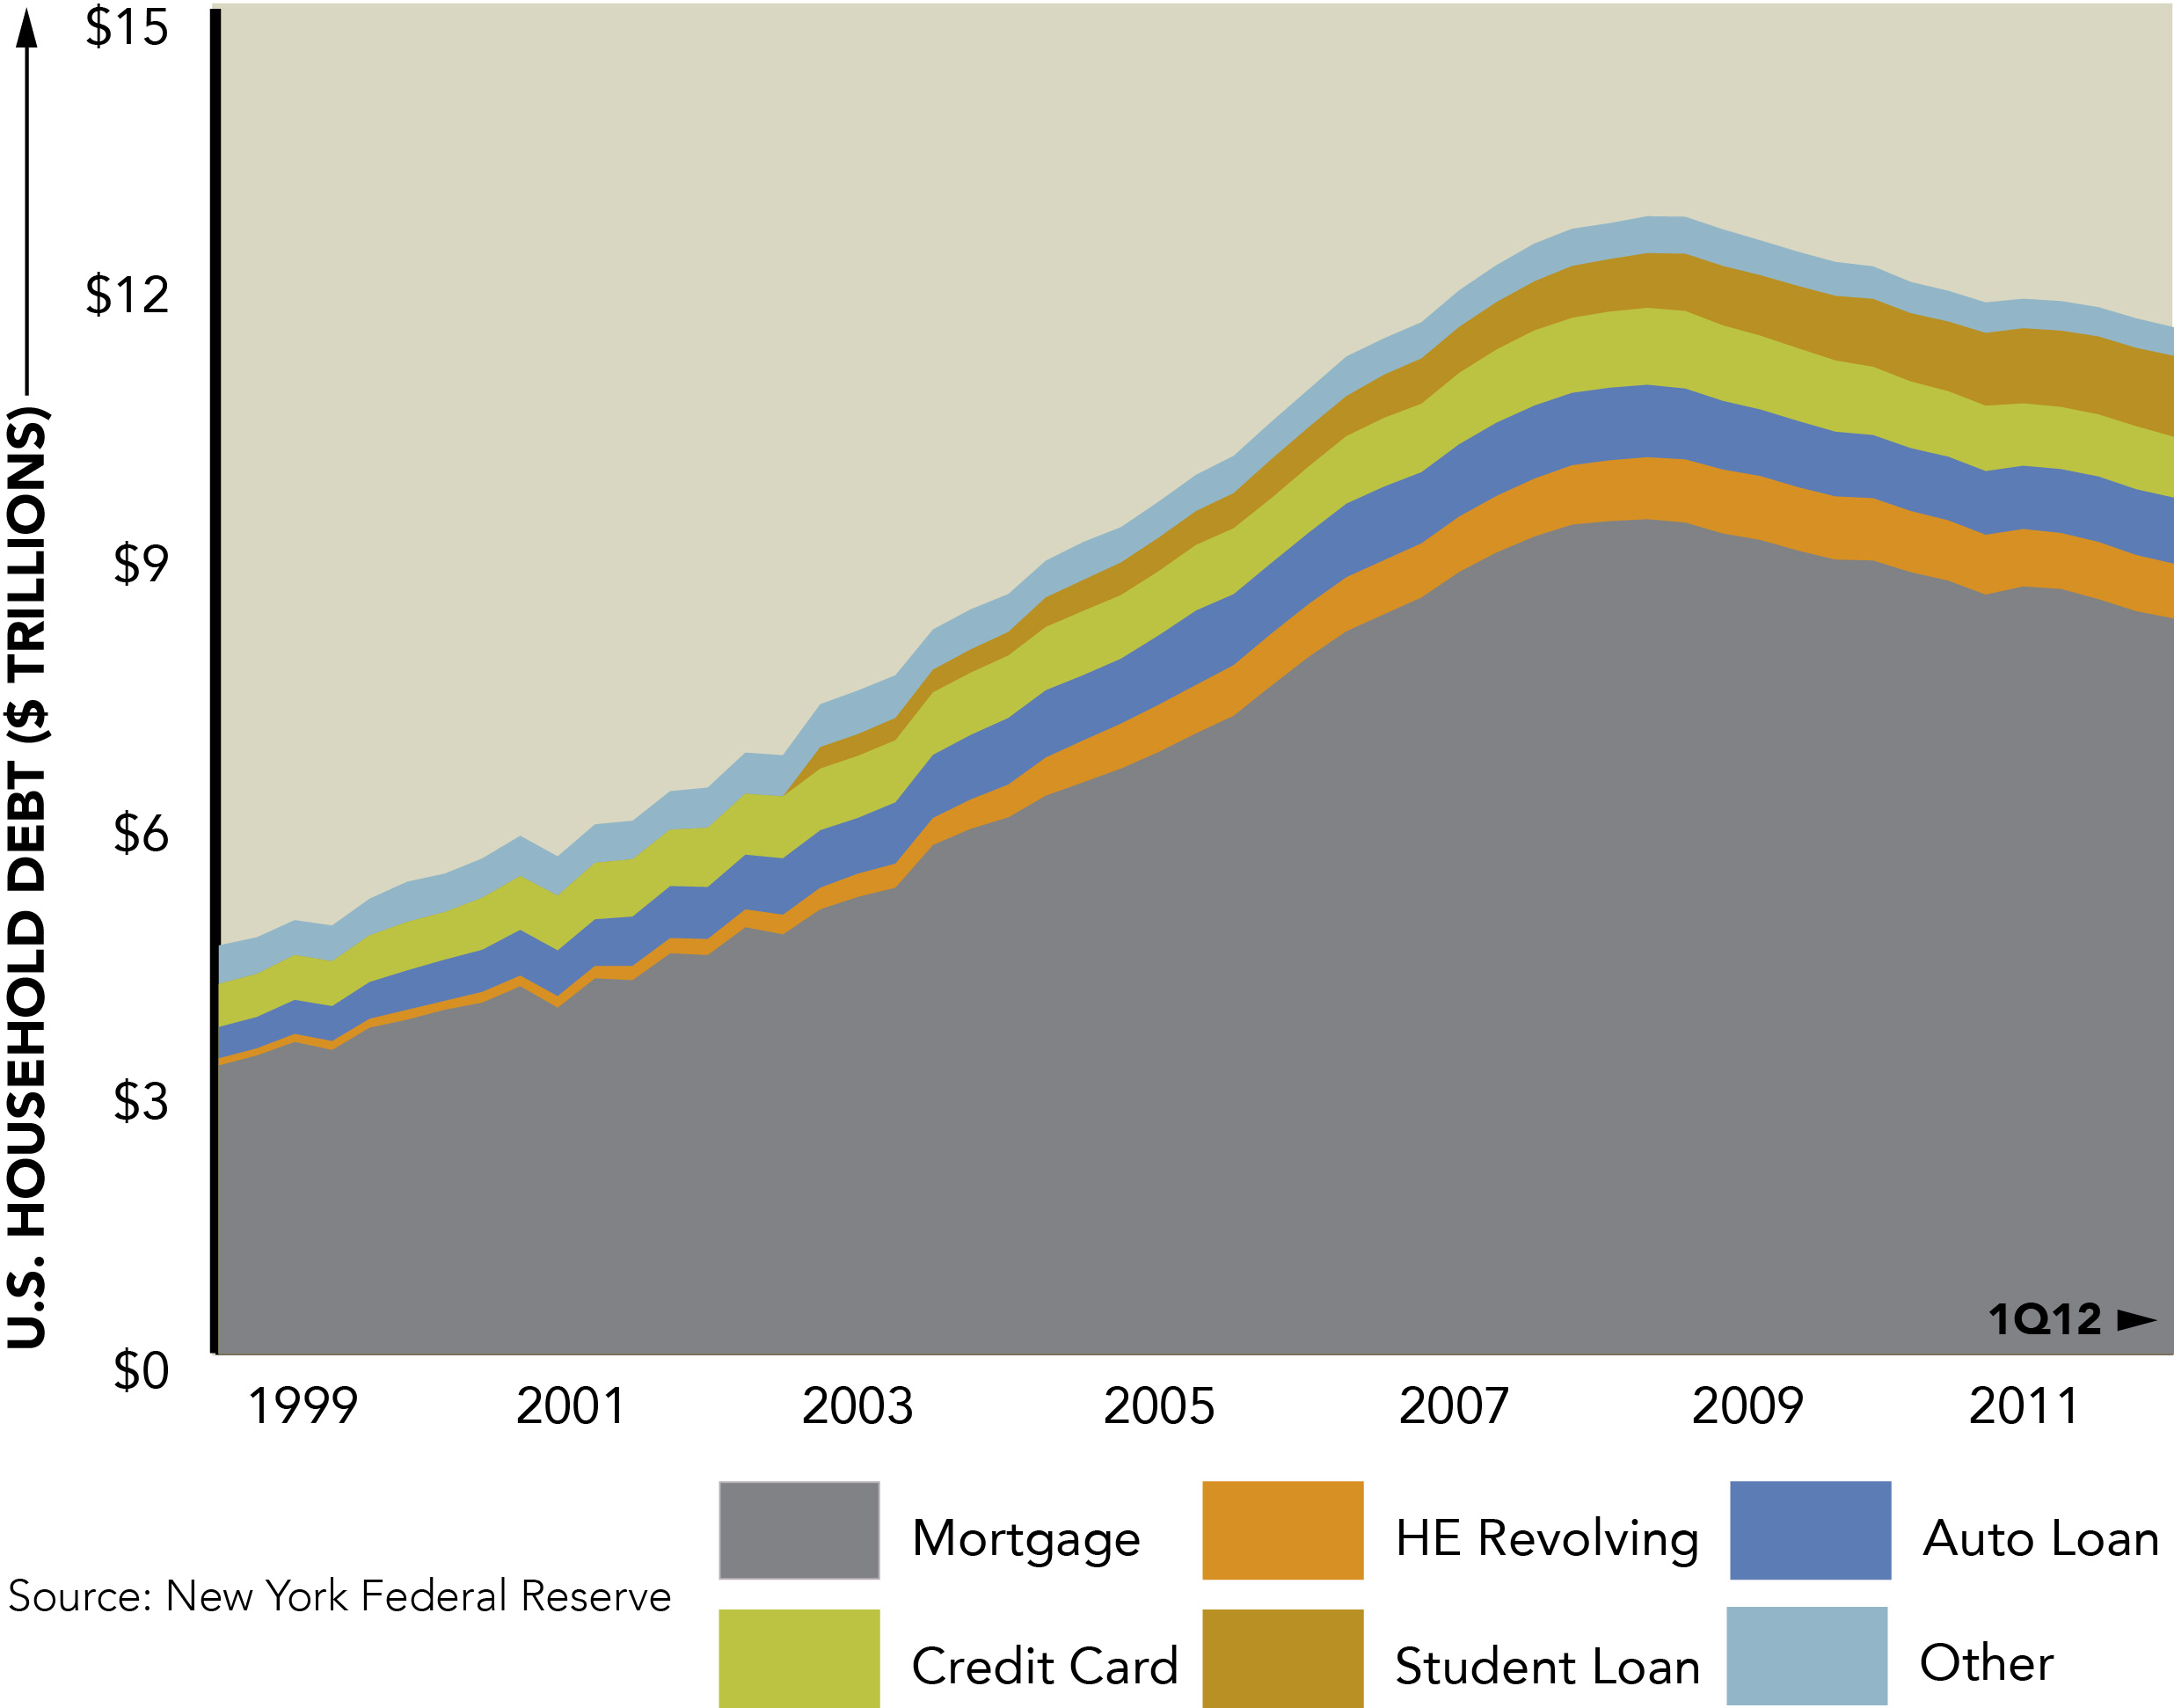
This week’s chart shows the components and level of U.S. household debt from March 1999 through March 2012. Categories of U.S. household debt include Mortgage, Home Equity Revolving, Auto Loan, Credit Card, Student Loan (which the Fed began tracking as an independent category in the first quarter of 2003), and Other which includes consumer finance and retail loans.
In its Quarterly Report on Household Debt and Credit, the Federal Reserve Bank of New York announced that total household indebtedness was $11.44 trillion as of the first quarter of 2012. The effects of U.S. household balance sheet repair since the 2008 recession can be seen in the above chart: after household debt peaked at $12.68 trillion in the third quarter of 2008, U.S. households have reduced total debt levels by $1.24 trillion (10.8%). In addition to a reduction in consumer spending, total debt levels were reduced due to banks exercising greater caution when issuing credit cards and mortgages. All categories of household debt decreased during this time with the exception of student loans which grew by 47.9%. During this time, college tuition costs continued to rise and households took on greater amounts of student loans in hopes of improved employment prospects. Student loans are now the second largest component of U.S. household debt behind mortgages.
As households continue to de-lever and focus on balance sheet repair, their consumption will not be as large of a driver to total GDP as it has been historically, therefore creating another headwind for robust economic growth.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >