10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


As the number of new coronavirus cases outside of China continues to rise and the oil price war between Saudi Arabia and Russia ensues, spreads of credit default swaps have widened hand-in-hand with the spreads of high yield bonds. Our chart this week will examine what this means for investors.
A credit default swap (CDS) is a derivative security that insures against default on a bond. In other words, the price of a CDS shows the market’s projection of the issuer’s likelihood of defaulting. Referred to as a spread, the price of a CDS is tracked in basis points, similar to the spread of a bond. Currently, the broad high yield CDS index, called the high yield CDX,¹ has a spread of 551bp as shown in the gray line. This means that a CDX investor must pay $5.51 per year to insure $100 worth of the high yield bond index from default. This is a near-term high, as the CDX’s spread was as low as 275bp in early January when it cost only $2.75 per year to insure $100 worth of the high yield bond index from default. But it is not as high as the point it reached in mid-February 2016, the peak of the U.S. shale crisis when it cost $5.89 per year to insure $100 worth of the high yield bond index from default.
A high spread for the CDX index means that the market is assigning a higher average likelihood of default to high yield bonds today as a result of the forward economic fallout from lower expected corporate earnings due to the coronavirus as well as the difficulties energy companies will have to endure due to the low price of oil. However, this high CDX spread also suggests attractive prices of the underlying bonds. Shown in the blue line, option-adjusted spreads for high yield bonds have widened to well above long term averages, signifying a compelling opportunity. With the U.S. consumer still on strong footing, high yield issuer fundamentals remaining moderate, and China in recovery mode as their coronavirus cases are declining and capacity utilization is rising, we would encourage investors to consider adding to their high yield allocations through dollar-cost averaging over the next few quarters, in accordance with the adage “buy fear, sell greed.”
Print PDF > A Spike in the Cost to Insure High Yield Bonds from Default
¹Inception of the high yield CDX was in 2012, while inception of the high yield bond index was in 1994
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
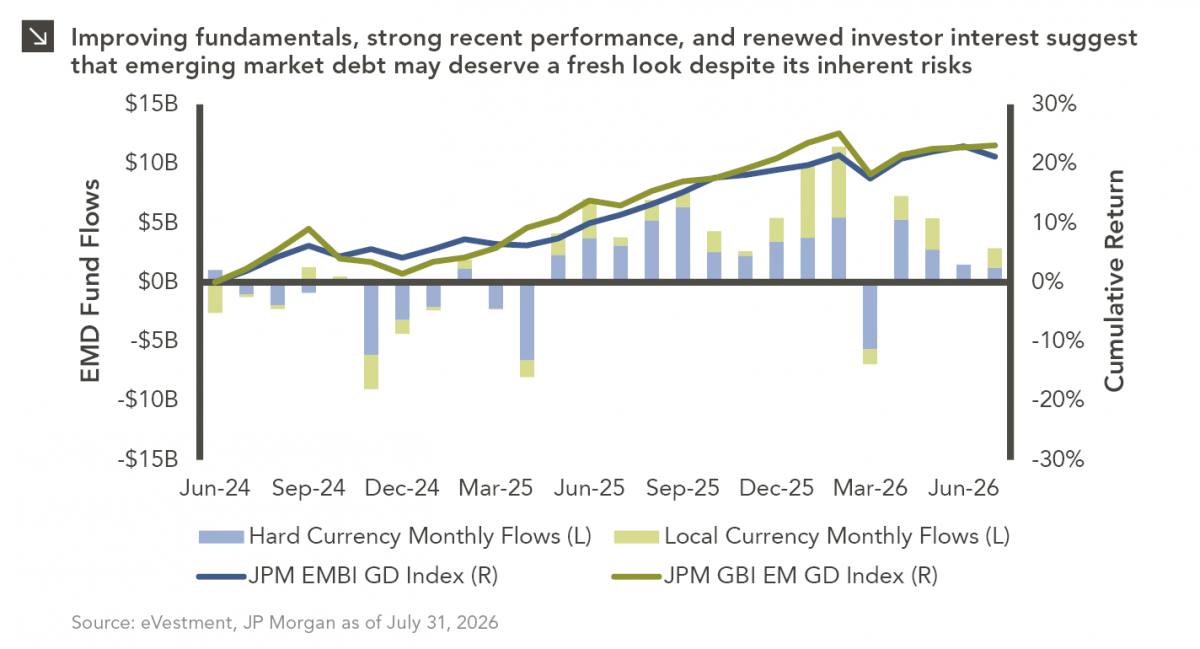
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >