Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index has notched an average return of approximately 6.5% in the fourth quarter of midterm election years, compared with roughly 3.0% in the fourth quarter of all other years.

Why do stocks tend to perform well following midterm elections?

  • Markets often experience uncertainty ahead of elections, with a recovery sometimes beginning in the days leading up to Election Day. Once the outcome of the election becomes clearer, the range of potential policy outcomes narrows, reducing uncertainty and potentially supporting equity valuations. Historically, this pattern has occurred regardless of which party gains or loses control of Congress.
  • The incumbent president’s party has lost seats in 36 of the last 39 midterm elections. A divided government can limit the likelihood of sweeping policy changes, providing investors with greater visibility into the regulatory and fiscal environment. Major changes to corporate taxes, capital gains treatment, healthcare, financial regulation, and energy policy often require congressional support. Although a divided government can constrain both pro-growth measures and policies that may weigh on corporate profitability, markets may benefit from greater predictability and a narrower range of potential outcomes.
  • Administrations may pursue more difficult or politically contentious measures earlier in a presidential term, while placing greater emphasis on pro-growth policies and economic stimulus as the next presidential election approaches. This dynamic can contribute to a more supportive policy environment for equities later in the presidential cycle.

Does this suggest stocks will rally following next month’s midterm elections?
Historical evidence points to a favorable seasonal tendency for U.S. equities following midterm elections, particularly over the subsequent two to three months. However, this pattern should be viewed as a supportive factor rather than a standalone investment signal. A more compelling outlook would combine favorable election-related seasonality with improving earnings expectations, reasonable valuations, and supportive monetary policy. Of these four factors, at least two currently appear to be in place, providing a potentially constructive backdrop for U.S. equities, although historical patterns do not guarantee positive returns.

The Power Demand Supercycle

This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the rapid expansion of data centers and increasing adoption of artificial intelligence. Specifically, U.S. power consumption is projected to rise from approximately 4.4 TWh in 2025 to 5.7 TWh by 2030, with data centers accounting for a significant portion of this increase. This trend is particularly evident in the PJM electricity market, where peak load is now forecast to reach 251 GW by 2046, significantly exceeding the 181 GW of current capacity. For context, the PJM Interconnection is the regional wholesale electricity market serving all or parts of 13 states and the District of Columbia, while peak load represents the highest level of electricity demand at a given time. The widening gap between projected peak demand and available capacity highlights the need for substantial investment in new generation, transmission, and storage infrastructure to maintain grid reliability and meet growing electricity needs.  Further, successive upward revisions to demand forecasts underscore the magnitude of anticipated electricity needs and the growing pressure on existing power infrastructure.

This widening gap between projected demand and available capacity is creating a substantial investment opportunity across the broader energy infrastructure ecosystem. Beyond data center development, significant capital will be required to expand power generation, modernize transmission and distribution networks, and deploy energy storage solutions to support grid reliability. For infrastructure investors, these trends present opportunities across both traditional and emerging sectors, including regulated utilities, contracted power generation, renewable energy, and battery storage. While the scale of investment needs is significant, execution risks related to permitting, grid interconnection, construction timelines, and regulatory frameworks remain important considerations. Core and core-plus infrastructure strategies may be particularly well positioned to benefit from this structural demand growth through long-duration assets supported by regulated or contracted cash flows.

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up at front doors demanding candy, but rather a potential uptick in market volatility, which has remained relatively muted over the last several months. Indeed, the CBOE Volatility Index (“VIX”), which measures expectations for U.S. stock market volatility over the next 30 days based on S&P 500 Index option prices, currently sits at roughly 15.8, placing it close to the lowest third of observations since 1990. Additionally, the VIX has not climbed above 25 since April, suggesting that investors are not currently spooked about the near-term outlook for U.S. equities. It is worth noting, however, that October has historically seen the highest average VIX levels of any month since 1990. These dynamics can be observed in the chart above.

Often referred to as the market’s “fear gauge,” the VIX tends to rise when investors expect greater market uncertainty and fall when expected volatility is lower. A few factors may help explain why the VIX has tended to be higher in October. For instance, U.S. midterm and presidential election cycles can contribute to greater uncertainty during the fall, as investors assess potential changes to fiscal, regulatory, and trade policy that could result from a change in political leadership. To that point, CBOE has observed higher implied volatility around Election Day, including in 2024 as the presidential election approached. It is important to point out that October’s historical volatility has also been heavily influenced by major market events, particularly the Global Financial Crisis. Specifically, the VIX reached an intra-month high of roughly 89.5 on October 24, 2008, as the crisis intensified, and spent most of that month above 60. Additionally, although not captured in the chart above, the infamous “Black Monday” crash of 1987 that saw the S&P 500 Index plummet by more than 20% occurred on October 19. These data points suggest that at least part of October’s spooky reputation is attributable to exogenous market shocks rather than a predictable seasonal effect specific to the month itself.

While October has historically been associated with elevated volatility, market gyrations in the weeks ahead are by no means inevitable. Corporate fundamentals remain relatively strong, providing an important foundation for equity markets even as investors navigate a range of uncertainties. At the same time, the upcoming midterm elections and elevated market valuations could create greater sensitivity to economic developments, potentially contributing to periods of increased volatility. Ultimately, while October may have a reputation for spooking investors, the prospect of heightened volatility should not distract investors from their long-term strategic allocations or lead them to make short-term investment decisions based on seasonal market fears.

Getting Real on Inflation

The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S. Treasury rates this year (e.g., the yield on the 10-year U.S. Treasury security has surged over 80 basis points since the start of 2026). Indeed, the U.S. has seen an uptick in inflation over the last few months, with the Consumer Price Index (CPI) reaching 3.4% on a year-over-year basis in August (up from 2.4% in February but down from an intra-year high of 4.2% in May). Higher energy prices due to the conflict in Iran are a major driver of the increase in CPI, and earlier this month the Federal Reserve hiked its benchmark interest rate for the first time in over three years in response to these price pressures. Given these dynamics, some might reasonably assume that expectations of higher inflation are putting upward pressure on interest rates, but a closer look at the data reveals there may be other factors at play.

This week’s chart shows the nominal 10-year U.S. Treasury rate, the real yield on the 10-year U.S. security, and the “5-Year Forward 5-Year Breakeven Inflation Rate,” which represents expected inflation over the five-year period beginning five years from today. As the chart indicates, the breakeven inflation rate has remained largely range-bound in 2026, meaning nominal interest rates and real interest rates have risen in tandem.

Why has the breakeven rate not increased this year? Traditionally, higher inflation occurs when there is too much money chasing too few goods (i.e., “demand-pull” inflation). Supply disruptions that temporarily increase prices, on the other hand, can lead to what is known as “cost-push” inflation. Notably, disruptions in supply chains during the COVID-19 pandemic caused transitory inflation to become embedded since the money supply also increased dramatically during that period. It is important to point out, however, that despite the closure of the Strait of Hormuz, Federal Reserve policy has remained largely restrictive in 2026 and broader monetary conditions have not loosened significantly. Indeed, commodity shocks often lead to temporary increases in price levels, and this dynamic helps explain why long-term inflation expectations have not increased meaningfully since the beginning of the year.

In effect, rising real yields, rather than higher expected inflation, are driving nominal yields higher. Real yields are driven by economic growth and policy dynamics, and recent movements in real yields are primarily a result of stronger growth forecasts combined with a higher term premium due to concerns around fiscal sustainability and government borrowing. While inflation remains an important consideration for investors, the data suggest that the recent rise in nominal yields is being driven more by changes in the economic and fiscal outlook than by expectations of persistently higher inflation.

Let’s Make a Deal

For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would keep buyers and sellers apart within private markets. While elevated base rates did indeed slow transaction activity as the market adjusted to a higher cost of capital, this dynamic did not lead to a structural freeze in dealmaking. To that point, average leveraged buyout, merger, acquisition, and recapitalization volume from the beginning of 2024 through the first half of this year was roughly $44.9 billion, only modestly below the $49.2 billion average exhibited from the third quarter of 2018 through the first quarter of 2022. These data points suggest that buyers and sellers are increasingly finding ways to bridge valuation gaps and transact within a higher cost of capital environment. It is important to note that dealmaking activity declined last quarter due to renewed uncertainty surrounding trade policy, geopolitical risks, and concerns regarding potential disruptions that artificial intelligence may cause within various industries. However, given that deal activity typically varies meaningfully from quarter to quarter, this decline could simply be a function of normal cyclicality rather than evidence of a coming slowdown.

For investors, the current environment presents both opportunities and risks. For instance, elevated base rates continue to support attractive gross yields for direct lenders, while higher debt-service burdens place greater pressure on borrowers and limit the ability of fund managers to financially engineer returns. As a result, underwriting discipline, downside protection, and operational value creation are likely to become increasingly important drivers of investment performance, particularly relative to the low-rate environment during which inexpensive leverage and multiple expansion played a more significant role in generating returns. Going forward, disciplined fund selection will be critical for investors, with manager performance dispersion potentially widening across both the private equity and private credit spaces.

No More Free Lunch?

There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of the list for many employees. Each week, the company generously provides catered cuisine from one of Chicago’s many fine dining establishments, and team members gather in the cafeteria to enjoy great conversation, build connections across the firm, and eat a tasty meal free of charge! Of course, since Marquette is ultimately footing the bill, these lunches are technically not “free.” In fact, Nobel Prize-winning economist Harry Markowitz famously stated that “diversification is the only free lunch in investing,” meaning that risk-adjusted returns can be improved simply by combining different assets within a portfolio. For more than four decades, this maxim held true, as an investor could add equity exposure to a fixed income portfolio and increase overall returns while also reducing risk. Specifically, from 1976 through the end of 2019, the Bloomberg U.S. Aggregate Bond Index notched annualized return and standard deviation figures of 7.3% and 5.3%, respectively. Given the lack of correlation between stocks and bonds during that period, however, an investor could have created a portfolio with a 90% allocation to the Bloomberg U.S. Aggregate Bond Index and a 10% allocation to the S&P 500 Index to increase overall returns while decreasing risk. This diversification benefit (i.e., free lunch) can be observed on the left-hand side of the chart above.

Another Nobel laureate, Milton Friedman, famously argued that “there is no such thing as a free lunch,” emphasizing that every benefit comes with an associated opportunity cost. The last several years have certainly supported this notion, as the slope of the efficient frontier of stock-bond portfolio combinations has increased significantly since the start of 2020, and investors across the spectrum of combinations have been required to accept greater risk to achieve higher returns. Remarkably, the 100% S&P 500 Index portfolio exhibited the highest Sharpe ratio (0.69) of any of the combinations on the 2020–2026 efficient frontier, meaning that any amount of fixed income exposure led to lower risk-adjusted returns for investors over this period. This is in stark contrast to the 1976–2019 period, during which the 100% S&P 500 Index had the lowest Sharpe ratio of any possible combination on the efficient frontier (0.51), with the highest being a combination closer to 50% S&P 500 Index and 50% Bloomberg U.S. Aggregate Bond Index (0.65).

The primary driver of the dynamics detailed above has been the breakdown in the traditional relationship between stocks and bonds. Historically, bonds exhibited low or even negative correlation with equities, providing meaningful diversification benefits within multi-asset portfolios. For instance, during periods of economic expansion in previous decades, stronger growth and rising interest rates often weighed on bond prices while supporting corporate earnings and stock valuations. Conversely, during periods of economic stress, declining interest rates generally boosted bond prices while causing equities to come under pressure. Indeed, from 1976 through 2019, the Bloomberg U.S. Aggregate Bond Index exhibited a correlation of 0.20 with the S&P 500 Index. This relationship, however, has changed materially since the start of 2020. That year, the Federal Reserve responded to the economic shock caused by the COVID-19 pandemic with aggressive monetary easing, driving interest rates sharply lower and supporting strong returns across both fixed income and equity markets. The Bloomberg U.S. Aggregate Bond and S&P 500 indices returned 7.5% and 18.4%, respectively, in 2020. In 2022, circumstances shifted sharply, as high inflation, tighter financial conditions, and concerns around corporate profitability proved challenging for most asset classes, and the Bloomberg U.S. Aggregate Bond and S&P 500 indices returned -13.0% and -18.1%, respectively. One notable factor contributing to the higher correlation between stocks and bonds in recent periods has been the increasing concentration of growth-oriented companies within equity indices. Because these businesses derive a significant portion of their value from cash flows expected far in the future, their valuations are particularly sensitive to interest rate fluctuations. As a result, rates have played a more prominent role in determining both fixed income and equity returns over the last few years, increasing the likelihood that the two asset classes move in the same direction. To that point, the correlation between the Bloomberg U.S. Aggregate Bond Index and the S&P 500 Index has been 0.51 since the start of 2020.

While the benefits of a traditional stock-bond portfolio may now be less pronounced than they have been historically, diversification remains a valuable portfolio construction tool because equities and fixed income are still not perfectly correlated. Even if the two asset classes move in the same direction over the coming quarters, the higher bond yields offered today provide a meaningful source of income and return that was largely absent during the low-rate environment of the early 2020s. Additionally, as inflation continues to moderate and monetary policy normalizes, the historical relationship between stocks and bonds is likely to reassert itself, which may restore some of the diversification benefits investors have come to expect from multi-asset portfolios. Although the diversification benefits of a traditional stock-bond portfolio have diminished in recent years, maintaining exposure to multiple sources of return remains a cornerstone of prudent long-term investing. And for all of us at Marquette Associates, let’s hope the phrase “no more free lunch” never extends beyond portfolio theory and into the lunchroom!


EMD’s Second Chance?

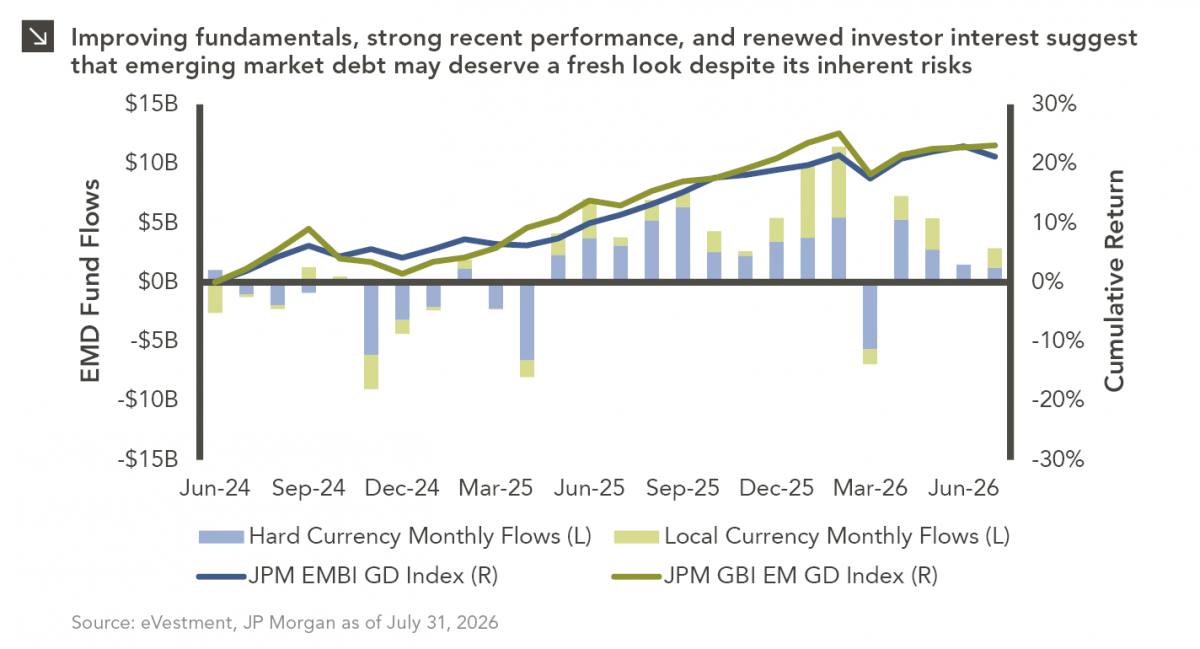
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income sectors narrowing the traditional yield advantage of the space. While many investors have overlooked or even exited EMD funds as a result of these challenges, recent developments have driven some investors back to the asset class. For instance, many emerging market countries have implemented meaningful structural reforms, particularly following the economic challenges associated with the COVID-19 pandemic. These countries have made progress in reducing inflation, managing government spending, and strengthening monetary and fiscal policy frameworks. Additionally, the continued development of domestic investor bases for local-currency debt has improved countries’ ability to withstand external shocks and reduced their reliance on foreign capital flows. Sovereign credit fundamentals have also improved, with credit upgrades gradually outpacing downgrades across the emerging market universe.

As some of the traditional risks associated with emerging market bond investing have moderated, performance has improved. To that point, EMD was the top-performing major fixed income asset class in 2025, and this momentum has continued so far this year. As of July 31, hard- and local-currency EMD indices have both returned roughly 1.8% on a year-to-date basis, respectively, outpacing high yield and core bonds over the same timeframe. Additionally, since the end of 2024, these indices have returned 10.1% and 13.1%, respectively. For context, the key difference between these indices is that local-currency debt exposes investors to both interest rate and currency movements, whereas hard-currency debt largely eliminates direct exposure to the issuing country’s currency.

Improving fundamentals have also supported renewed capital flows into the asset class. According to EPFR, cumulative EMD fund inflows for 2026 surpassed $31 billion as of the end of July. It is important to note that the composition of those flows is evolving. Historically, hard-currency debt has dominated investor allocations, but more than 50% of EMD fund flows have been directed toward local-currency strategies in 2026. Several factors could be contributing to this dynamic, including a weaker U.S. dollar, attractive local interest rates, improving macroeconomic fundamentals, and growing confidence in the stability of emerging market currencies.

All of this being said, EMD remains a complex asset class that poses risks related to interest rates, currencies, sovereign credit quality, and capital flows. Foreign investment flows can also introduce volatility during periods of market stress and risk-off environments. Nevertheless, the recent outperformance of EMD indices has clearly not gone unnoticed by investors, and the improving fundamentals and diversification benefits offered by the asset class suggest that it may deserve a second chance.

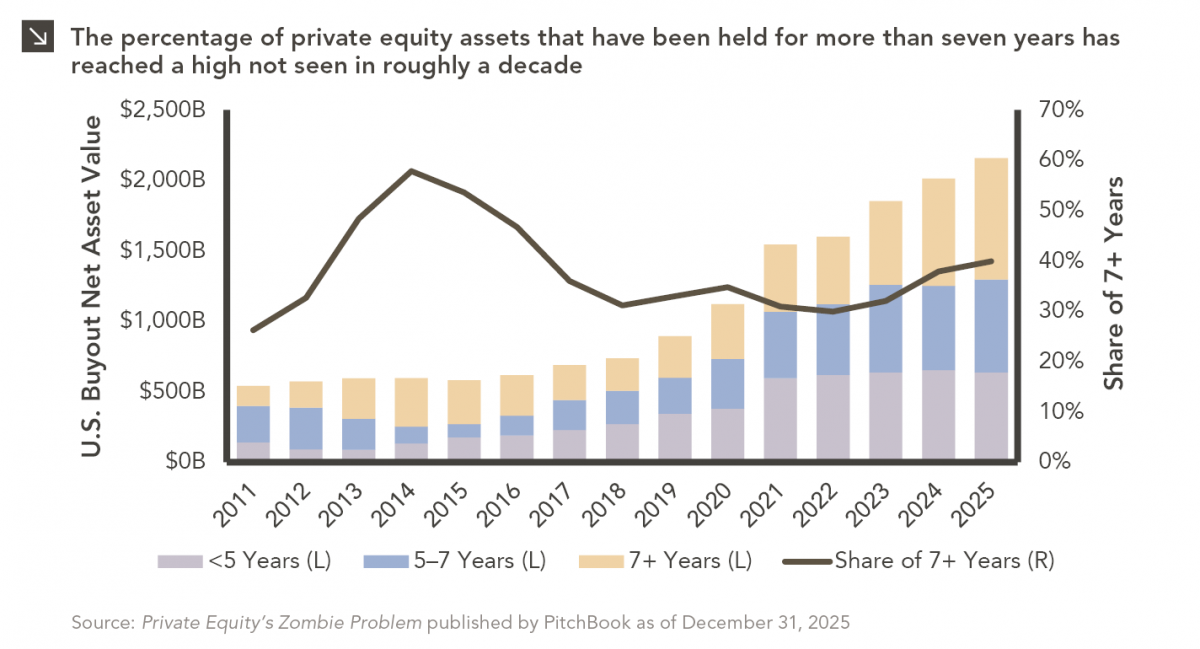
Zombie, Inc.

Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears to be hosting an entire zombie convention. The occasional underperformer has given way to a growing pool of aging assets that remain operational and solvent but increasingly difficult to exit. According to PitchBook, more than one-third of U.S. private equity-backed companies have been held for over five years, with hold periods for thousands now exceeding the traditional exit window. The causes of this trend are not mysterious. In hindsight, the industry may have committed the cardinal sin of every market cycle: mistaking favorable conditions for permanent conditions. Between 2020 and 2021, sponsors acquired businesses amid an environment of near-zero interest rates, abundant leverage, and valuation multiples that appeared destined to move only upward. That said, when rates rose and multiples compressed in 2022, two of private equity’s favorite value drivers, cheap debt and multiple expansion, suddenly disappeared. The result was a cohort of companies purchased at EBITDA multiples of 12x or greater that now struggle to justify valuations of 10x or less.

These “zombie companies” tend to share a similar profile. Specifically, they tend to be older assets with extended hold periods, elevated leverage, slowing earnings growth, and limited buyer interest. Further, many have not completed a refinancing, recapitalization, add-on acquisition, or meaningful transaction in years. It is important to note that zombie companies tend not to be bankrupt. In fact, that is part of the problem. Thanks to covenant-lite loans, amend-and-extend transactions, and payment-in-kind interest, companies can survive almost indefinitely without truly improving. In short, these businesses are less “walking dead” and more “comfortably numb.”

For limited partners, the implications of this dynamic are becoming increasingly difficult to ignore. From a liquidity standpoint, DPI (a key performance metric in private equity that measures the cash returned to investors relative to the capital they invested) has lagged historical norms in recent time (particularly for 2018–2022 vintages), while TVPI (a metric that measures a private equity fund’s total return compared to the actual money investors have paid in) has remained stubbornly stable. In plain English, paper value is not turning into cash for private equity investors. Indeed, limited partners expected distributions but have instead received an education on quarterly valuations and continuation vehicles. More subtly, zombies threaten one of private equity’s defining advantages: efficient capital recycling. As managers spend more time extending maturities and defending marks (rather than sourcing exits), capital cannot be redeployed into new opportunities. Continuation vehicles, while often legitimate solutions to liquidity challenges, increasingly risk looking less like a value-creation tool and more like the industry’s version of moving leftovers into a different container.

The good news for limited partners is that the rise of zombie companies appears to be a growth inhibitor for the asset class rather than a systemic crisis, and it is important to remember that most private equity funds are designed to absorb precisely this kind of stress. The bad news is that patience, once considered a virtue, may now be considered a holding strategy. As the living learn, the dead rarely disappear on their own.

Long Weakened

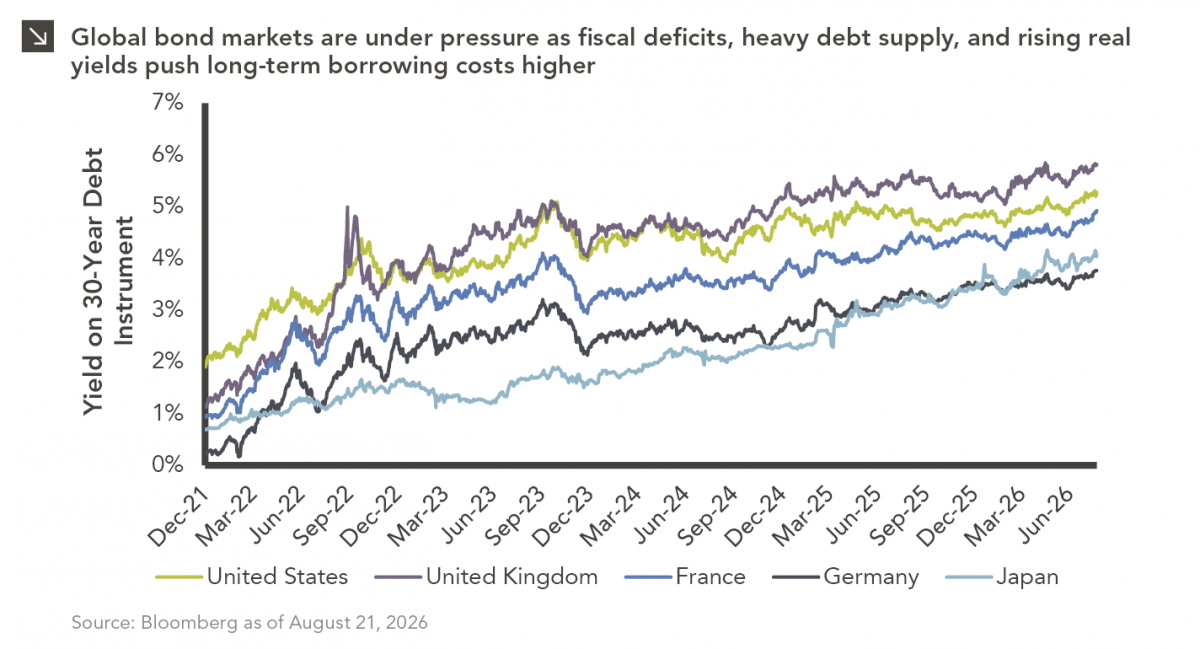
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing costs in several developed economies to extreme levels relative to recent history. For instance, the 30-year U.S. Treasury yield sits at nearly 5.3% as of this writing, near its highest level since 2007, after rising more than 40 basis points in the last two months. Additionally, 30-year borrowing costs in France recently reached their highest level since 2008, long-term yields in Germany have moved to levels not seen in more than 15 years, 30-year gilt yields have approached 6%, and comparable Japanese yields are near record highs.

While some country-specific factors are contributing to this sell-off, many of the drivers are global in nature. For instance, governments are running significant deficits at a time when interest rates remain well above the exceptionally low levels that prevailed for much of the past decade. In the U.S., interest expenses on the national debt have become an increasingly important contributor to the budget deficit, with fiscal-year-to-date interest costs now above $1.1 trillion as higher Treasury yields raise the government’s financing bill. It is important to note that the current environment also differs from previous periods of rising deficits. Historically, fiscal deterioration has often occurred alongside economic weakness, prompting central banks to cut interest rates and provide support to government bonds. Today, however, governments are adding to borrowing needs while monetary policy remains relatively restrictive. This dynamic could keep upward pressure on long-term yields even if central banks eventually begin lowering short-term rates.

Another important development is the changing composition of sovereign bond market investors. While government bonds have traditionally benefited from steady demand from institutions (e.g., pension funds and other liability-driven entities), demographic changes, pension reforms, and regulatory developments are impacting that demand. Consequently, governments are increasingly dependent on private investors, who are generally more sensitive to valuation and expected returns. This dynamic is particularly important at the long end of the curve, where the additional yield investors require to own longer-dated securities (i.e., the term premium) can have an outsized impact on borrowing costs. Government debt is also competing with a rapidly expanding supply of corporate bonds, as the capital requirements associated with artificial intelligence infrastructure have prompted technology-oriented companies to raise unprecedented amounts of debt (much of which is concentrated in longer maturities). As a result, bond investors now have more opportunities to deploy capital, and issuers must compete for that demand by offering attractive yields. Inflation is another reason investors have become less comfortable locking in yields for decades. The conflict in the Middle East has pushed energy prices higher, raising concerns about renewed inflationary pressures and the possibility that central banks could be forced to maintain restrictive monetary policy for longer than previously anticipated. That risk is particularly problematic for long-duration bonds, which have prices that are highly sensitive to changes in interest rates and inflation expectations. It should be noted, however, that the recent increase in long-term yields has not been driven entirely by rising inflation expectations, as long-dated inflation breakevens have remained largely contained across major markets. Instead, a significant portion of the increase has come from higher real yields (i.e., the inflation-adjusted compensation investors receive for owning bonds). That distinction is important because if real yields continue to rise because investors are demanding greater compensation for fiscal and economic uncertainty, long-term bonds could remain under pressure even without a major acceleration in expected inflation. The deterioration in long-term borrowing conditions is already influencing how governments approach debt issuance. For instance, the United Kingdom has reduced its planned issuance of longer-dated bonds and increased its reliance on shorter maturities. The problem with this approach is that shortening maturities does not eliminate underlying fiscal burdens but rather shifts more debt into the near-term refinancing pipeline. This leaves governments more exposed to future interest-rate movements. The U.S. Treasury is also taking steps to support liquidity in the long-end of the market, recently doubling the size of planned buybacks of longer-dated Treasuries to at least $4 billion per operation. While this initiative may provide some near-term support, its initial impact was short-lived, underscoring the challenge policymakers face in addressing the broader fiscal and supply-demand forces driving long-term yields higher.

One of the key takeaways here is that the long ends of yield curves across major economies are increasingly being shaped by forces that extend beyond traditional monetary policy expectations, with even the U.S. Treasury taking steps to support demand and liquidity in longer-dated bonds. Additionally, investors should note that rising long-term yields raise the discount rates applied to future corporate earnings, potentially creating a difficult backdrop for growth-oriented companies whose valuations depend heavily on cash flows expected many years in the future. On the positive side, the repricing in long-duration bonds could eventually create opportunities for investors with fresh capital, as higher real yields provide a more attractive starting point for long-term fixed income returns. The key question is whether yields are now high enough to compensate investors for the fiscal, inflationary, and supply-related risks currently embedded in the market.

Supersize Me!

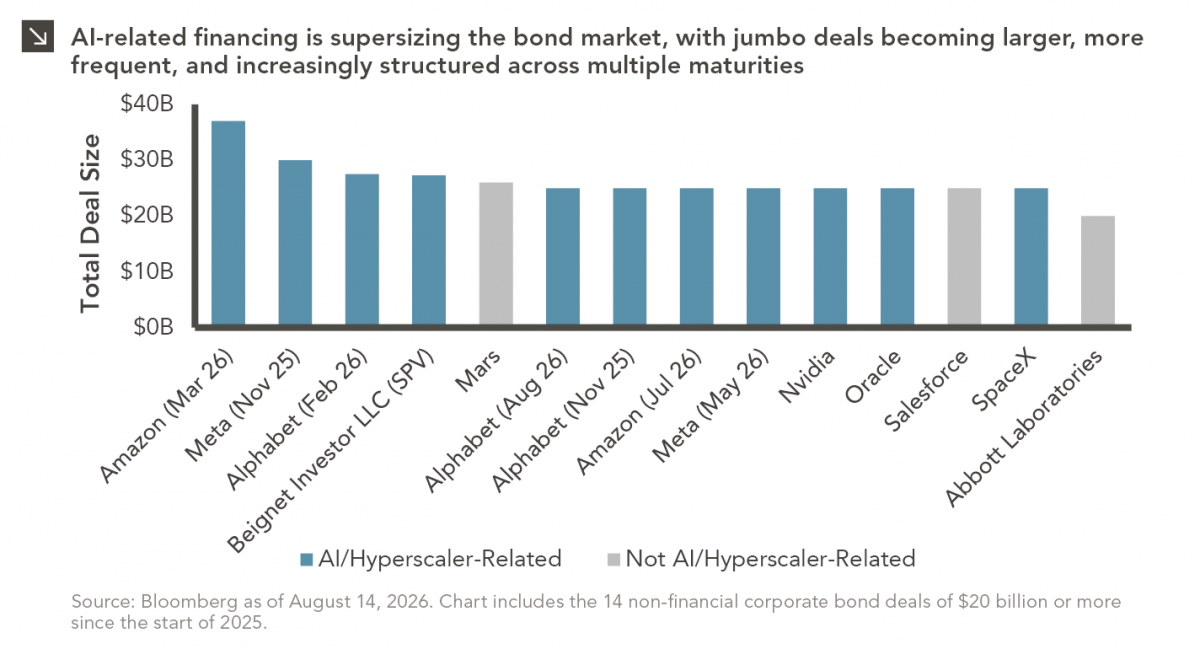
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For just $0.39 extra, I could upgrade to a 7-ounce serving of French fries and a 42-ounce cup of ice-cold Coca-Cola, which would serve as perfect complements to my nightly meal of two Big Macs, a 20-piece Chicken McNuggets, and a large Oreo McFlurry (assuming the ice cream machine was working). While McDonald’s discontinued supersizing its value meals in 2004 (to my eternal dismay), the bond market is experiencing its own supersizing moment today. Jumbo bond transactions, once a rarity, are now becoming increasingly common, and the definition of a “jumbo” deal has changed in recent years. Whereas any transaction above $5 billion was once considered jumbo, a wave of AI and hyperscaler-related deals has moved the goalposts closer to the $20 billion mark.

Since the start of 2025, there have been 14 non-financial corporate bond deals of $20 billion or more. Interestingly, only three of these deals were unrelated to AI or hyperscalers:

  • Mars issued $26 billion to help finance its acquisition of Kellanova
  • Salesforce issued $25 billion to fund share repurchases
  • Abbott Laboratories issued $20 billion to finance its acquisition of Exact Sciences

Of the remaining 11 deals, Amazon and Meta each issued two jumbo deals, while Alphabet, the parent company of Google, issued three. The pace of jumbo deals has also accelerated, with half of these 14 transactions occurring in 2026 (including five since June alone).

As jumbo deal size and frequency have increased, so too has the number of tranches within each transaction. Historically, investment-grade issuers typically split bonds into just a few tranches, but Amazon’s $37 billion issuance this year included 11 tranches, with maturities ranging from two to 50 years. Other recent jumbo transactions have included as many as eight tranches. Structuring a large transaction across multiple maturities allows companies to better manage borrowing costs while reducing refinancing and maturity concentration risks.

Going forward, the bond market does not appear ready for its own “Morgan Spurlock moment” that would lead to a reduction in these “supersized” deals. Indeed, heavy issuance from large, technology-oriented companies is likely to continue through the remainder of the year, with less than 40% of expected 2026 issuance having occurred through June 30. Investors continue to largely absorb these large transactions, and until that appetite meaningfully changes, companies appear happy to supersize their new issuances.