China: Regulators, Mount Up!

November 09, 2021 | David Hernandez, CFA, Director of Traditional Manager Search

Combination chart showing number of regulatory actions by the Chinese government (columns) and MSCI China Index cumulative returns (line) by month. Chart subtitle: In recent months, Chinese equities have been hampered by new regulations from Beijing authorities aimed at a variety of industries . Chart description: Left Y-axis shows Cumulative Return in percent of the MSCI China Index, from -20% to +15%. X-axis shows months from November 2020 to September 2021. Right Y-axis shows Number of Beijing Regulatory Actions from 0 to 35. The x-axis line is at the 0% mark for the Cumulative Return axis. Prior to this summer, the number of regulatory actions was very low, typically less than 5 per month in the data shown. In May 2021, there were 9 actions; June saw 3, then July had 14, August had 31, and September had 24. The MSCI China Index has struggled with this increase and has been negative each month since June. Chart Sources: Bloomberg, Cornerstone, and MFS; data as of September 30, 2021.

Over the last year, the Chinese government has enacted a series of new regulations targeting several domestic industries including finance, health care, and real estate. In general, the policies that have garnered the most attention are those directed at Chinese technology companies and range from restrictions on the use of advertising algorithms targeting consumers to limitations on the amount of time children are permitted to spend gaming online. As displayed in this week’s chart, these new regulations, the majority of which have been codified in the last few months, have shaken equity investors and led to a significant drop in the MSCI China Index. Specifically, the benchmark lost roughly 18.2% in the third quarter of this year alone as investors scrambled to react to the new regulatory environment in China and its ramifications.

Recent efforts of Chinese government authorities mark a sea change in the country’s social and economic goals and the ways in which those goals are pursued. For decades, China was largely comfortable with encouraging economic development at all costs, however, it seems officials in Beijing have now shifted their focus to pragmatic, quality growth with an emphasis on both prosperity and sustainability ahead of National Party Congress elections in 2022. It is worth mentioning that the developments of the last several months do not constitute a new experience for Chinese companies or investors. China’s government has a history of stepping in after periods of unchecked economic growth, with the targeting of the gaming industry in 2018 serving as a recent example. That said, the significant volume of policy changes that have been enacted in the last year has caught many investors by surprise, which has led to the drawdown in Chinese equity indices described earlier.

While this type of volatility can be difficult to stomach for most market participants, it can also allow investors the chance to purchase securities at more attractive valuations. To that point, many portfolio managers with a focus on Asian markets have expressed an interest in increasing their exposure to Chinese equities over the coming months given the dislocations that have potentially arisen as a result of the recent pullback, though most still expect market fluctuations to continue in the near term. Investors with exposure to Chinese markets should remain disciplined in their approach and cognizant of both the risks and potential opportunities stemming from the current situation.

Print PDF > China: Regulators, Mount Up!


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

David Hernandez, CFA
Director of Traditional Manager Search

Get to Know David

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

Line chart showing average option-adjusted spreads (OAS), in basis points, on Bloomberg CCC U.S. High Yield and Bloomberg U.S. Corporate High Yield bonds from December 2025 through October 2026. CCC-rated high yield spreads increased from approximately 600 bps to 1,100 bps, reaching their highest levels in nearly four years, while broader U.S. corporate high yield spreads remained relatively stable, increasing from approximately 260 bps to 330 bps. Source: Bloomberg as of November 6, 2026. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.09.2026

C’s Get Degrees (of Pain)

The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

Bar chart comparing October and year-to-date 2026 returns for Korea, Taiwan, Brazil, India, China, and the MSCI Emerging Markets Index. October returns are below zero for most markets, while year-to-date returns range from negative to positive. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.02.2026

The Haunting of Emerging Markets

Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

Stacked bar chart showing U.S. private equity deal value by deal size from Q1 2022 through Q2 2026. The y-axis shows percentage of total deal value from 0% to 100%, and the x-axis shows quarters by year. Stacked bar chart showing the percentage of U.S. private equity deal count by deal size from Q1 2022 through Q2 2026. The y-axis ranges from 0% to 100%, and the x-axis shows quarters by year. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.26.2026

Smaller Deals, Larger Appeal

Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

Line chart comparing S&P 500 Index cumulative returns for midterm and non-midterm election years since 1980. The x-axis shows October through December, and the y-axis shows S&P 500 Index cumulative return, ranging from -1% to 8%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.19.2026

Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
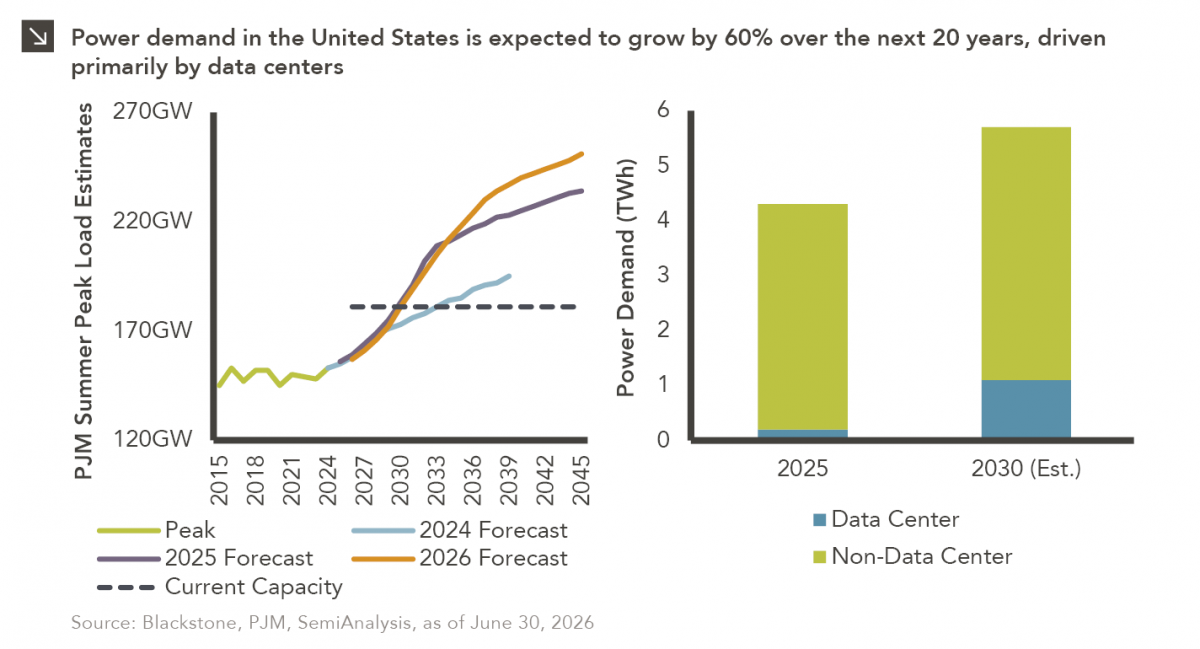
Chart #1 - Line chart showing PJM summer peak load estimates in gigawatts (GW) from 2015 to 2045. The chart compares historical peak load, current capacity, and forecasts from 2024, 2025, and 2026, showing projected demand rising above current capacity over time. Chart #2 - Stacked bar chart showing U.S. power demand in terawatt-hours (TWh) for 2025 and estimated demand in 2030. The chart compares data center and non-data center demand, showing total power demand increasing over the period.

10.12.2026

The Power Demand Supercycle

This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
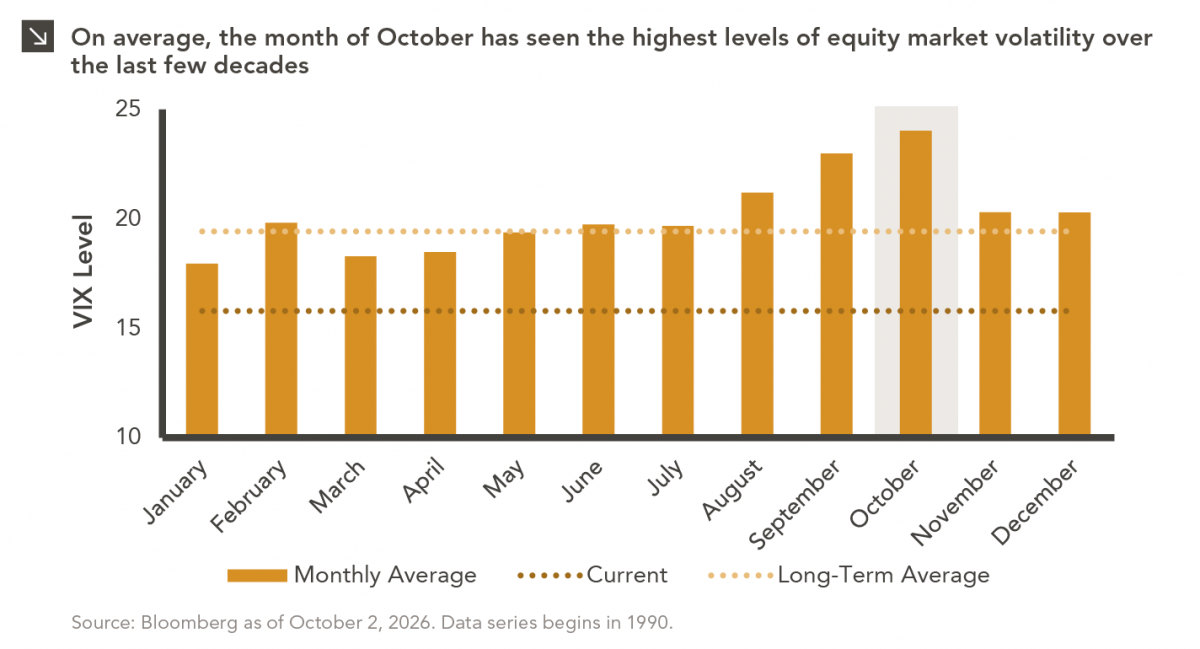
Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >