11.16.2026
Business in the Front, Party in the Back
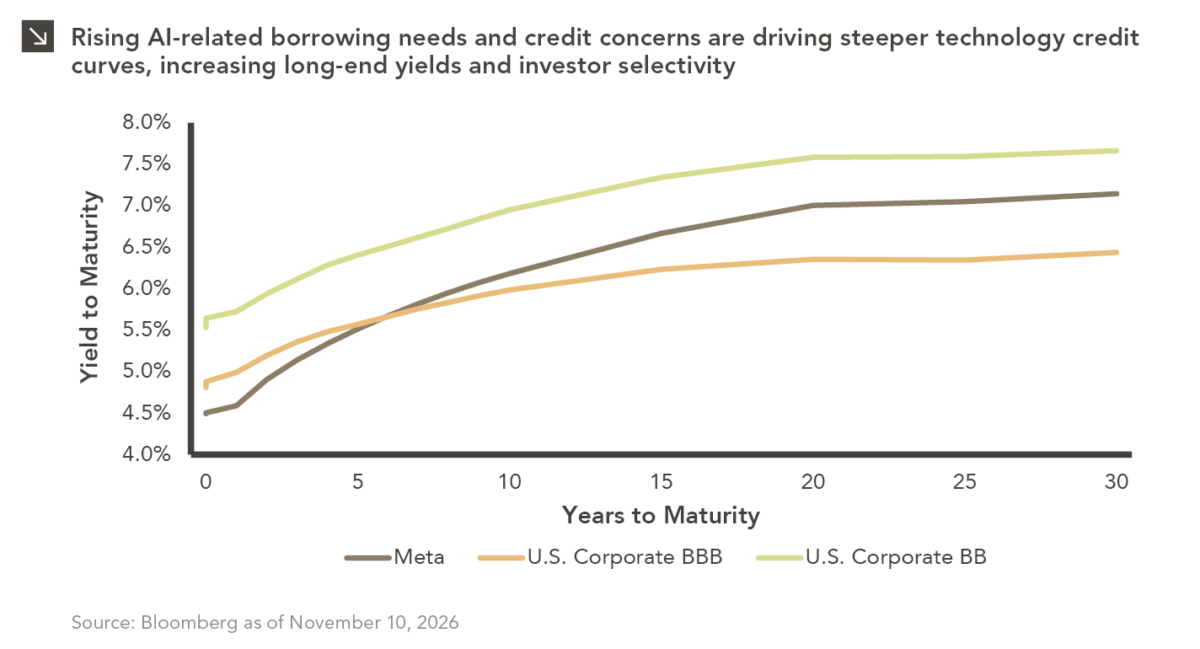
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


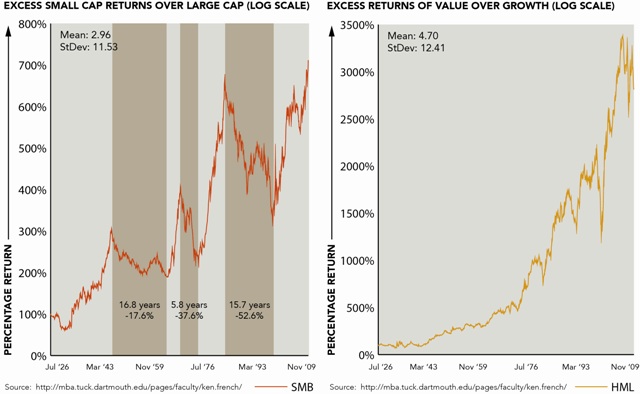
This week’s charts show the cumulative outperformance of the two Fama-French Factors, SMB and HML. SMB stands for small minus big, and is the excess performance of small market cap stocks minus large market stocks controlling for value. HML stands for high minus low, and is the excess performance of high book to market stocks minus low book to market stocks controlling for size. Graphs are shown on a log scale to highlight relative change. A change in relative size on a log scale chart is the same visual distance, which enables the viewer to more easily compare different fluctuations over time. For example, on an absolute scale graph, a price change from 50 to 100 appears much smaller than a price change from 100 to 200, even though both represent a doubling in price. On a log scale graph, these two changes appear the same.
As shown on the graphs there have historically been excess returns to small stocks and value stocks over the long term. While the volatility of both of these factors has been high (11.53 for SMB and 12.41 for HML), the value factor has earned a much higher premium over time than the size factor. This has led to long periods during which small cap stocks underperform large cap stocks, as highlighted on the graph.
While it is impossible to say given the data here, it is certainly plausible that there are business cycles that are more or less favorable to small companies compared to large companies. In fact, some academic research suggests small companies are more susceptible to shocks in profitability, which explains some of their underperformance starting in the mid 80’s. See Hou and van Dijk (2010) for more details.
The takeaway for investors is that while small caps may outperform over the long term (30 years or more), there can be extended periods during which they underperform large cap stocks. Small caps have certainly been a good bet over the past decade, but their strong performance versus large caps may or may not continue for the next.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >