10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


The U.S. dollar is the strongest it has been in a generation. The U.S. dollar index is up almost 11% this year against a basket of global reserve currencies with the greenback reaching parity with the euro last week for the first time since 2002. Like many things in financial markets, interest rates tend to be one of the most significant drivers of currency valuation, specifically the interest rate differentials between global central banks. As the Federal Reserve has pivoted to a more hawkish stance to tame decades-high inflation, other central banks, including the ECB and BOJ, have been slower to respond. When capital can flow freely, investors tend to flock to higher-yielding assets as interest rates rise, which leads to appreciation of the higher-interest rate country’s financial account and increases demand for the domestic currency — in this case, the U.S. dollar.
The Japanese yen is down roughly 16% year-to-date and is the worst performing major currency relative to the U.S. dollar. In an effort to fight decades-long deflation, the Bank of Japan has committed to holding down short-term interest rates, resulting in significant currency devaluation. Japan is the largest foreign holder of U.S. Treasuries, with $1.3 trillion as of January 2022. As the U.S. dollar strengthens, it becomes more expensive for Japan to continue to purchase on-the-run Treasury issuances, which could put further upward pressure on U.S. rates at the same time the Fed is lifting the benchmark fed funds rate and engaging in quantitative tightening. The question of what will happen when the two largest buyers of U.S. Treasuries — the Federal Reserve and the Bank of Japan — both remove liquidity from the market is another unknown that could add to market volatility in the near term.
Print PDF > The Currency Conundrum
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
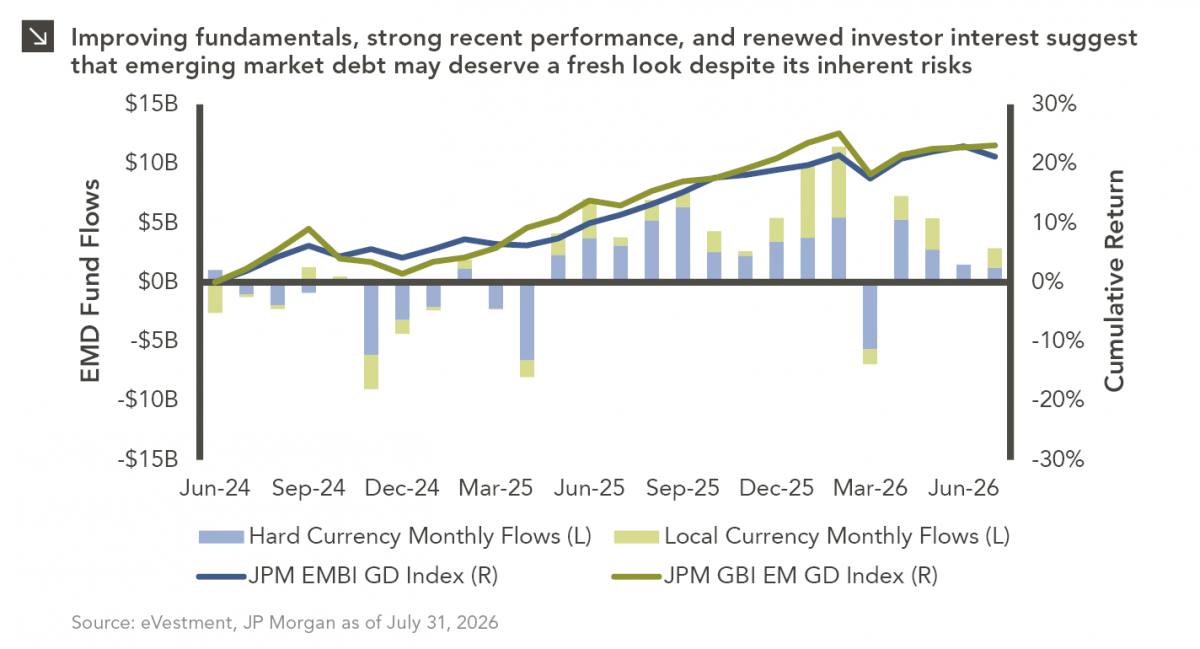
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >