James Torgerson
Senior Research Analyst


Emerging market debt (EMD) has earned a checkered reputation at best from institutional investors. The asset class is large, complex, and comes with unique risks that can lead to “throwing the baby out with the bath water” when things go wrong. 2022 was a challenging year for investors across asset classes, and emerging markets headlines ranging from the meltdown in Chinese property developers to Russia’s invasion of Ukraine only complicated the investment case for EMD. That said, historically the asset class has tended to rebound strongly from drawdown events, and that has so far been the case this year.
This newsletter revisits the dynamics of emerging markets debt, reviews 2022 performance, and discusses the investment opportunity from here.
Read > Emerging From the Depths: An Overview of the Emerging Market Debt Opportunity Set

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
09.28.2026
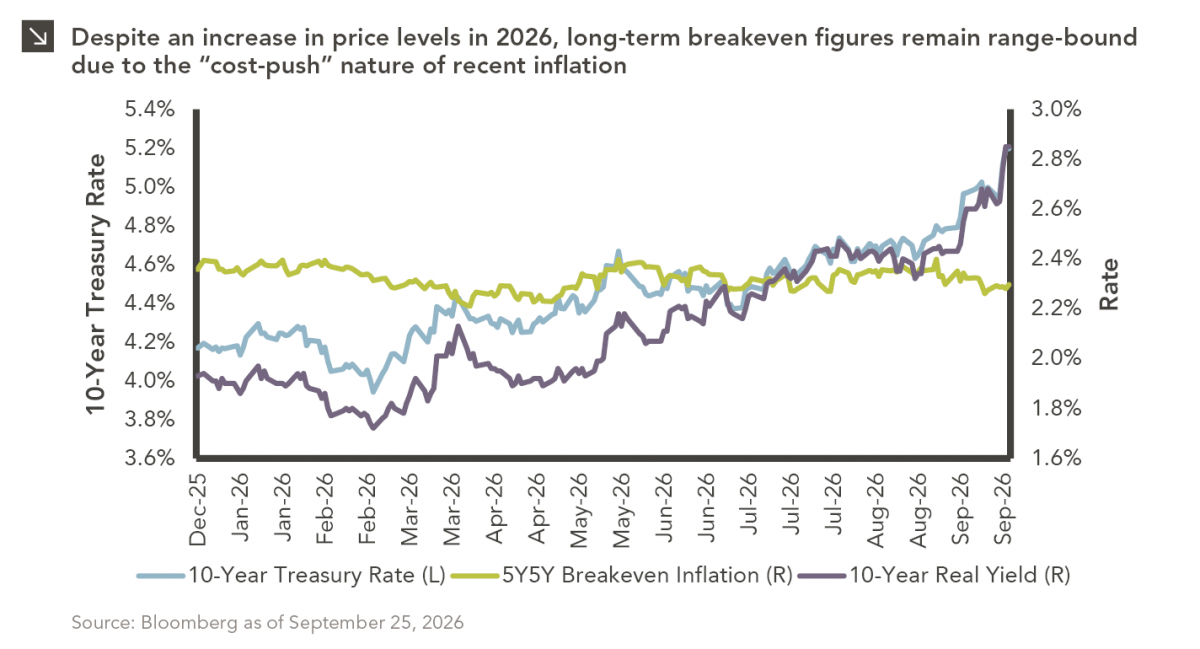
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.21.2026
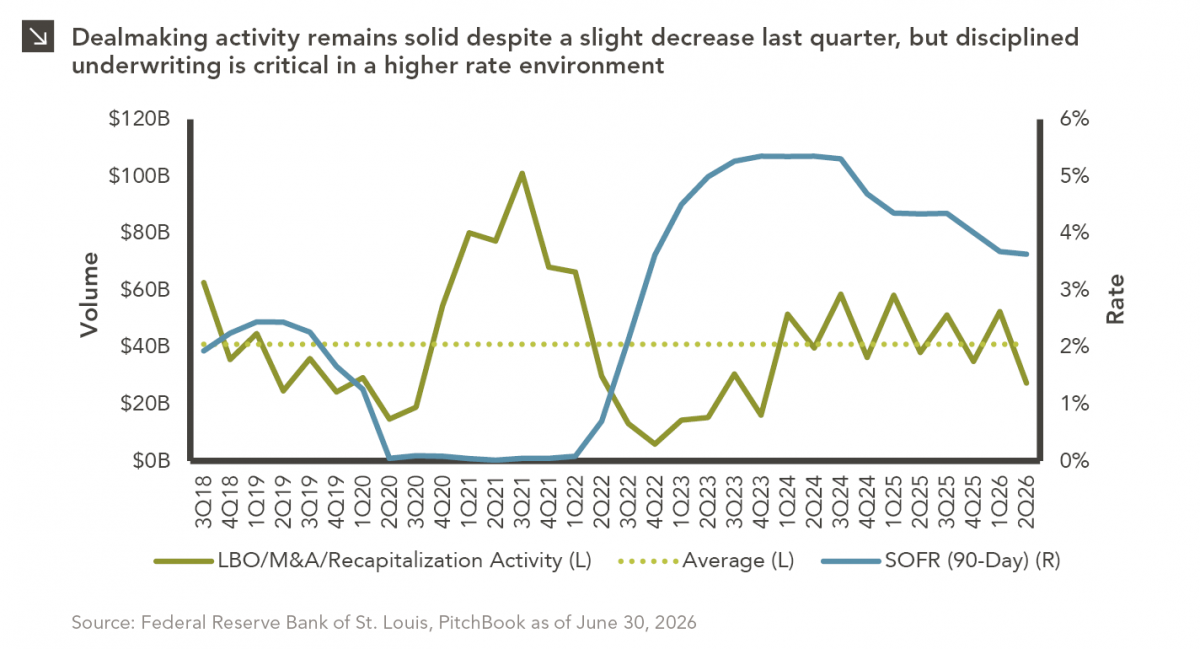
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >