Tom Salemy, CFA, CAIA
Partner


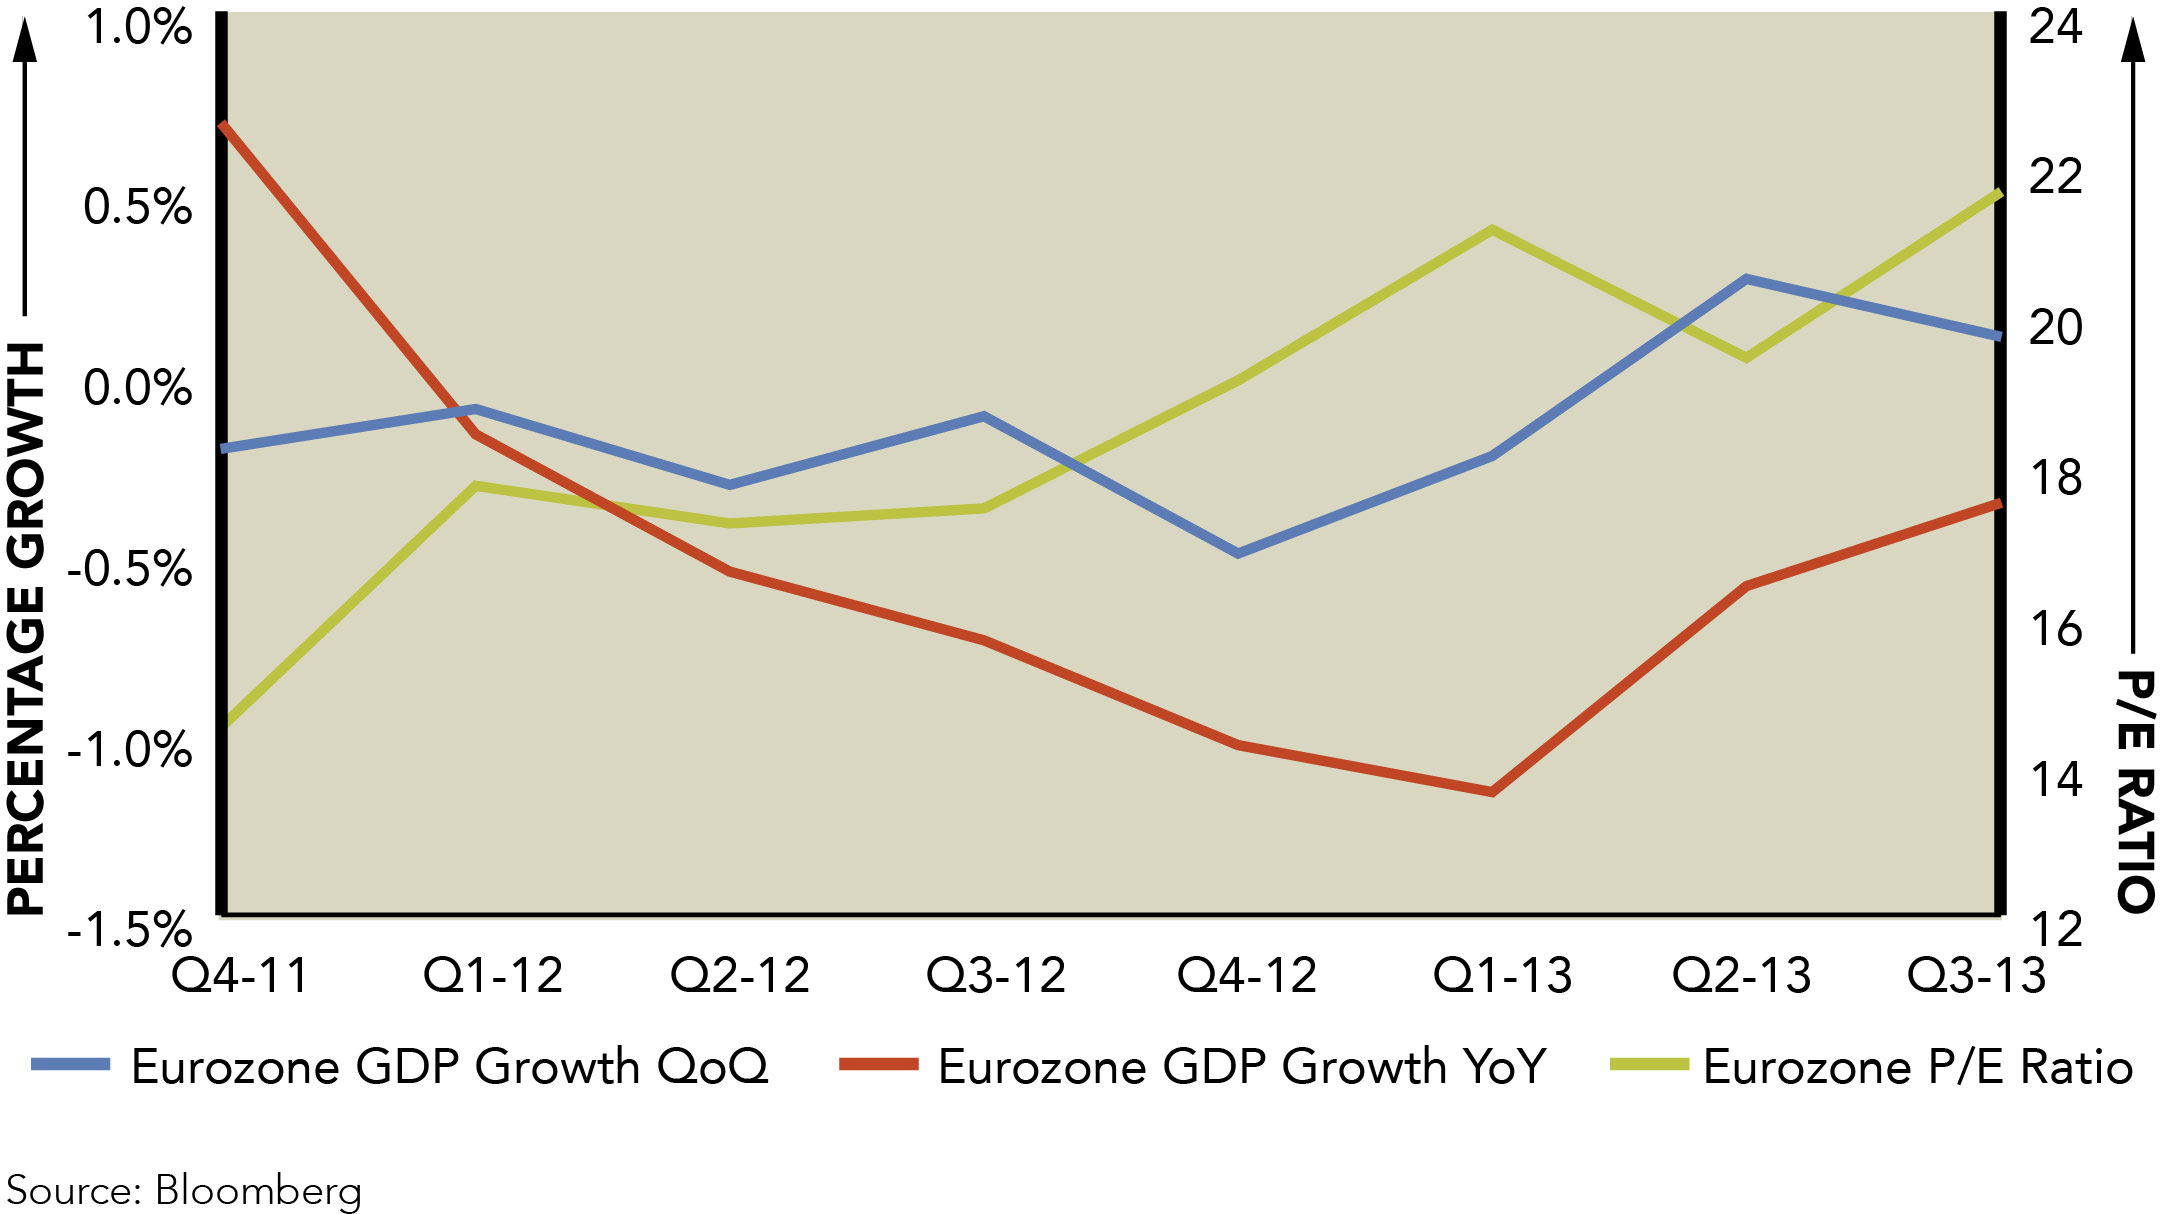
This week’s Chart of the Week examines GDP growth and valuation levels in the eurozone. The chart above depicts eurozone quarterly GDP growth compared to both the prior quarter and year. As the chart shows, eurozone GDP growth is at very low or even negative levels. Growth versus the prior year has been negative since the first quarter of 2012, while growth versus the prior quarter only recently turned positive (albeit very slow at .26%) in the second quarter of 2013.
The eurozone GDP growth or lack thereof does not seem to accurately correspond to eurozone valuation levels. As seen in the chart, the eurozone’s P/E ratio has continued to increase over the past 8 quarters despite little to no growth. The P/E ratio was 14.5 at the end of the fourth quarter of 2011. Since then, the P/E ratio has climbed to 21.6 on speculation that Europe will experience a strong recovery. However, despite continued investor optimism, the main question still remains: will the European recovery truly come to fruition?

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >