The Evolving Secondary Market

March 31, 2022 | Hayley McCollum, Senior Research Analyst

Combined stacked column and line chart showing private equity secondary market volume and single asset deals within it. Chart visual description: Left y-axis shows Secondary Market Volume in $Billions, ranging from $0 to 180. X-axis shows years from 2012 to 2021 for each column. Right y-axis shows Single Asset % from 0% to 50%. Stacked columns include the Secondary Market Volume data in teal and Single Asset Deals in dark teal. Single Asset Deals as a Percentage of Total Secondary Market Volume is displayed in an orange line overlaid on the columns. Chart data description: From 2012 to 2017, no single asset deals occurred, but have since increased exponentially, with 2018 at $2B, 2019 at $5B, 2020 at $14B, and 2021 at $32B. General secondary market volume has also increased, from $25B in 2012 to $130B in 2021. Single Asset Deals as a percentage of total secondary market volume came in at 25% in 2021. Chart sources: JPM and Preqin.

The private equity secondary market has matured and become more efficient over the last decade, with annual secondary transaction volume scaling from approximately $25 billion in 2012 to roughly $130 billion in 2021. Investors are increasingly turning to the secondary market for liquidity as they look to exit their private equity investments to better manage their overall portfolio allocations. Single asset transactions have been a more recent contributor to the growth of the secondary market, growing from 3% of total secondary transaction volume in 2018 to 25% in 2021, with a large part of this volume driven by the creation of continuation vehicles. These vehicles are quickly gaining in popularity, primarily by managers within the middle and upper end of the private equity market.

Continuation vehicles have become a hotly debated topic within the private equity community. The ability for private equity managers to recapitalize what is often their top portfolio company into a new single fund structure helps raise additional AUM and allows the manager to continue to own the company. However, it can be challenging for Limited Partners (LPs), who often lack the ability to underwrite a single company or are not given enough time to do so. Many institutional LPs are also simply unable to take the concentration risk of investing in a single asset.

As the secondary market evolves, single asset continuation vehicles are expected to become more common. LPs in private equity funds will need to evolve as well to take advantage of these opportunities and remain invested in the best assets over a longer period. This may require LPs to increase their allowable concentration limits, expand underwriting capabilities, or adjust policies in order to roll top investments into continuation funds.

Print PDF > The Evolving Secondary Market


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Hayley McCollum
Senior Research Analyst

Get to Know Hayley

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
Related Content

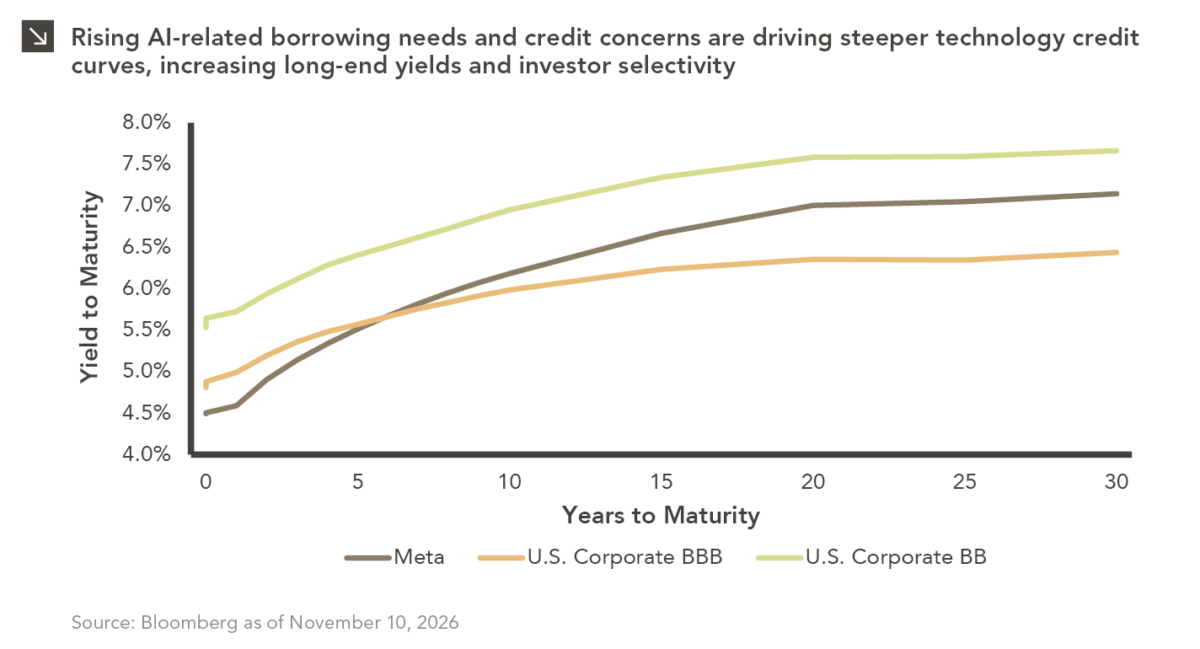
Three-line chart comparing yield to maturity across Meta, U.S. Corporate BBB, and U.S. Corporate BB bonds at maturities ranging from 0 to 30 years. Meta yields increase more sharply at longer maturities, approaching the U.S. Corporate BB curve. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.16.2026

Business in the Front, Party in the Back

Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

Line chart showing average option-adjusted spreads (OAS), in basis points, on Bloomberg CCC U.S. High Yield and Bloomberg U.S. Corporate High Yield bonds from December 2025 through October 2026. CCC-rated high yield spreads increased from approximately 600 bps to 1,100 bps, reaching their highest levels in nearly four years, while broader U.S. corporate high yield spreads remained relatively stable, increasing from approximately 260 bps to 330 bps. Source: Bloomberg as of November 6, 2026. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.09.2026

C’s Get Degrees (of Pain)

The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

Bar chart comparing October and year-to-date 2026 returns for Korea, Taiwan, Brazil, India, China, and the MSCI Emerging Markets Index. October returns are below zero for most markets, while year-to-date returns range from negative to positive. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.02.2026

The Haunting of Emerging Markets

Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

Stacked bar chart showing U.S. private equity deal value by deal size from Q1 2022 through Q2 2026. The y-axis shows percentage of total deal value from 0% to 100%, and the x-axis shows quarters by year. Stacked bar chart showing the percentage of U.S. private equity deal count by deal size from Q1 2022 through Q2 2026. The y-axis ranges from 0% to 100%, and the x-axis shows quarters by year. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.26.2026

Smaller Deals, Larger Appeal

Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026

3Q 2026 Market Insights

This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

Line chart comparing S&P 500 Index cumulative returns for midterm and non-midterm election years since 1980. The x-axis shows October through December, and the y-axis shows S&P 500 Index cumulative return, ranging from -1% to 8%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.19.2026

Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >