Jessica Noviskis, CFA
Portfolio Strategist, OCIO Services


Fitch Ratings unexpectedly downgraded the U.S. government’s credit rating one notch from AAA to AA+ on August 1, 2023. This is only the second downgrade in history, after S&P Global Ratings, then Standard & Poor’s, made the same adjustment shortly after the 2011 debt ceiling crisis; S&P has maintained the AA+ rating since. Moody’s — the third major U.S. rating agency — still has the U.S. at its highest Aaa rating. Fitch noted the downgrade reflects expected fiscal deterioration over the next three years, the country’s high and growing debt burden, and an erosion in governance over the last several years, marked by bipartisan standoffs and last-minute resolutions. The downgrade and timing have drawn criticism from the Biden administration and economists, citing economic strength and the minuscule risk of the U.S. actually missing any debt payments.
While in practice the downgrade will likely have minimal impact, with the U.S. government broadly considered one of the safest borrowers, markets are reacting. Treasuries initially rallied on the news, anticipating the same flight to quality seen in 2011, though that sentiment reversed this morning, with yields at one point breaching a key resistance level of 4.1% — a level last seen in November 2022. Also likely contributing to the move today is the Treasury Department’s announced plans to sell a higher-than-expected amount of longer-dated securities next week, as it works to replenish the Treasury General Account (reference Marquette’s recent newsletter for additional context). The U.S. dollar initially dipped on the news but has since rallied and is up on the day amid higher yields. U.S. equities, after a steep run, are down modestly today, with growth equities leading the group lower.
Print PDF > Fitch Downgrades U.S. Credit

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
09.28.2026
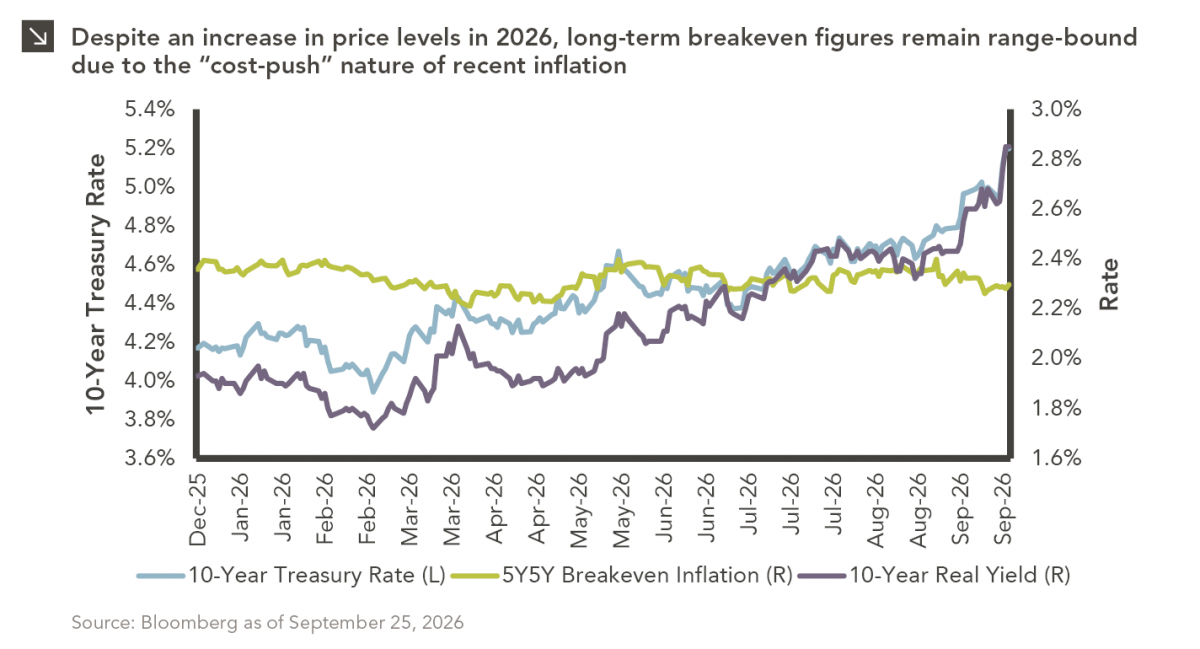
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.21.2026
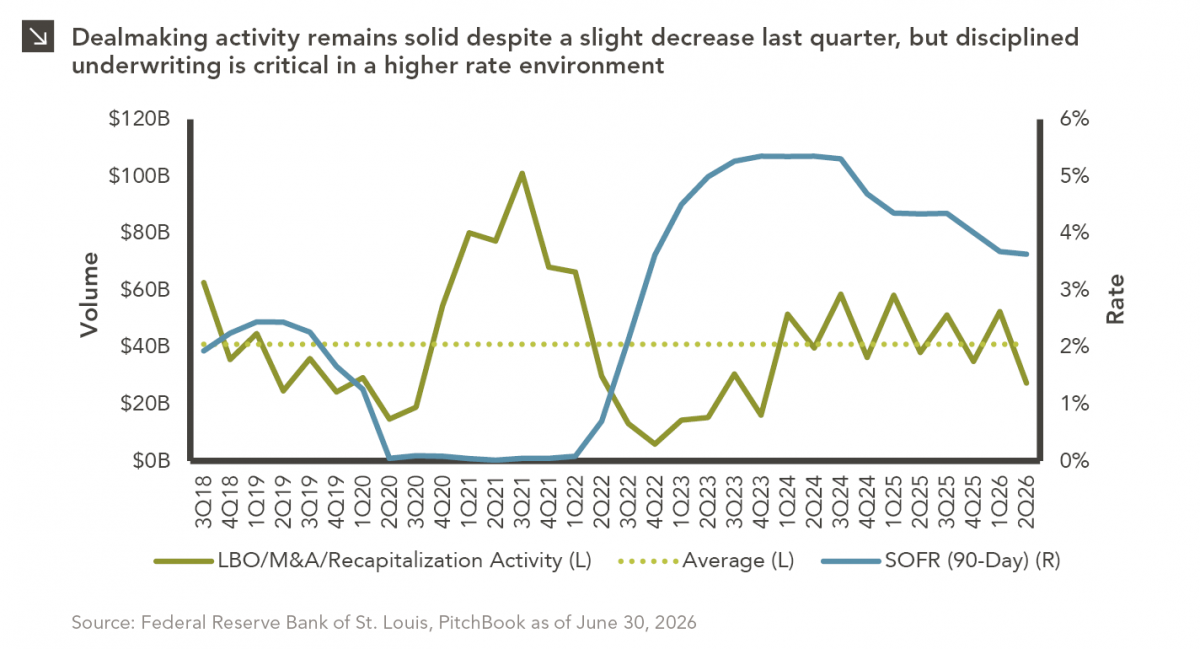
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >