GICS Reclassifies Away From Tech, Again

April 20, 2023 | Catherine Hillier, Senior Research Analyst

This chart description is for illustrative purposes only and its accuracy cannot be guaranteed. Please see full disclosures at end of PDF document in the web post. General description: Column chart showing S&P 500 sector weightings from Dec 31 2022 to Mar 31 2023. Chart subtitle: The Financials and Technology sectors were the most impacted by the latest GICS reclassification. Chart source: Bloomberg as of March 31, 2023. Chart visual description: Y-axis is labeled “S&P 500 Sector Weight” and ranges from 0% to 35%. X-axis shows each of the GICS categories: Comm. Svcs, Cons. Discr, Cons. Staples, Energy, Financials, Health Care, Industrials, Info. Tech., Materials, Real Estate, Utilities. Each category has a column in light blue for 12/31/2022 weighting, darker blue for 3/17/2023, green for 3/20/2023, and light green for 3/31/2023 showing weighting before and after reclassification. Financials and Info. Tech. categories are outlined with orange dashed rectangle to highlight. Chart data description: Most categories are relatively the same; as described in the write-up, however, Financials and Info. Tech. were both adjusted during reclassification. Financials’ weighting went from 11.66% as of 12/31 to 10.28% 3/17 to 13.02% 3/20 and is now at 12.91%. IT went from 25.74% 12/31 to 29.02% 3/17 to 25.76% 3/20 and is now at 26.08%. End chart description. See disclosures at end of document.

The Global Industry Classification Standards (GICS) were established in 1999 by MSCI and S&P Dow Jones Indices to categorize publicly-traded equities. Broadly accepted across the industry, the GICS classification system undergoes an annual review, which has resulted in only 12 updates to the classification system since inception. These updates can have significant impacts on the underlying performance drivers of sectors as well as the concentration of sector-specific indices. The Technology sector has been meaningfully impacted by the two most recent updates. In 2018, GICS broke the Technology sector up to create the Communication Services sector, which includes FAANG stocks Meta, Netflix, and Alphabet. While the update was less consequential this year, it again relocated some of the Tech sector’s largest constituents, increasing its concentration to new highs.

Effective after the close on March 17, 2023, 14 firms were reclassified, impacting five GICS sectors. Notably, Visa and Mastercard, previously two of the five largest Technology companies, along with PayPal, Fiserv, and others, were reclassified as Financials. As a result, the Financials sector is now more exposed to growth factors, including, on the margin, valuation risk from rising rates. The Technology sector, conversely, has become even more concentrated in two mega-cap stocks — Apple and Microsoft. The resultant weighting and concentration changes will impact active manager attribution metrics as well as the exposures achieved via sector-specific ETFs and are important for investors to be aware of. Lastly, while not implemented this year, another key proposal discussed concerned renewable energy companies. These stocks are generally categorized within the Energy and Utilities sectors, and future changes could represent another meaningful shift in GICS classifications.

Print PDF > GICS Reclassifies Away From Tech, Again


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Catherine Hillier
Senior Research Analyst

Get to Know Catherine

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

10.08.2026

3Q 2026 Market Insights Webinar

LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

Line chart showing 10-year U.S. Treasury rate, 5-year/5-year breakeven inflation rate, and 10-year real yield from December 2025 through September 2026. The left axis shows rates from 3.6% to 5.4%, and the right axis from 1.6% to 3.0%. The Treasury rate and real yield rise notably in late 2026, while the breakeven inflation rate remains relatively range-bound around 2.3%–2.4%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.28.2026

Getting Real on Inflation

The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

Dual-axis line chart comparing LBO/M&A/Recapitalization Activity, its average level, and the SOFR (90-Day) rate from 3Q18 through 2Q26. LBO/M&A/Recapitalization Activity ranges from approximately $0 billion to $100 billion, while SOFR ranges from 0% to approximately 5%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.21.2026

Let’s Make a Deal

For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

Line chart comparing annualized return and annualized risk for stock-bond portfolio combinations from 1976-2019 and 2020-2026. Two lines show the range of return and risk outcomes across portfolio allocations during each period. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.14.2026

No More Free Lunch?

There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
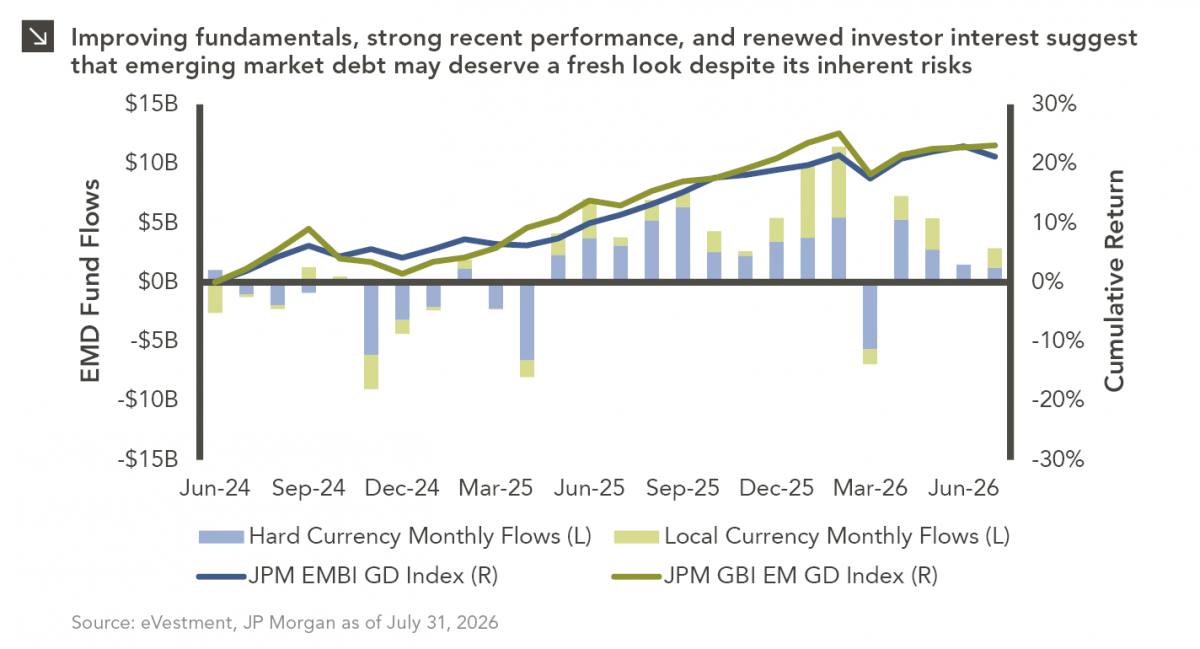
Combination stacked column and line chart comparing EMD fund flows (columns) and index cumulative returns (lines), June 2024 to present. Indices used: JPM EMBI GD Index and JPM GBI EM GD Index. Since May 2025, Monthly Flows have been positive, with the exception of March 2026. Most recent datapoint: July 31, 2026 Hard Currency Flows $1.2B, Local Currency $1.6B, JPM EMBI GD Index at 21.2%, JPM GBI EM GD Index at 23.1%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.08.2026

EMD’s Second Chance?

Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >