Jessica Noviskis, CFA
Portfolio Strategist, OCIO Services


Rising inflation and interest rates have not been real issues for investors for several years, but both have remained popular topics of concern. While inflation does not appear to be an immediate risk given still depressed GDP and elevated unemployment, the size of the latest proposed $1.9 trillion COVID relief package has many thinking about future implications. Stimulus did not lead to inflation following the Global Financial Crisis, but there are a number of reasons, beyond the sheer size of this effort, that we could see greater inflationary pressures this time: more pent-up consumer demand, well-capitalized banks and healthy consumer balance sheets, de-globalization, and higher operational costs associated with the virus. And while the Federal Reserve has committed to maintaining its ultra-accommodative monetary policy until long-term inflation hits 2% (with shorter-term inflation allowed to rise moderately above 2% for some time), unless the Fed changes its stance on negative rates, rates can only go in one direction from here: up.
Like all things market-related, we do not recommend trying to time inflation or interest rates. In this newsletter, we analyze equity long/short hedge funds as an option for investors to potentially optimize their portfolio for this dynamic environment.
Read > Hedging Rising Inflation and Interest Rates

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
09.15.2026
Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…

08.24.2026
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…

08.17.2026
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…
08.10.2026
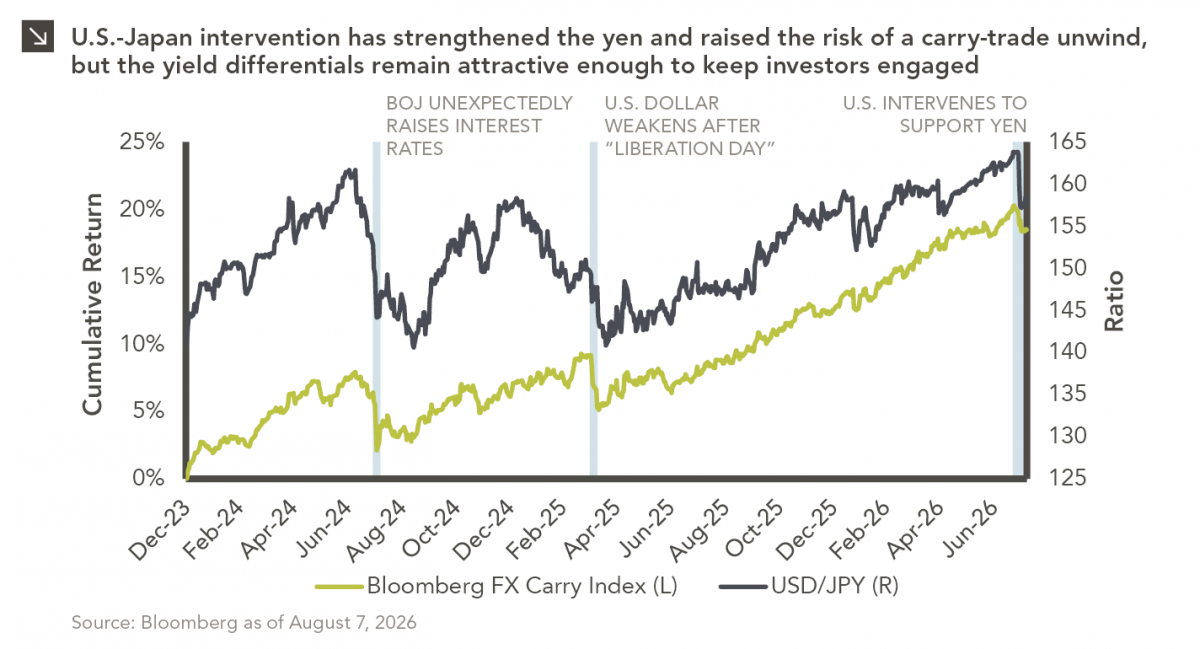
After reaching nearly ¥164 per dollar, its weakest level in roughly four decades, the yen had become a source of…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >