Assessing the Likelihood of a Recession and Understanding the Impact on Portfolios

March 26, 2024 | Frank Valle, CFA, CAIA, Associate Director of Fixed Income, Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research, Catherine Hillier, Senior Research Analyst, David Hernandez, CFA, Director of Traditional Manager Search, Evan Frazier, CFA, CAIA, Senior Research Analyst, James Torgerson, Senior Research Analyst, Jessica Noviskis, CFA, Portfolio Strategist, OCIO Services

Is a recession coming to the U.S.? It’s a question that has been asked since 2022, as the Fed’s rapid rate hikes sparked concern that higher interest rates would lead to demand destruction and ultimately economic contraction. Nonetheless, here we are in the first quarter of 2024 and although the growth rate of gross domestic product has fallen, it is still positive. Unemployment remains at historic lows and inflation is falling. However, with the Fed unlikely to cut rates during the first half of the year and the full effect of the higher rate environment not yet settled, the recession threat still looms over the economy and markets. Given this background, the following paper presents three reasons for each side as to whether the U.S. may enter or avoid a recession in 2024, as well as recessionary implications across asset classes.

Read > Assessing the Likelihood of a Recession and Understanding the Impact on Portfolios

Frank Valle, CFA, CAIA
Associate Director of Fixed Income

Get to Know Frank

Greg Leonberger, FSA, EA, MAAA, FCA
Partner, Director of Research

Get to Know Greg

Catherine Hillier
Senior Research Analyst

Get to Know Catherine

David Hernandez, CFA
Director of Traditional Manager Search

Get to Know David

Evan Frazier, CFA, CAIA
Senior Research Analyst

Get to Know Evan

James Torgerson
Senior Research Analyst

Get to Know James

Jessica Noviskis, CFA
Portfolio Strategist, OCIO Services

Get to Know Jessica

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

Line chart showing 10-year U.S. Treasury rate, 5-year/5-year breakeven inflation rate, and 10-year real yield from December 2025 through September 2026. The left axis shows rates from 3.6% to 5.4%, and the right axis from 1.6% to 3.0%. The Treasury rate and real yield rise notably in late 2026, while the breakeven inflation rate remains relatively range-bound around 2.3%–2.4%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.28.2026

Getting Real on Inflation

The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

Dual-axis line chart comparing LBO/M&A/Recapitalization Activity, its average level, and the SOFR (90-Day) rate from 3Q18 through 2Q26. LBO/M&A/Recapitalization Activity ranges from approximately $0 billion to $100 billion, while SOFR ranges from 0% to approximately 5%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.21.2026

Let’s Make a Deal

For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.15.2026

Continuation Vehicles: Worth the Wait?

Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…

Line chart comparing annualized return and annualized risk for stock-bond portfolio combinations from 1976-2019 and 2020-2026. Two lines show the range of return and risk outcomes across portfolio allocations during each period. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.14.2026

No More Free Lunch?

There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…

Five-line chart comparing yield on 30-year debt instrument for the United States, United Kingdon, France, Germany, and Japan, December 2021 to August 21, 2026. First data point in order listed previously: 1.9%, 1.1%, 0.9%, 0.2%, 0.7%. Most recent: 5.3%, 5.8%, 4.9%, 3.8%, 4.1%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

08.24.2026

Long Weakened

The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…
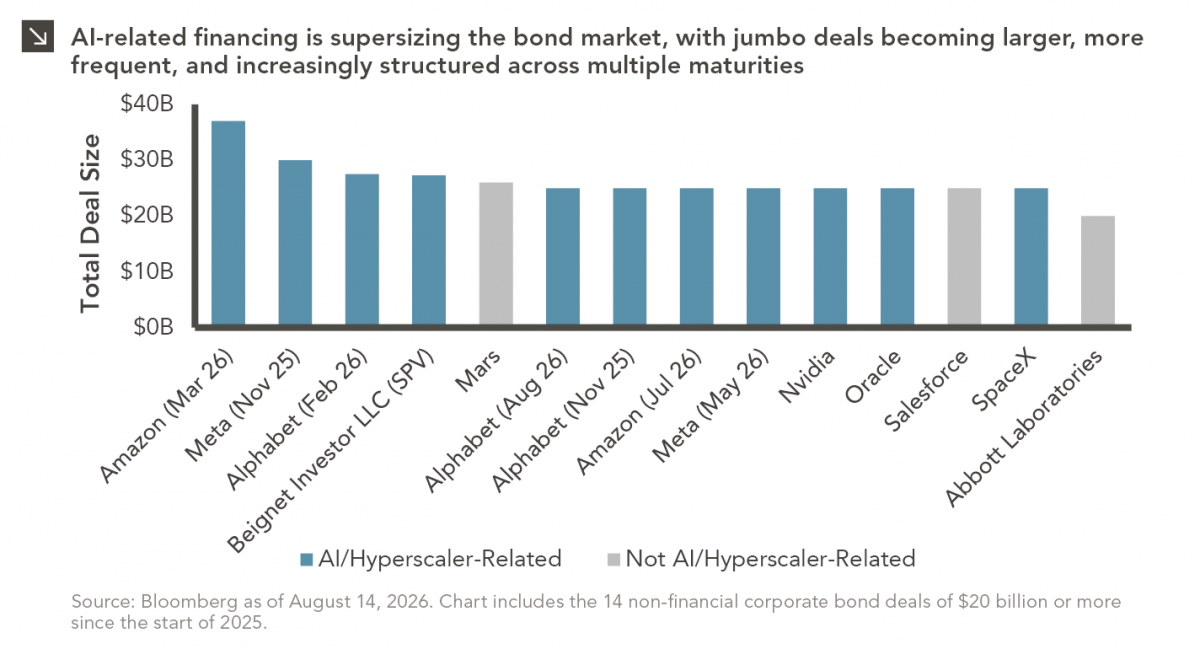
Column chart showing total deal size for 14 non-financial corporate bond deals of $20B or more since the start of 2025. Out of 14, only three were unrelated to AI or hyperscalers. For full dataset, please contact marquettemarketing@marquetteassociates.com.

08.17.2026

Supersize Me!

As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >