10.19.2026
Divided We Rise?
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…


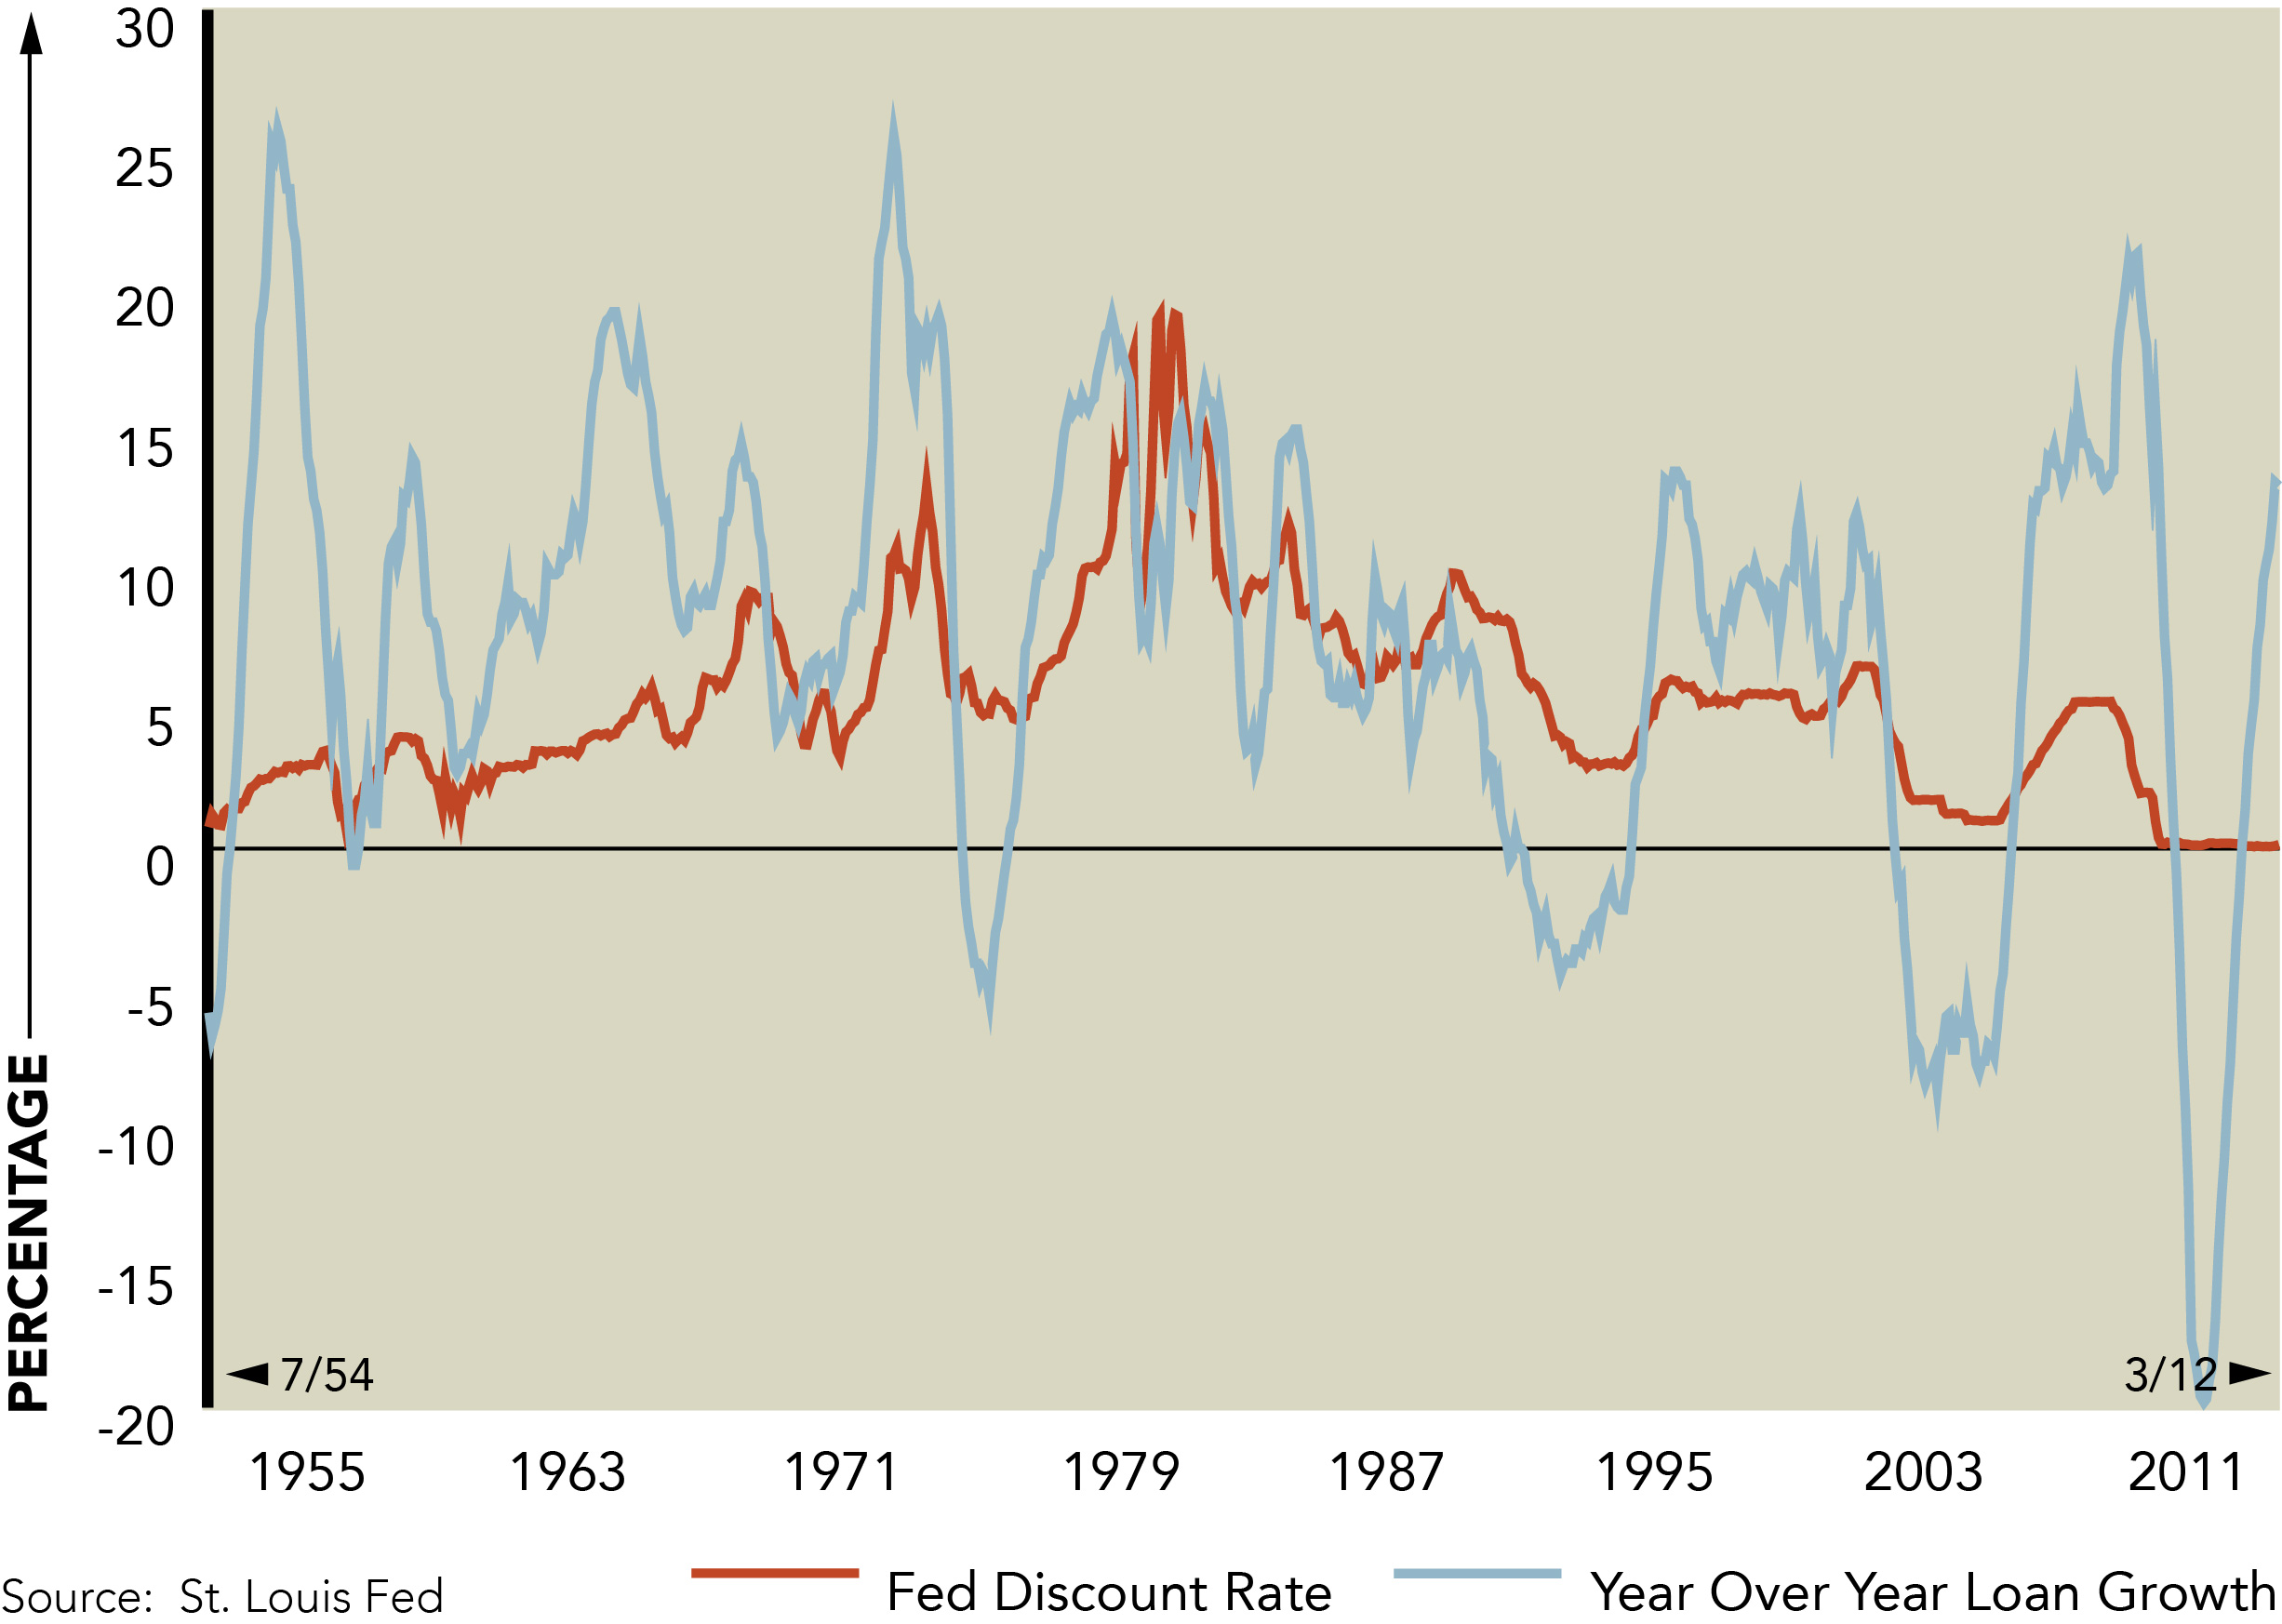
Since the 2008 recession began, the Federal Reserve has seemingly used all available tools to stimulate the economy. In particular, the Fed has relied heavily on controlling the Federal Funds Rate, which is the rate that the Fed charges banks for overnight loans. By keeping this discount rate low, the Fed can theoretically stimulate loan growth by making credit cheaper for banks to obtain.
In this week’s Chart of the Week, the percentage change (year over year) of total commercial and industrial loans issued by all commercial banks is compared to the Fed Funds rate. Historically, these have moved in tandem as the Fed raises the rate to control growth of credit during expansions and lowers the discount rate to stimulate credit during recessions. Recently, the Federal Reserve has held the Fed Funds rate near zero in response to the largest contraction of total loans over the last 60 years. It is also interesting to note that despite recent loan growth of nearly 15%, the Fed continues to maintain a near-zero Fed Funds rate.
Although the economy continues to grow more slowly than anyone would like, the recent year over year surge in commercial and industrial loans offers some cause for optimism. Typically, loan growth leads to economic expansion as companies resume investments that were delayed during the previous recession. This direct investment spending helps current economic growth while the resulting increase in productivity from investment drives long term economic growth. As long as the Fed remains committed to keeping the Fed Funds rate near zero for the foreseeable future, it looks like loan volumes should continue to grow and help spur economic growth.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >