11.16.2026
Business in the Front, Party in the Back
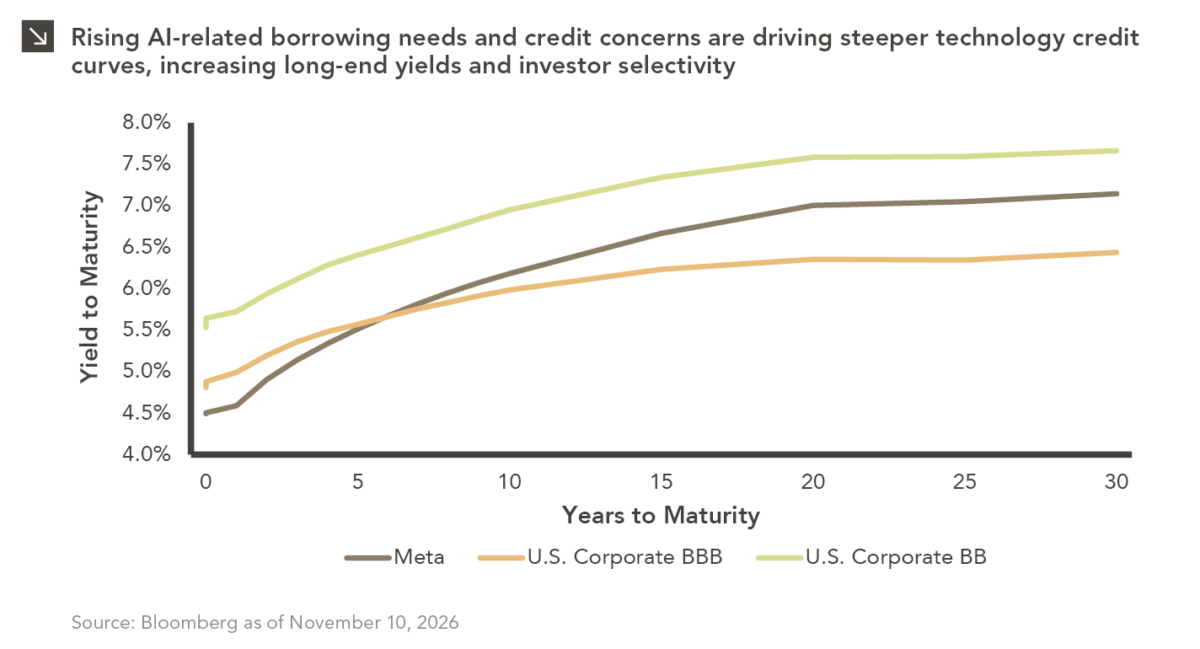
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


With Trump’s surprise announcement of additional tariffs at the beginning of this month — a day after the Fed’s rate cut — the yield curve continued its free fall and flattening that began in earnest at the beginning of 4Q18’s dislocation and the gradual heating-up of the tariff war. Sunday’s Argentine Presidential primary election surprise, where pro-free markets incumbent Macri lost to populist duo Fernandez/Kirchner by a wider than expected margin, further exacerbated that trend.
In this newsletter, we examine the driving forces behind this persistent yield curve decline and flattening and potential remedies to the “lower for longer” norm.
Read > Lower for Longer, or Negative Forever?
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
09.28.2026
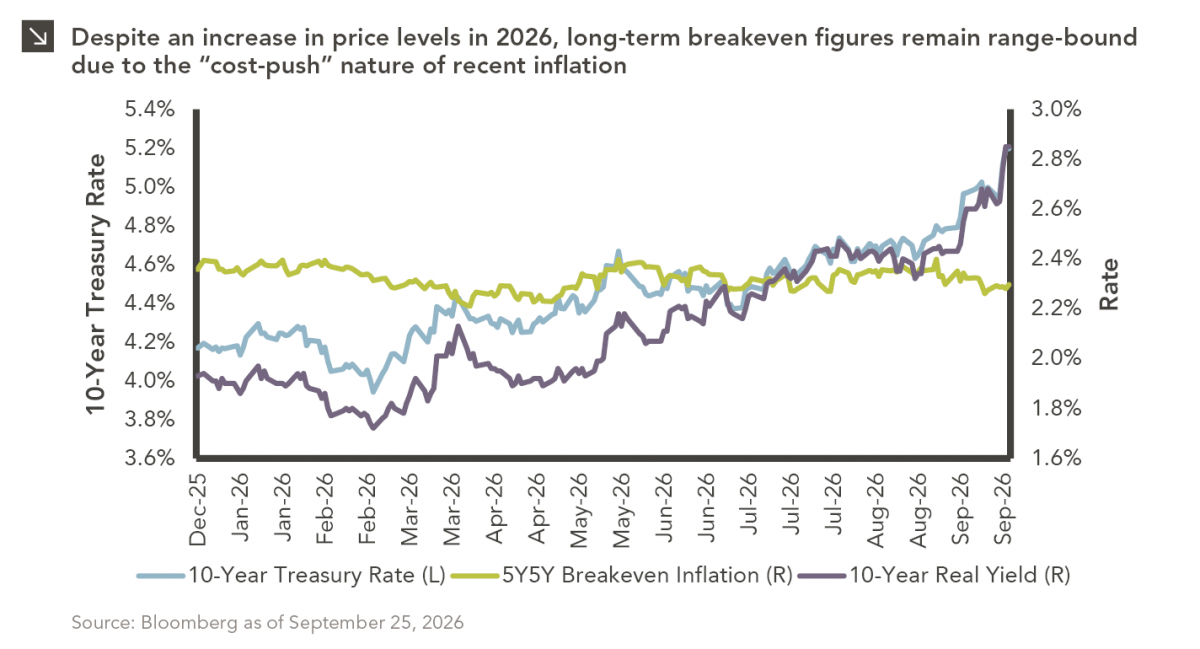
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.21.2026
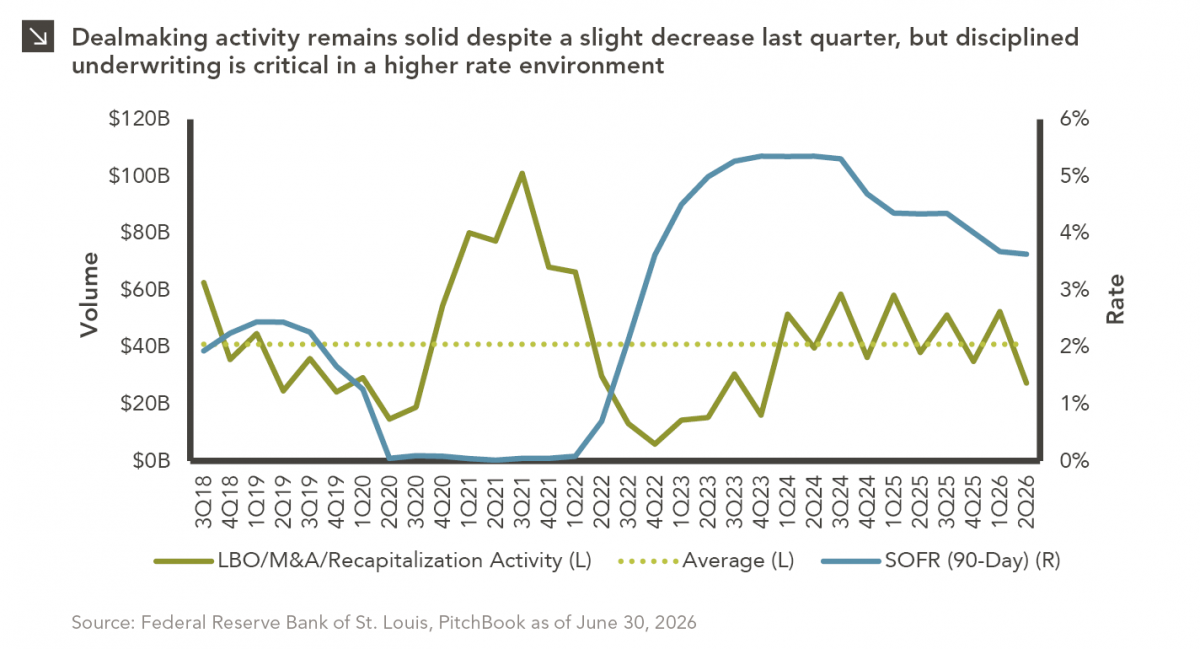
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >