11.16.2026
Business in the Front, Party in the Back
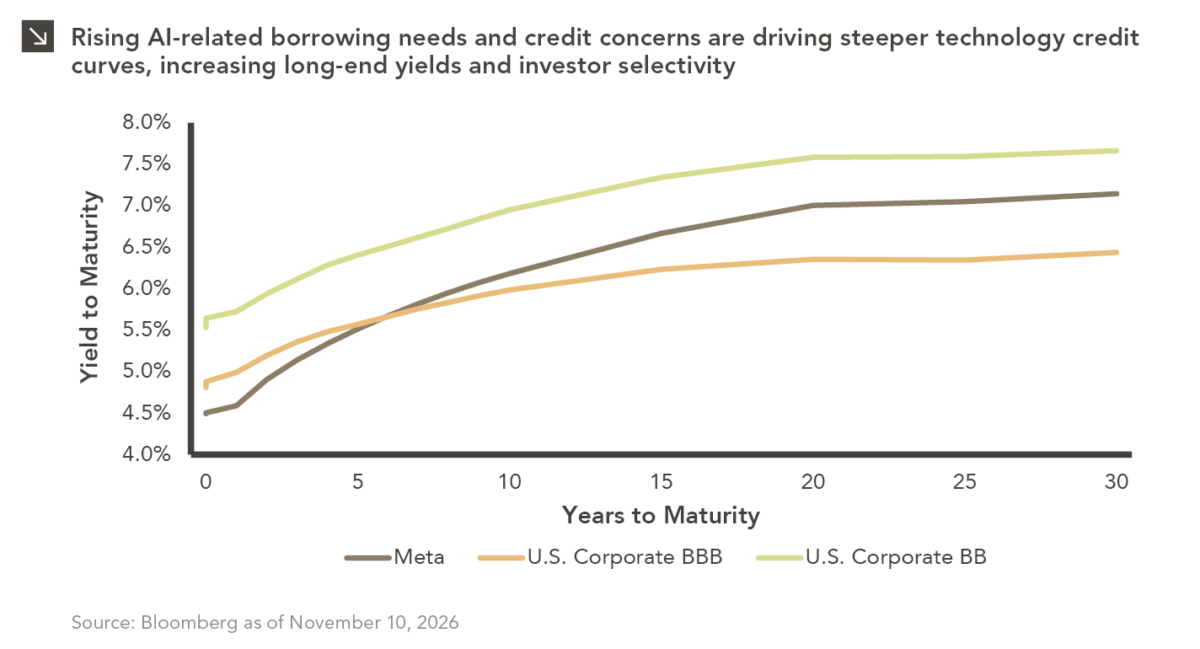
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


Historically, two indices have moved hand-in-hand: the Global Economic Policy Uncertainty Index and the VIX Index. The former is a measurement of uncertainty surrounding economic and political policy on a global scale, while the latter is a gauge of the volatility level for the S&P 500 index. The relationship between the two should not be surprising: as uncertainty increases, equity volatility rises. What is surprising is the recent divergence of the two. While global economic policy uncertainty surged to recent highs, market volatility is close to 20-year lows. Since the late 1990s, the 3-month rolling correlation between these indices has hovered around 60%; a divergence of the two to this extreme has not been seen in recent history. So what has caused this disparity?
One answer could be the election of Trump, which could explain the directionality of both indices. The contradictory nature of White House statements versus direct quotes from Trump himself oftentimes leaves the public unsure of what to expect next, as it relates to policy direction. Meanwhile, markets have climbed from the “Trump Effect,” which reflects optimism about the successful implementation of new business-friendly policies. An alternative explanation could simply be that company earnings have been sufficiently strong to support current valuation levels. Though there is global policy uncertainty domestically and internationally — notably due to the populist movement in Europe — strong earnings have more than offset this policy uncertainty and thus driven markets higher and perceived risk lower.
Can both sentiments concurrently be correct? This trend certainly hasn’t been the case in recent years, however, the divergence has continued since Trump’s inauguration. Only time will tell if one of these indicators is truly victorious.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >