11.16.2026
Business in the Front, Party in the Back
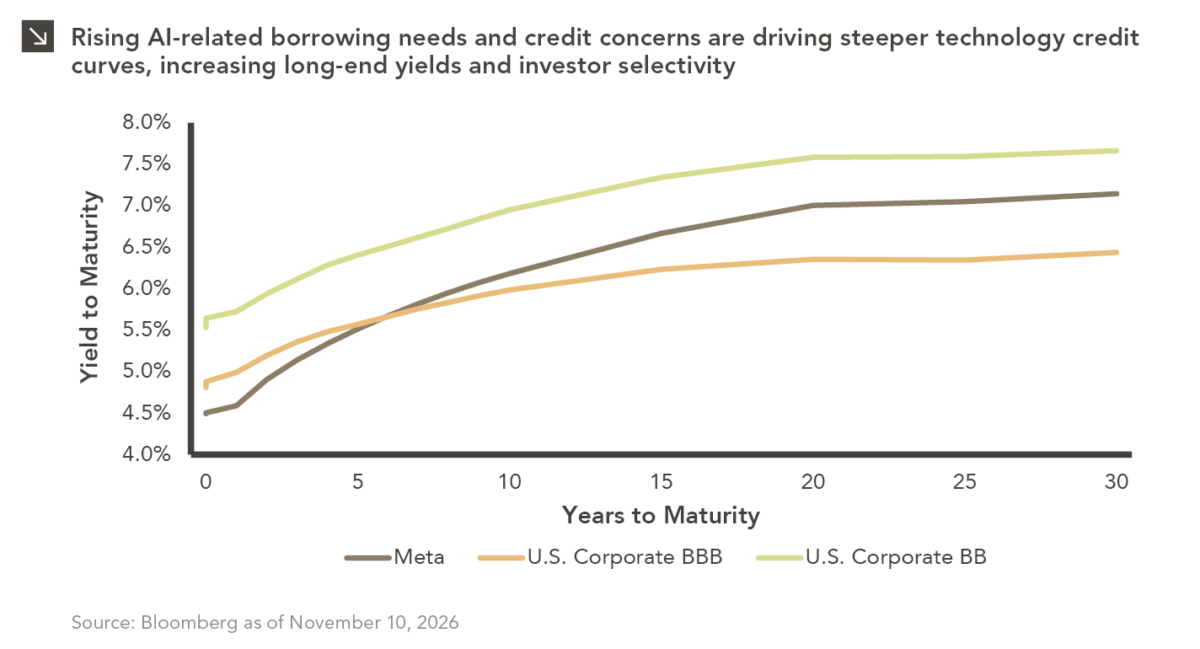
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


Despite the enormous challenges of 2020, financial markets have rebounded. While baffling at face value, the contrast between market performance and the widespread suffering due to COVID-19 is more understandable in the context of markets as a representation of human ingenuity and resiliency. These two traits are perhaps most recognized in the world’s foremost economic superpowers: The United States and the People’s Republic of China. During the third week of March, both countries saw market drawdowns near 30%; most other equity indices across the world saw similar drops. Since the global market bottom, countries have been racing to make up these losses and charge ahead to new highs. As of December 11th, America’s recovery has been nearly a third stronger than China’s. Globally, the recovery has fallen in between these two world powers.
A dollar invested in American public equities on March 23rd would have grown to $1.72 as of last Friday, December 11th, as represented by the Russell 3000 (representing approximately 98% of the investable U.S. equity market¹). Over this same time span, a dollar invested in China would have driven an increase to $1.54, as represented by the MSCI China Index. This broad market index captures 85% of China’s equity universe and includes the variety of share classes available to both strictly domestic Chinese investors as well as foreign investors.² However, America’s strength in capital markets recovery does not reflect the country’s relative success in managing the virus. In the U.S., the fight drags on, while much of China has returned to business as usual.³ Broadly, capital markets as measured by the All Country World Index (ACWI) — which contains 85% of the global equity markets, including 23 developed countries and 26 developing countries² — has rebounded at a clip between that of the U.S. and China. The good news for investors is that equity markets — regardless of home country — have rebounded from the extreme drops seen in March and April.
As detailed in our previous Chart of the Week, “Main Street Won’t Look Like Wall Street for a While,” the real-world experience of many Americans is one of continued economic hardship. While this desperate situation may soon be addressed with additional stimulus, Americans and people around the globe can also find hope in the fact that markets are forward-looking and humans, by nature, are resilient and resourceful. As a testament to this, one needs to look no further than the rollout of the highly anticipated and historic COVID-19 vaccine, which saw its first doses administered in the U.S on Monday.⁴ The extreme market volatility and large sell-off early in the year and subsequent recovery have further underscored why a long-term investment perspective rooted in a fundamental confidence in continual technological and economic progress is the most effective mindset an investor can have.
Print PDF > Market Recovery: Superpower Showdown
¹ FTSE Russell
² MSCI
³ China is back to normal — the US and Europe are not. Here’s how it succeeded
⁴ First Covid-19 Vaccine Given to U.S. Public
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >