More Bang for Your… EM Local Currency?

June 29, 2023

This chart description is for illustrative purposes only and its accuracy cannot be guaranteed. Please see full disclosures at end of PDF document in the web post. General description: Two-line chart comparing yield for JPM GBI-EM Global Diversified Index with the U.S. 10-Year. Chart subtitle: EM local yields remain at elevated levels relative to their history. Chart source: J.P. Morgan, Bloomberg as of June 26, 2023. Chart visual description: Y-axis is labeled “Yield” and ranges from 0% to 10% in 1% increments. X-axis is labeled annually, from June 2005 through June 2023. Slate line plots JPM GBI-EM Global Diversified Index and light blue line plots U.S. 10-Year. Chart data description: Yields for both indices move generally parallel, though the emerging markets index is typically at about 2% points higher than the U.S. 10-Year. Most recent data point: EM at 6.28% and U.S. 10-Year is at 3.72%. Please contact us for the full data set. End chart description. See disclosures at end of document.

Local currency emerging markets debt has been one of the standout fixed income asset classes this year. The J.P. Morgan GBI-EM Global Diversified Index — which tracks local currency bonds issued by emerging market governments — is up nearly 5% year-to-date.¹ This compares with the Bloomberg US Agg up 2.5% over the same period. Yields for the emerging markets index peaked in the fourth quarter of 2022 and remain near multi-year highs. Local currency EM debt could stand to benefit for three reasons: higher starting yields, proactive emerging markets central banks, and emerging versus developed GDP growth differentials.

  • Real yields in EM local currency debt are at attractive levels relative to history as well as relative to developed markets. As of June 26, GBI-EM yields were 6.28%. This compares with the U.S. 10-year Treasury yield at 3.72%. This yield differential compensates investors for the higher risk and positions them to benefit from yield compression if global macro headwinds start to abate.
  • Several EM countries such as Brazil and Mexico began their rate hiking cycles much sooner than their developed market counterparts. To the extent that positions these emerging central banks to cut policy rates sooner than the rest of the world, yield compression could benefit total asset class returns.
  • EM local currency debt should benefit from higher GDP growth than is expected in developed markets. Based on projections from the International Monetary Fund, EM economies are projected to grow approximately 4% per annum through 2024. This compares to advanced economies, where real GDP is projected to grow roughly 1.5% through 2024.

In sum, a number of tailwinds could continue to position EM local currency debt for strong relative returns as the year progresses.

Print PDF > More Bang for Your… EM Local Currency?

¹Through June 26, 2023


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

Line chart showing average option-adjusted spreads (OAS), in basis points, on Bloomberg CCC U.S. High Yield and Bloomberg U.S. Corporate High Yield bonds from December 2025 through October 2026. CCC-rated high yield spreads increased from approximately 600 bps to 1,100 bps, reaching their highest levels in nearly four years, while broader U.S. corporate high yield spreads remained relatively stable, increasing from approximately 260 bps to 330 bps. Source: Bloomberg as of November 6, 2026. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.09.2026

C’s Get Degrees (of Pain)

The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

Bar chart comparing October and year-to-date 2026 returns for Korea, Taiwan, Brazil, India, China, and the MSCI Emerging Markets Index. October returns are below zero for most markets, while year-to-date returns range from negative to positive. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.02.2026

The Haunting of Emerging Markets

Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

Stacked bar chart showing U.S. private equity deal value by deal size from Q1 2022 through Q2 2026. The y-axis shows percentage of total deal value from 0% to 100%, and the x-axis shows quarters by year. Stacked bar chart showing the percentage of U.S. private equity deal count by deal size from Q1 2022 through Q2 2026. The y-axis ranges from 0% to 100%, and the x-axis shows quarters by year. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.26.2026

Smaller Deals, Larger Appeal

Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

Line chart comparing S&P 500 Index cumulative returns for midterm and non-midterm election years since 1980. The x-axis shows October through December, and the y-axis shows S&P 500 Index cumulative return, ranging from -1% to 8%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.19.2026

Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

Chart #1 - Line chart showing PJM summer peak load estimates in gigawatts (GW) from 2015 to 2045. The chart compares historical peak load, current capacity, and forecasts from 2024, 2025, and 2026, showing projected demand rising above current capacity over time. Chart #2 - Stacked bar chart showing U.S. power demand in terawatt-hours (TWh) for 2025 and estimated demand in 2030. The chart compares data center and non-data center demand, showing total power demand increasing over the period.

10.12.2026

The Power Demand Supercycle

This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
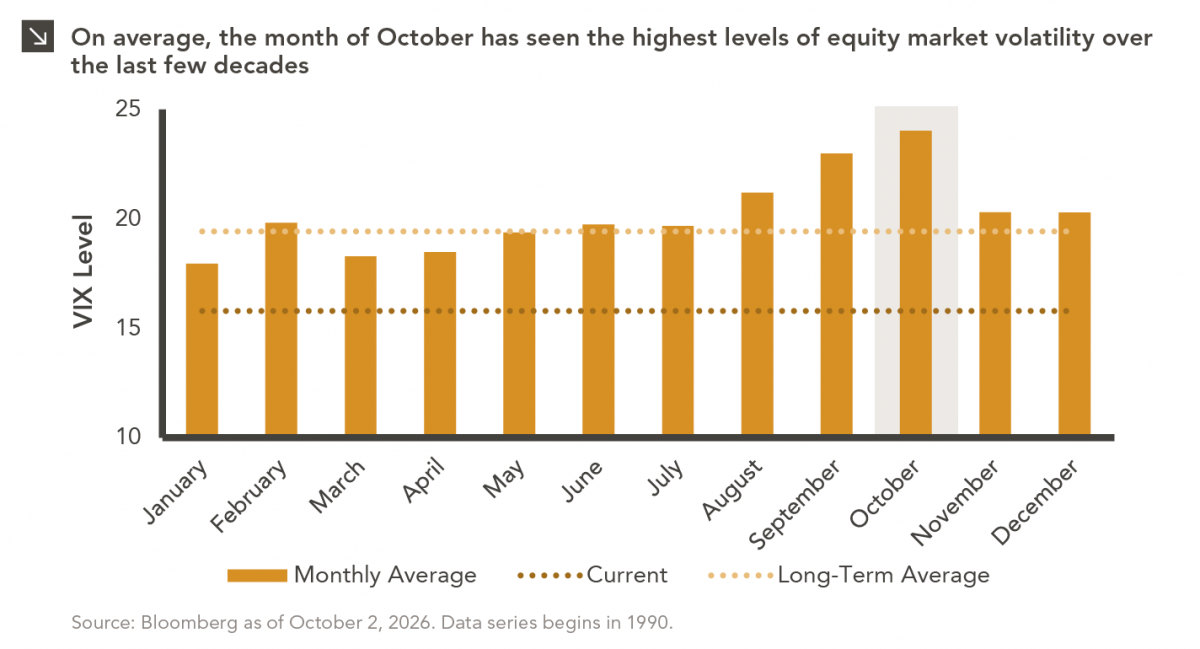
Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >

