Eric Gaylord, CFA
Partner


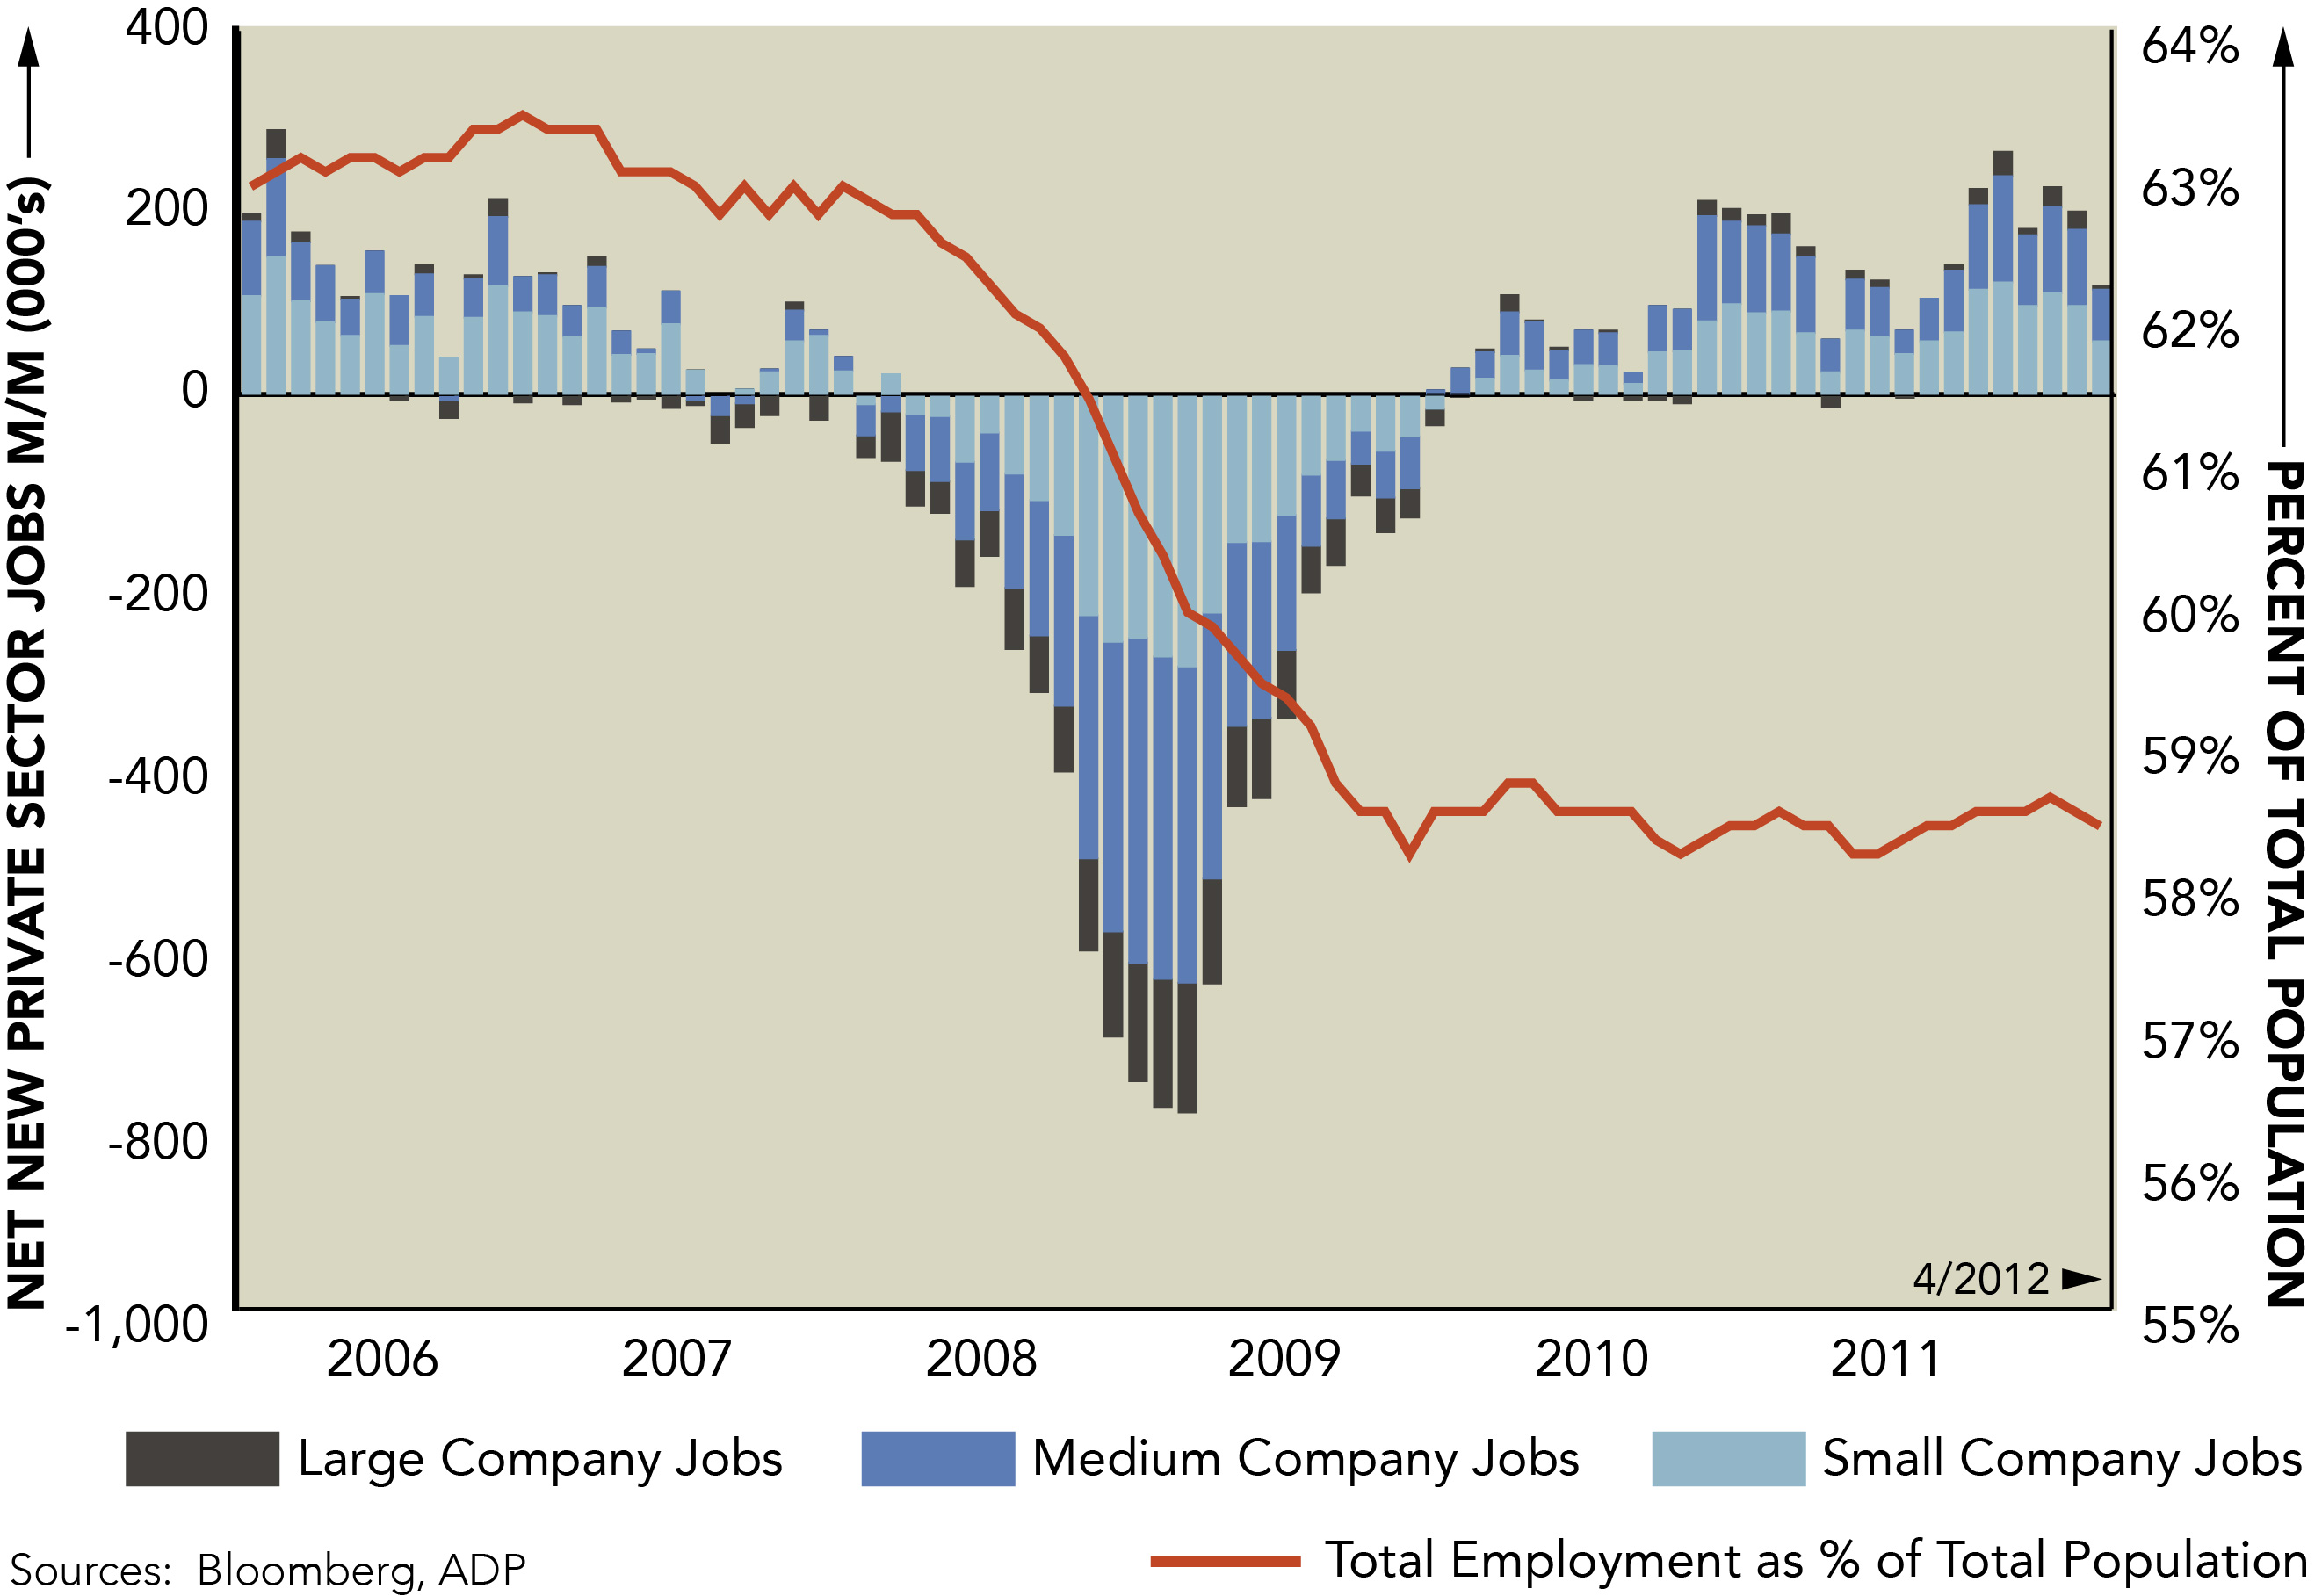
On Friday, the U.S. Department of Labor announced that 115,000 jobs were created in April and the national unemployment rate fell from 8.2% to 8.1%. Though these data points showed improvement, their release prompted an immediate equity market selloff. So what gives? In this Chart of the Week, we consider an expanded view of the labor market to explain Friday’s reaction.
At the beginning of 2006, the U.S. private sector labor market was close to full employment, and more jobs were being created every month. Comparing today’s total number of private sector jobs to those pre-recession levels, the private sector has only 2% less total jobs. The chart above illustrates why the true situation is not as healthy as the headline unemployment numbers suggest: although the private sector has been adding jobs for a little over two years now, the job growth has been almost exclusively from small and medium sized companies. A recovery in job creation by larger companies and public sector jobs which, on average, pay higher wages has yet to take hold.
Despite the fact that we have seen job creation over the last two years, the total number of Americans employed as a percentage of the population has been stagnant: the new jobs that have been created are only enough to keep pace with population growth. The unemployment rate is falling mainly because the percentage of Americans who have given up seeking work (and are therefore not included in that calculation) remains elevated.
This challenge is no more evident than with young Americans. During the 90’s, an average of 77.2% of 20-24 year olds and 52.3% of 16-19 year olds participated in the labor markets. Today, those percentages stand at 70.6% and 33.8%, respectively. As long as the labor market continues to force young people to start careers later, start saving later, and start raising families later, the outlook for full recovery and long-term economic growth remains challenged. Friday’s negative reaction to sustained slow job growth shows that small improvements are no longer enough to satisfy investors’ concerns which are becoming increasingly forward-looking.

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >