Eric Gaylord, CFA
Partner


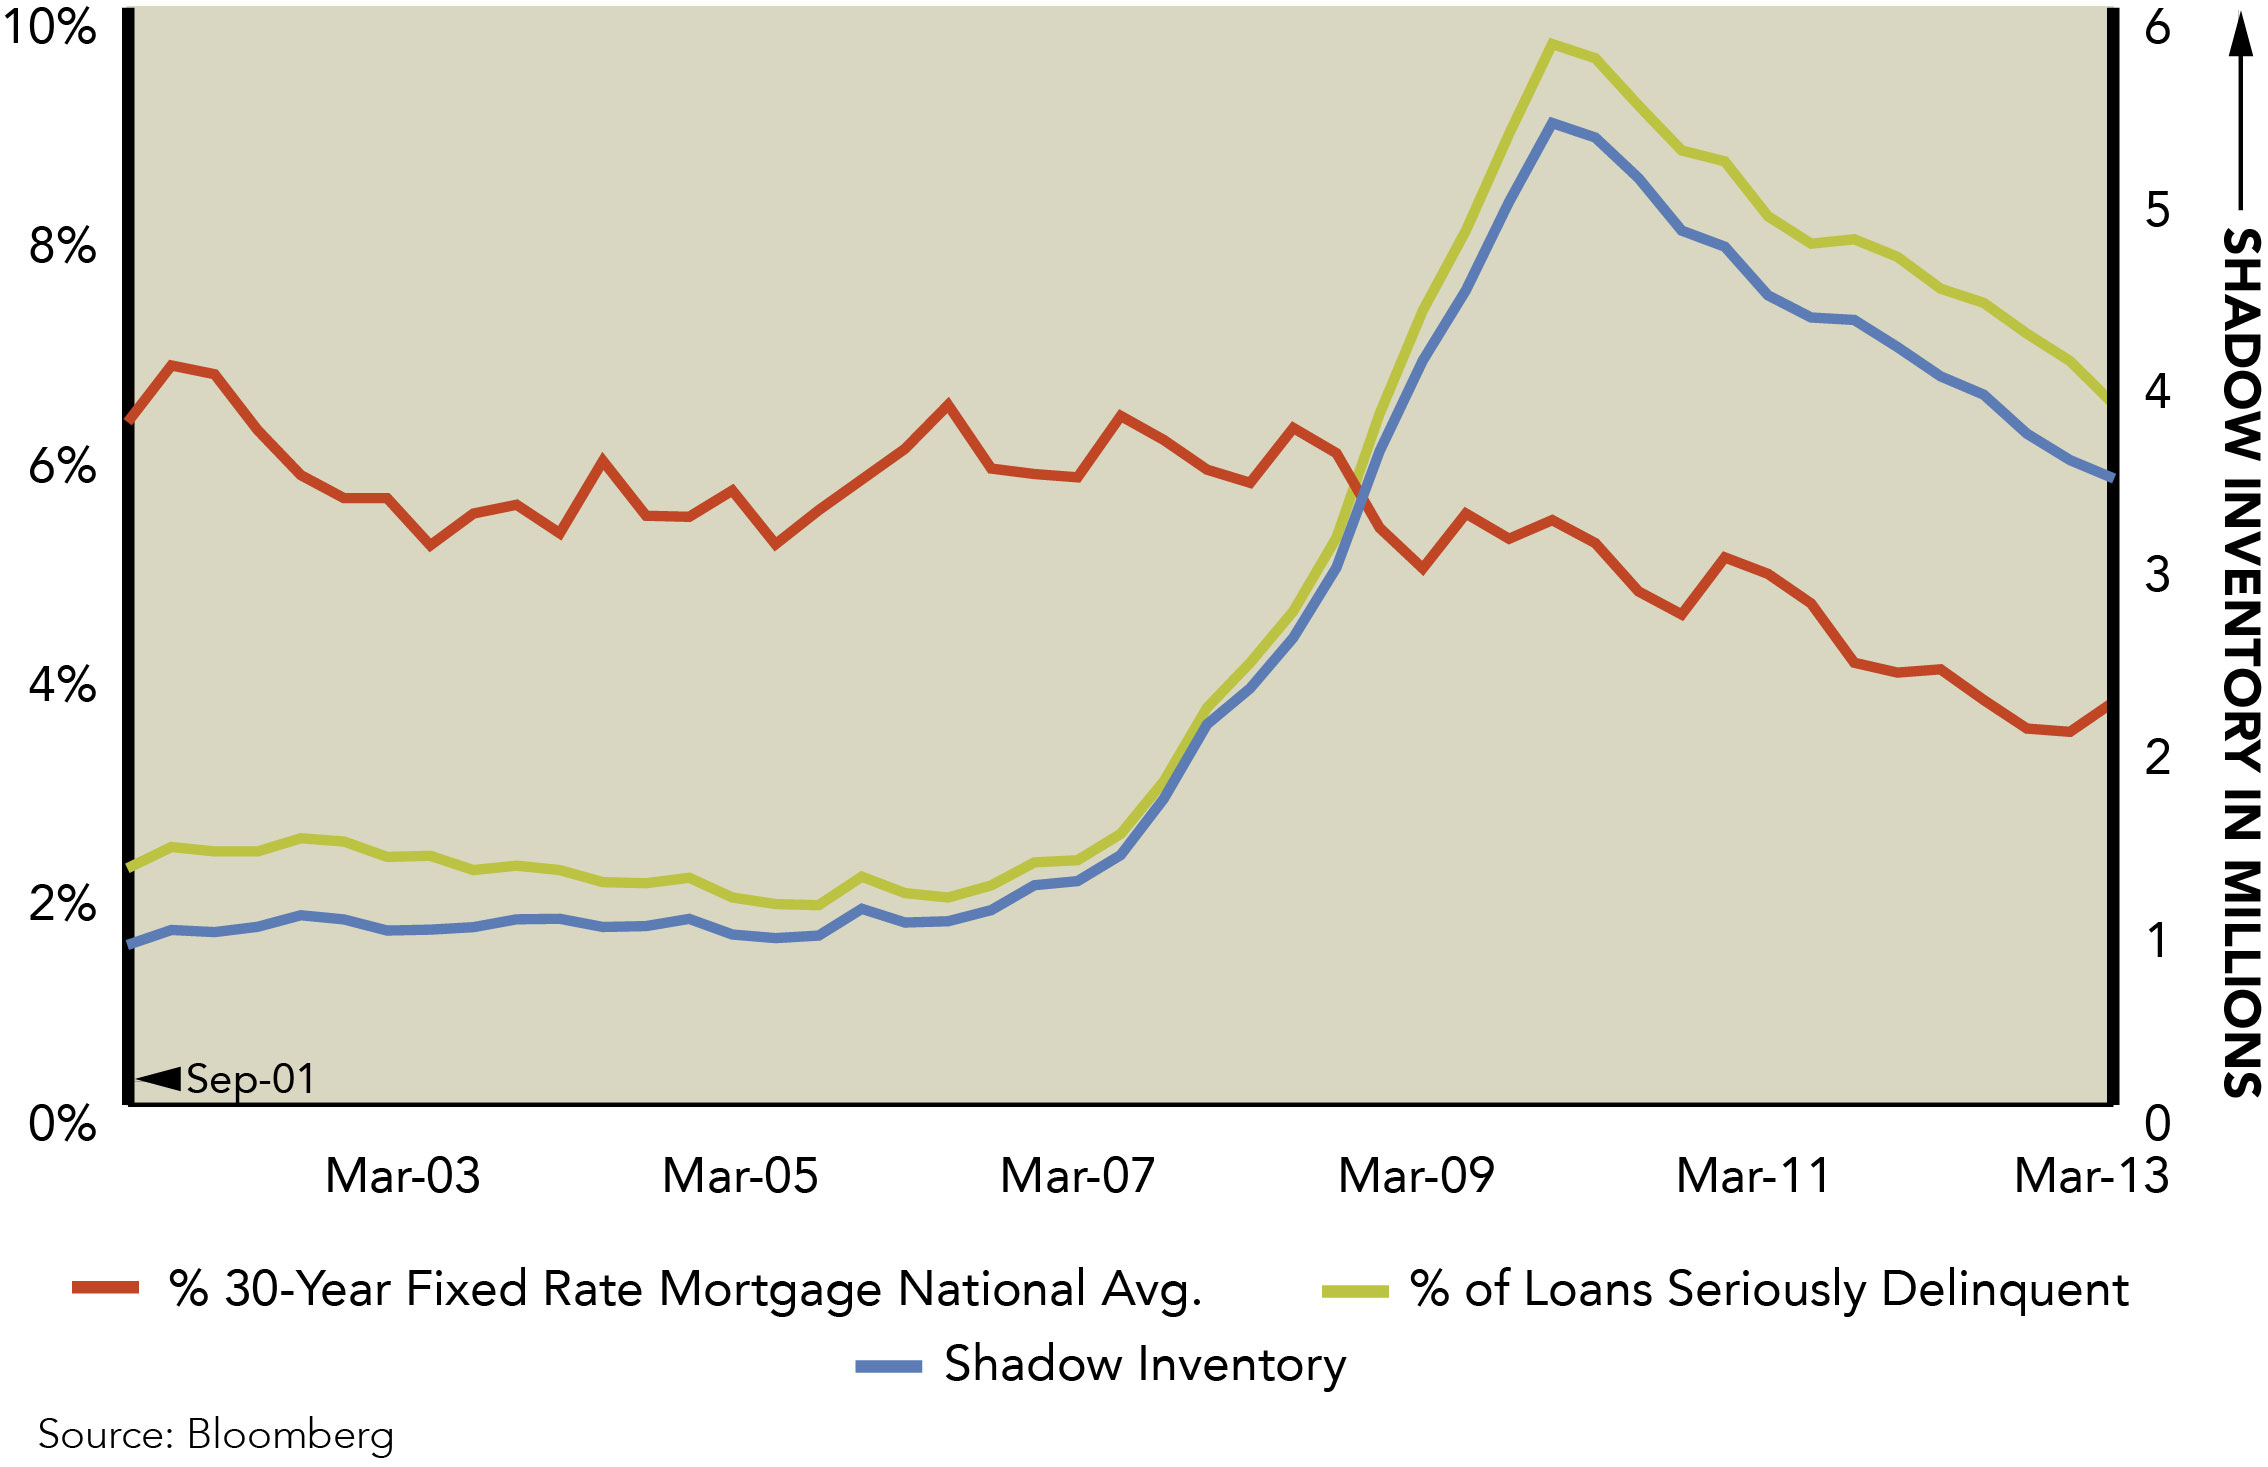
Since the end of 2008, the Federal Reserve has held the Federal Funds Rate at approximately 0% in an attempt to stimulate bank lending and revive the collapsing U.S. housing market. The aggressively accommodative monetary policy has caused borrowing rates on traditional 30-year mortgages to steadily decrease from 5.94% in September of 2008 to 3.40% at the beginning of 2013. Following the commencement of this loose monetary policy and a period of bank deleveraging, the deterioration in the housing market began to subside by the close of 2009. Accordingly, the percentage of mortgages considered seriously delinquent (i.e. 90+ days past due or in foreclosure) has steadily declined since then. Additionally, the level of “Shadow Inventory” in the housing market which includes not only homes for sale but also estimates of those that may come to market has decreased by over one third during the same period.
Collectively, these forces have driven a significant recovery in the housing market. However, the recovery may soon face some considerable headwinds as mortgage rates have recently reversed their downward trend. This reversal was partly a result of the release of the Federal Open Market Committee minutes on June 19th in which the Fed indicated the mere possibility of scaling back its stimulus program later this year. While the Fed’s policy remains unchanged and the Federal Funds Rate is expected to remain low through 2015, the perception that federal stimulus cannot continue has had a tangible impact. One week after the release of Fed minutes, the average borrowing rate on a 30-year fixed mortgage has increased from below 4.0% to around 4.6%, one of the more rapid rises in U.S. history. According to the Mortgage Bankers Association Weekly Mortgage Applications Survey, applications fell 3.0% on a seasonally-adjusted basis in the week ending June 21st and 3.3% in the week prior.
It remains to be seen if the housing market, which has been aided by decreasing borrowing rates to this point, can continue along its current trajectory of recovery with rising borrowing costs for homebuyers. A stalling housing recovery would have negative implications across the broad economy and slow nascent growth.

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >