11.16.2026
Business in the Front, Party in the Back
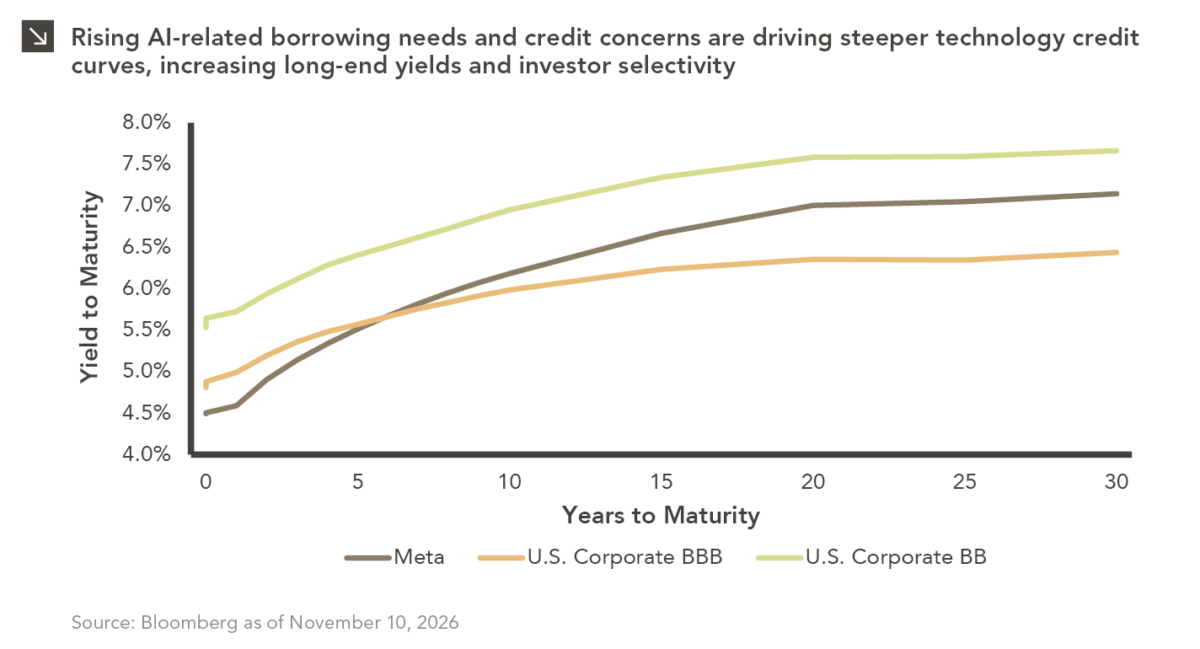
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


In the above chart, corporate profits as a percentage of employee compensation reflect the after tax profits of companies compared to the total compensation provided to American workers. As this percentage increases, corporate profits are increasing relative to employee compensation. Historically, corporate profits as a percentage of employee compensation and the unemployment rate have moved in opposite directions: in the past, both employees (through lower unemployment rates) and employers (through higher profits relative to employee compensation) have benefitted together during periods of prosperity and both have suffered together through difficult periods.
The historical pattern mentioned above holds for the period 1968 – 2008 when the unemployment rate and corporate profits as a % of employee compensation move in opposite directions: high relative profits for employers have historically coincided with low levels of unemployment. However, beginning in 2009 both the unemployment rate and corporate profits relative to employee compensation began to move sharply higher. This appears to be the first time in recent history that they have moved in tandem to such a dramatic degree and shows that corporate profits relative to employee compensation are at historical highs given the current unemployment rate. Intuitively, this makes sense, given that economic growth has been slow: companies have achieved profits through cost-cutting and efficiencies, which unfortunately comes at the expense of jobs. If previous patterns repeat themselves, either corporate profits relative to employee compensation will decline or the unemployment rate will begin to recede noticeably as companies begin to hire.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >