10.22.2026
Will Higher Rates Cramp the Markets?
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…


Commodity market investors received a ray of hope in the early months of 2014. After several years of consecutive declines, commodities, as measured by the Bloomberg Commodity Index, began the year on strong footing and posted a gain of 7.1% in the first half of the year. By the end of the third quarter, however, commodities entered negative territory, and the year-to-date return through November for the Bloomberg Commodity Index had fallen to -10.2% (Exhibit 1). In this newsletter, we examine the recent developments in the commodity markets and evaluate their prospects for the coming quarters.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.15.2026
Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…
09.08.2026
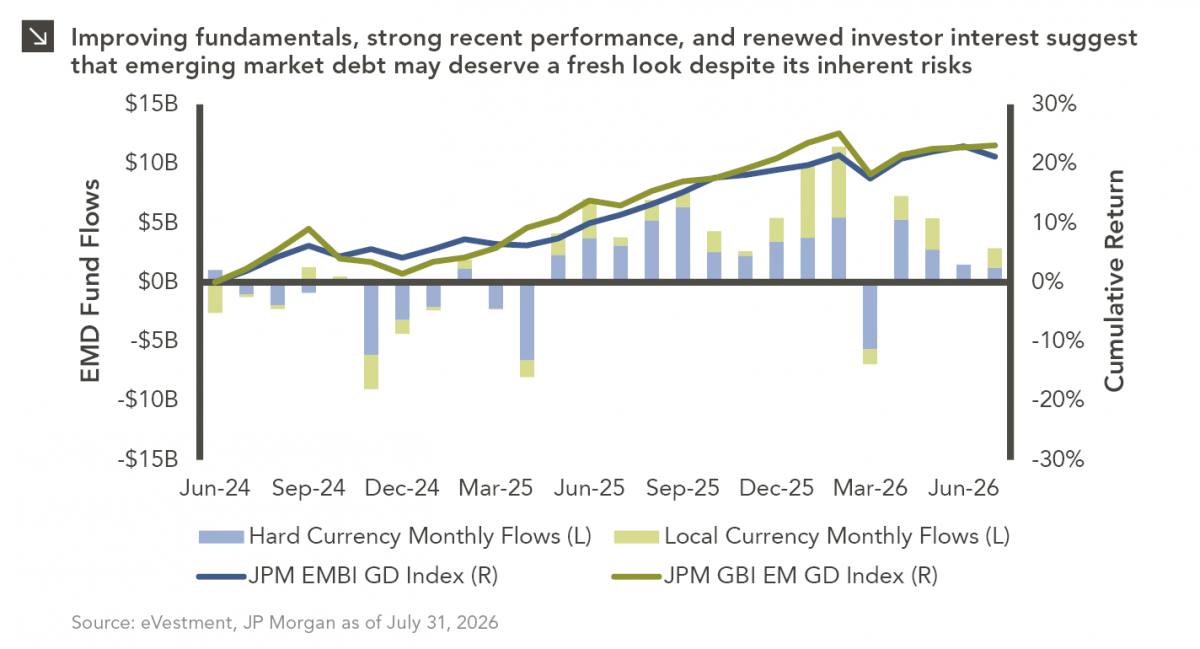
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >