Eric Gaylord, CFA
Partner


Recently, the decline in the U.S. housing market has shown some evidence of bottoming. The national average home price has crept up off of lows according to the Case-Shiller Home Price Index, and inventories of existing homes on the markets have shrunk significantly since the outset of the credit crunch. Given this new data and a Federal Reserve fiscal policy including QE3 designed to induce access to home financing, it begs the question, “Has access to home financing returned?”
The Federal Reserve conducts a quarterly survey of banks operating in the U.S. called the Senior Loan Officer Opinion Survey on Bank Lending Practices. As part of this survey, mortgage lenders report changes in demand for residential loans as well as whether standards for loan approval are becoming more or less stringent. To assess the health of the loan market, this week’s chart focuses on prime mortgage borrowing, since this category reflects loan seekers that should be considered creditworthy. In the chart, we see that banks are reporting a notable increase in demand for prime residential loans this year. Meanwhile, lending standards required by banks remain strict. The data appears to show that for Americans with control over their personal finances, the affordability of home ownership is starting to outweigh the risks. Meanwhile, banks remain cautious. The percentage of outstanding prime mortgages on their balance sheets remains elevated above the historical average. If these trends continue, investors can expect slow improvements in the residential real estate market, but given the persistent attention to high lending standards that was absent pre-crisis, these improvements should prove to be sustainable and accretive to long-term value.

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
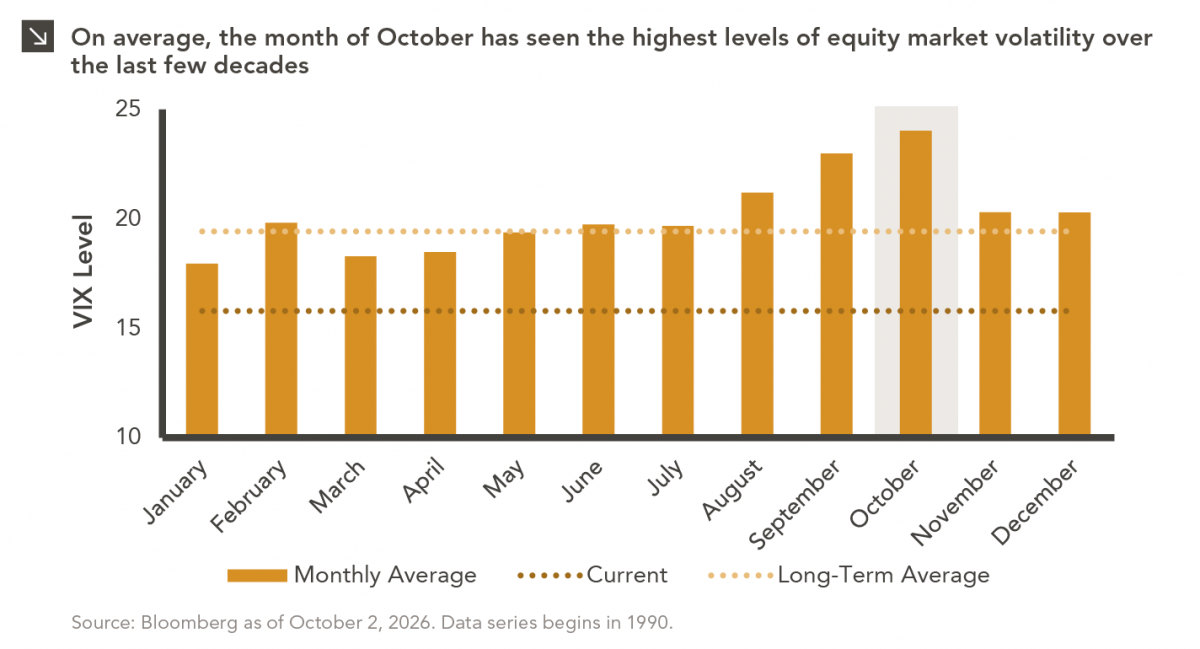
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >