10.08.2026
3Q 2026 Market Insights
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…


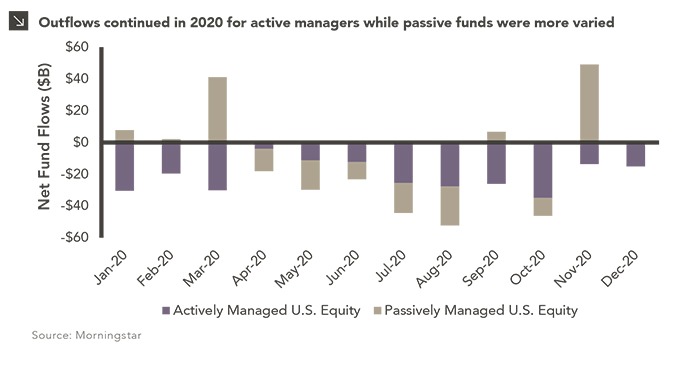
Fund flows, which measure the net movement of assets into and out of investment vehicles like mutual funds and exchange-traded funds (“ETFs”), can provide a window into investor behavior and are often an indication of investor sentiment. Strong inflows can indicate optimism within a particular asset class or investment style, while outflows may suggest pessimism on the part of investors. That said, a robust market is not always supported by investor inflows, as underlying fund flows and market index performance frequently deviate. This phenomenon was on display in 2020 and merits further evaluation.
The S&P 500 index posted a double-digit return in 2020 and closed the year at an all-time high, despite record-breaking outflows from U.S. equity funds. Nearly $241 billion flew out of domestic equity funds in 2020, a figure that is more than four times the previous calendar year record set in 2015. Perhaps unsurprisingly, these outflows centered predominately around actively managed products, a trend that has been persistent since 2014. Active funds saw net outflows in every month of 2020, while passive funds enjoyed bursts of investor interest, with extreme net inflows in both March (after the market bottomed) and November (due to positive coronavirus vaccine news). Investor preference for ETFs over mutual funds is particularly noteworthy. ETFs have risen in popularity as a lower-cost alternative to mutual fund investing and carry little-to-no investment minimum with real-time pricing. In November, passive ETFs saw a staggering net inflow of more than $54 billion, which is $12 billion more than the last monthly record set in December of 2016. This historic net inflow provided a tailwind to an already optimistic investor base and propelled indices like the Russell 2000 index, which tracks the U.S. small-cap market, to post its strongest returning month on record.
Hefty inflows for passive vehicles, like those in November, can have unfortunate implications for active investment managers. Many of these investment professionals are constructing a relatively small basket of securities with the intent to outperform a benchmark, often with less risk, over the long term. Commonly, these managers focus on quality metrics like top line growth, gross margins, earnings, and lower debt levels to drive outperformance. When a wave of inflows hits passive products, we see a “rising tide lifts all boats” phenomenon that is largely detached from underlying stock fundamentals. This can cause a short-term price dislocation and distortion of investor sentiment. Ultimately, the immediate impact of fund flows is temporary, but the continued trend away from active management may pose a greater threat to the asset management industry if portfolio managers fail to improve benchmark-relative performance.
Print PDF > Record Flows: Another Headwind for Active Management
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >