10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


Summer has arrived and with it comes the annual “Russell Rebalance,” or as FTSE Russell — the index administrator — officially calls it, the Russell Reconstitution. The last Friday in June brings a unique set of challenges for investors managing to one of Russell’s many indices. More than half of U.S. equity investment managers benchmark to a FTSE Russell Index and the Russell rebalance affects an estimated $9 trillion across these products.¹ The entire family of Russell U.S. indices is recast to reflect changes in the U.S. equity markets over the preceding year. Essentially, the rebalance resets market cap weightings and style designations, which ultimately drive shifts in the underlying sector distributions. This creates one of the highest trade-volume days of the year.
The market’s appreciation over the longest bull market in history pushed the market cap breakpoint between the asset classes to a peak in 2018 of $3.7 billion. As a result, the market cap threshold for constituents to be placed into either the large- and mid-cap focused Russell 1000 Index or the small-cap focused Russell 2000 Index has grown 150% since the Great Financial Crisis.
This past Friday, June 26th, marked the official reconstitution day. Notable movements in this year’s rebalance revolved around a few key sectors: Financials, Health Care, Industrials, and Information Technology. The Russell 1000 saw little movement in sector allocation, while the respective style indices, the Russell 1000 Growth and Value benchmarks, experienced the brunt of change. Technology now comprises a record 43% of the Russell 1000 Growth Index, a 2.3% rise, while the Industrials allocation fell to 4.6%, from 7.3%. The Russell 1000 Value Index was the recipient of those Industrials companies, rising from 9.6% to 12.4%.
From a market cap perspective, many banks within the Russell 1000 Financials sector moved to the small-cap index as investors sold economically sensitive stocks in the first quarter of the year. The Russell 2000 Index saw a 1.6% increase to the sector, bringing the total weight in Financials to 16.2%. As expected, many of these banks qualified for the Russell 2000 Value Index, which now has a nearly 29% weight to the sector. Likely the largest hurdle for active managers navigating the rebalance is the increased allocation to Biotechnology, an industry within the Health Care sector. These securities, many of which do not make money and have no established products, go against the investment philosophies of many fundamentally driven active managers. The Russell 2000 Growth Index now has a more than an 18% allocation to the industry. As managers settle into their new benchmarks, it will be pertinent to discuss these sectoral and capitalization changes in the context of future performance expectations.
Print PDF > Russell Rebalance: What Happened?
¹ FTSE Russell
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
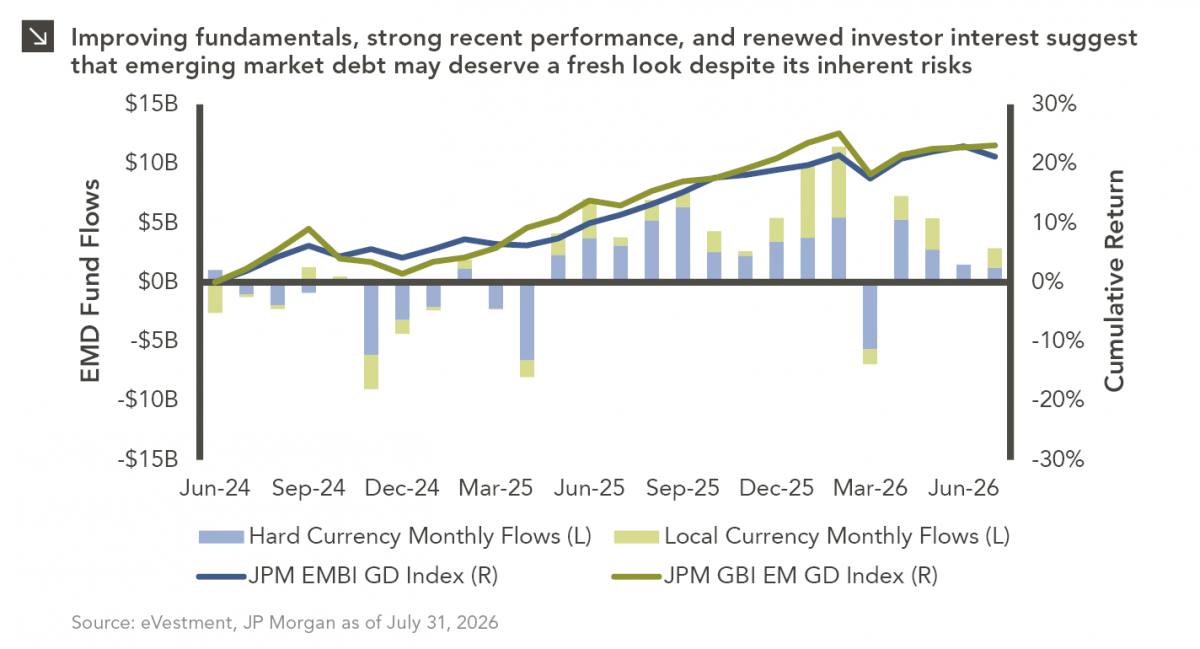
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >