11.16.2026
Business in the Front, Party in the Back
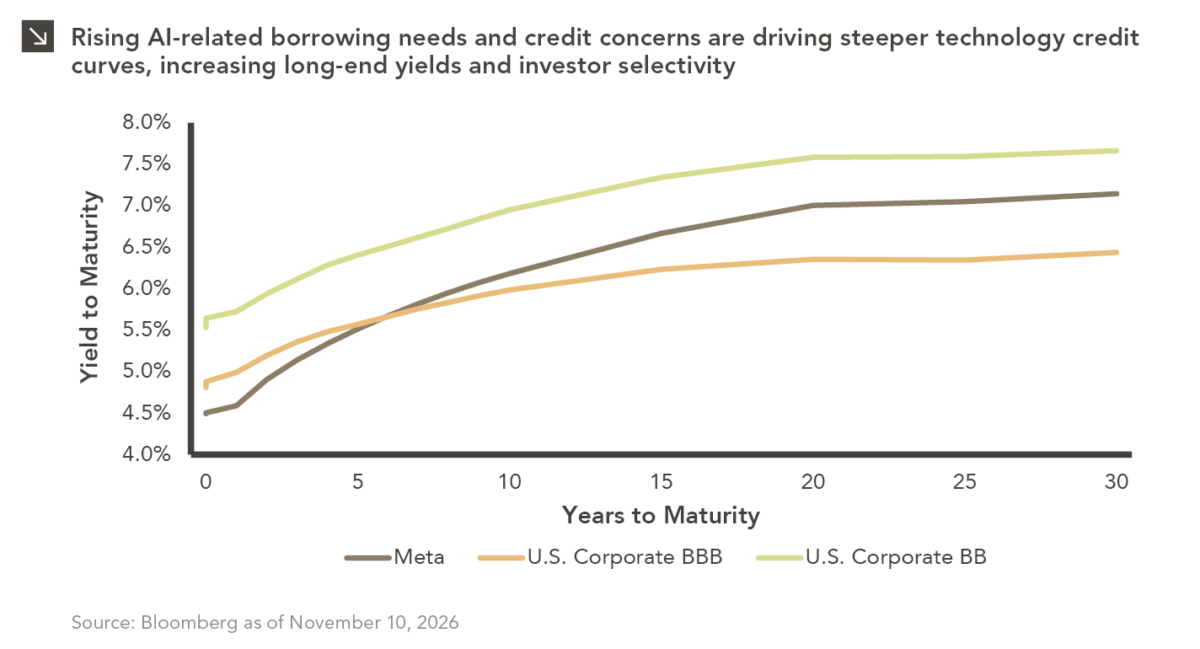
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


As the economic recovery continues, investors are rightly concerned with inflation, especially given the recent surge in M2 money supply,¹ as shown in the purple line in the left chart. M2 has soared amid unprecedented levels of monetary and fiscal stimulus infusing markets and households with cash. While an economy awash with cash may lead to concerns about runaway inflation, certain key economic recovery dynamics point to a less drastic trajectory and potentially more muted, transitory inflation.
Juxtaposing M2 with core PCE inflation,² shown as the green line in the left chart, we see that the two have not always been perfectly correlated. While an increase in the M2 rate has typically led to an increase in the core PCE rate, there are imperfections in the relationship. Inflation so far in the economic rebound has stayed low as the surge in M2 has been offset by a drastic decline in the velocity of money,³ shown as the orange line in the right chart. The velocity of money dropped off last year as money supply surged while consumer spending was down during the pandemic, though velocity has generally been in decline since 2000 amid the longer-term trends of aging demographics, greater debt, and weaker physical investment prospects relative to financial investment prospects. The increased money supply has so far not led to increased transactions, GDP per dollar spent, or inflation. The gray line in the right chart depicts M2’s annual rate of change normalized by annual GDP, showing that M2 increases from the 1990s, 2000s, and 2010s have been relatively stable as a proportion of overall GDP. In this context, while the surge over the last year is still evident, it is much less extreme.
From here, as the economy continues to reopen, consumer spending on goods and services is expected to raise demand for input materials. This, along with COVID-related supply shortages, may boost inflation temporarily. However, we expect supply chains will normalize and supply overall will adjust, reducing inflationary pressures. More importantly, in order for a pickup in inflation to be sustained over the longer term, economic participants would have to boost real asset purchases over financial asset purchases, counter to trends over the last 20 years. As the Fed eventually tapers its bond purchases and increases rates, the markets will be expected to absorb at least some of the greater money supply. M2 is ultimately expected to shrink relative to GDP as the economy rebounds, with velocity expected to correct upwards.
In summary, we generally expect a more muted and transitory rise in inflation, holding all else equal. Core PCE may rise from the 1.5% at the end of 2020 to a range of 2.0–2.5% for 2021, encompassing the Fed’s projected 2.2%, but could then revert back down close to the Fed’s long-term target of 2.0%, especially with the Fed’s eventual bond purchase tapering and rate hikes.⁴ Once the initial recovery is over and the economy trends back to normal, we could see factors like aging demographics and the trend towards services and tech over old economy sectors bring on more deflationary pressures. Post-recovery, the evidence points to more normal inflationary levels, again holding all else equal.
Print PDF > Will Skyrocketing Money Supply Boost Inflation?
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >