Mike Spychalski, CAIA
Vice President


In response to the financial crisis and the accompanying recession that began in 2007, the Fed injected massive amounts of liquidity into the U.S. economy and undertook unprecedented actions to help alleviate the stress in the financial markets. The U.S. economy has strengthened substantially over the past several quarters, and at some point the Fed will have to begin removing excess liquidity and end the special programs it created to support the economy during the crisis. With the Federal Reserve’s second round of quantitative easing (QE2) set to expire in June, there has been much speculation about what will happen once QE2 comes to an end, and when the Fed will begin tightening monetary policy.
During periods of economic recovery, the Fed has traditionally used consumer and business spending as well as the level of upward pressure on prices and wages to determine when to begin tightening monetary policy. However, given that the recession the U.S. economy is currently recovering from was largely caused by a financial crisis, the Fed has the added challenge of determining what effect financial market stress will have on the current recovery. In response to this, the Federal Reserve Bank of St. Louis developed the St. Louis Fed Financial Stress Index as a way to measure the overall “stress” in the financial markets. The St. Louis Fed Financial Stress Index combines 18 financial market variables (see table below), each of which captures some aspect of financial stress, into a single index that is compiled on a weekly basis.
This week’s Chart of the Week shows the St. Louis Fed Financial Stress Index from December 31, 1993 through April 15, 2011 (the index was created in December 2009 and was populated with data going back to December 1993). Positive values in the index indicate that financial stress is above the long-term average and negative values indicate that financial stress is below the long-term average. On April 15, 2011 (the most recent date data is available), the St. Louis Fed Financial Stress Index was -0.14, indicating that financial stress is slightly below the long-term average. This is the lowest level the index has reached since October 2007 (i.e. financial market stress is the lowest it has been since October 2007), and the first time the index has posted a negative reading for three consecutive weeks since 2007.
Components of the St. Louis Fed Financial Stress Index:
Interest Rates:
• Effective federal funds rate
• 2-year Treasury
• 10-year Treasury
• 30-year Treasury
• Baa-rated corporate
• Merrill Lynch High-Yield Corporate Master II Index
• Merrill Lynch Asset-Backed Master BBB-rated
Yield Spreads:
• Yield curve: 10-year Treasury minus 3-month Treasury
• Corporate Baa-rated bond minus 10-year Treasury
• Merrill Lynch High-Yield Corporate Master II Index minus 10-year Treasury
• 3-month London Interbank Offering Rate–Overnight Index Swap (LIBOR-OIS) spread
• 3-month Treasury-Eurodollar (TED) spread
• 3-month commercial paper minus 3-month Treasury bill
Other Indicators:
• J.P. Morgan Emerging Markets Bond Index Plus
• Chicago Board Options Exchange Market Volatility Index (VIX)
• Merrill Lynch Bond Market Volatility Index (1-month)
• 10-year nominal Treasury yield minus 10-year Treasury Inflation Protected Security yield (breakeven inflation rate)
• Vanguard Financials Exchange-Traded Fund
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
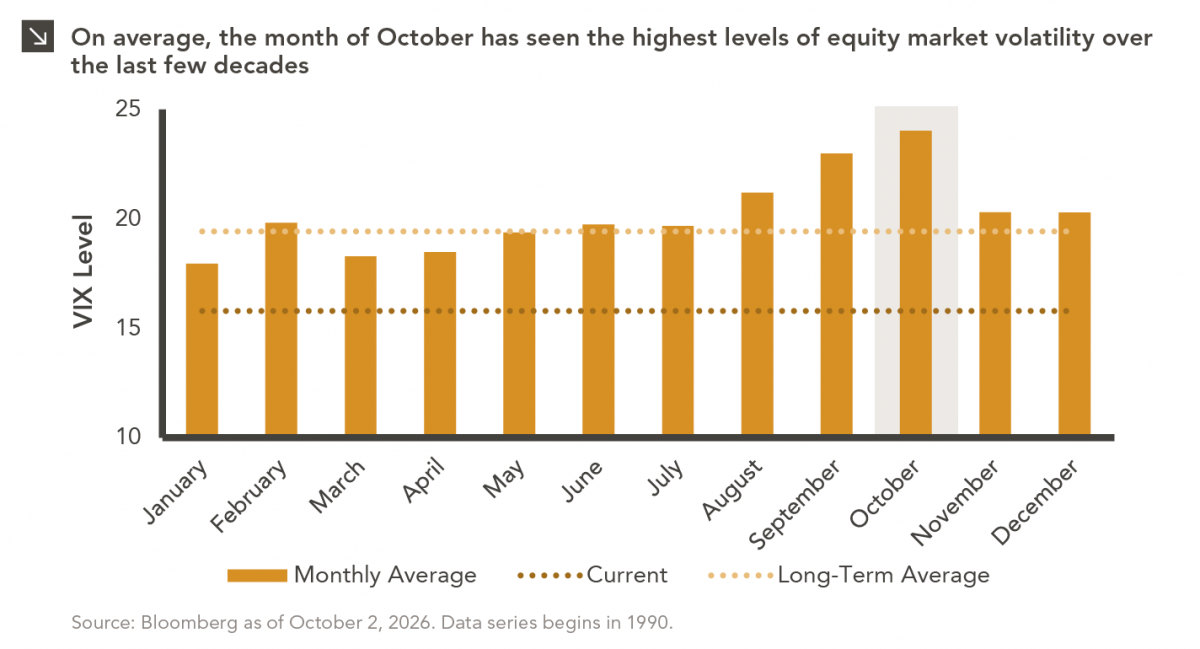
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
09.28.2026
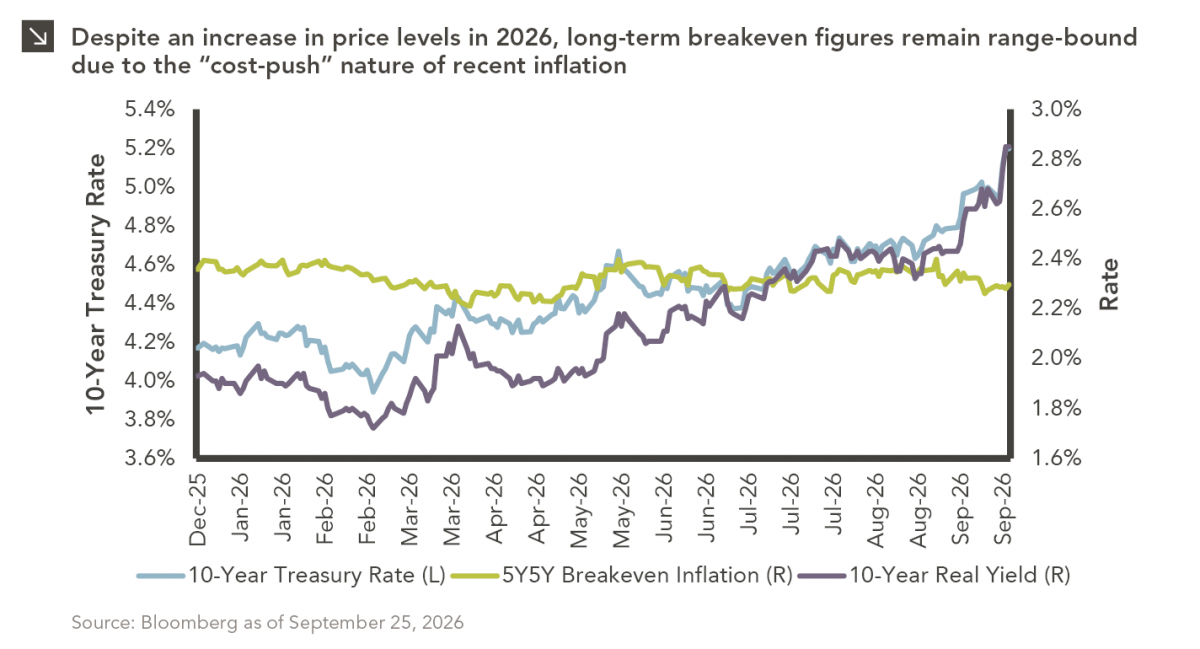
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >