10.22.2026
Will Higher Rates Cramp the Markets?
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…


Direct lending is an established asset class that provides a total return to investors typically between that of high yield bonds and mezzanine debt. It is considered private credit because the assets in a direct lending portfolio are loans originated privately between the direct lending fund manager (acting as lender) and the borrowing company. Due to the private nature of direct lending, the asset class produces attractive risk-adjusted returns supported by reduced competition, lower volatility, and favorable negotiation leverage for the direct lender. Since the financial crisis of 2008, direct lending as an asset class has featured unprecedented growth in deal volume as well as assets under management. This growth is attributed largely to post-crisis regulations that effectively forced banks, the traditional direct lenders of the past, to shed their direct lending operations. Non-bank direct lending asset managers have in turn benefitted from the significant rise in direct lending opportunities.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
09.15.2026
Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…
07.27.2026
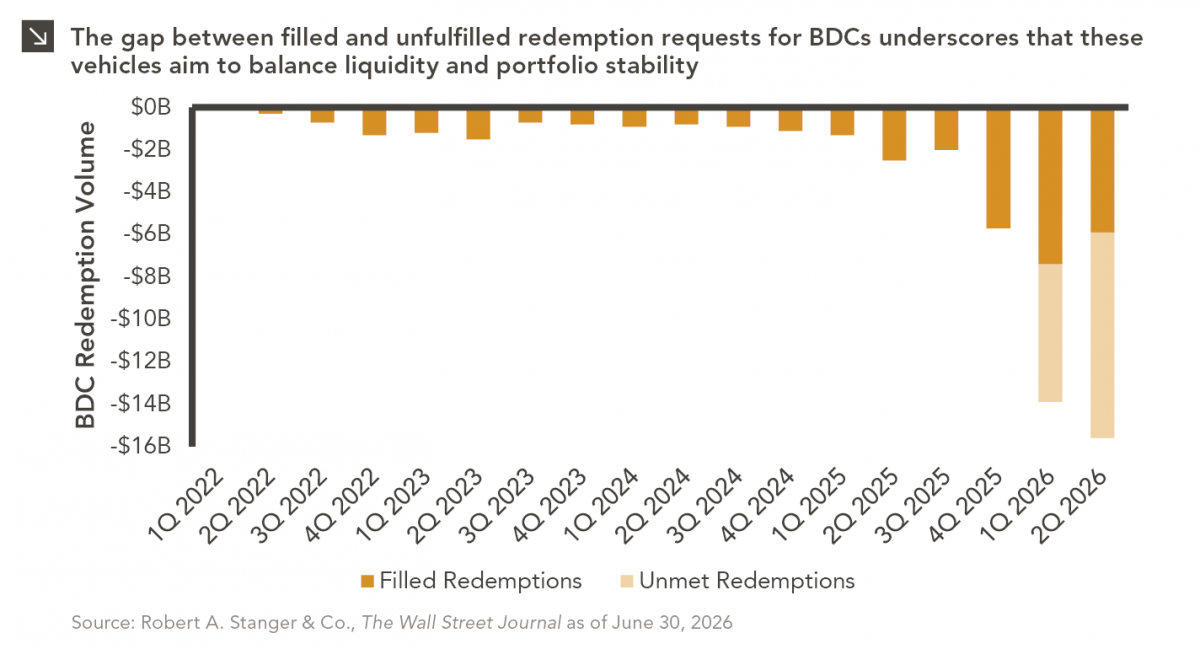
The rapid growth of non-traded business development companies (BDCs), which are investment vehicles that pool investor capital to make loans…
07.24.2026
This video is a recording of a live webinar held July 23 by Marquette’s research team analyzing the first half…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >