David Hernandez, CFA
Director of Traditional Manager Search


Late last week the European Central bank (ECB) announced an end to its quantitative easing (QE) program. Over the last three years the ECB purchased 2.4 trillion euros in bonds to help boost the region’s economy. In October of this year the monthly bond purchases will be halved to 15B euro and move to zero at the end of the year. The ECB balanced this hawkish move with a commitment to keep interest rates at current levels at least through the summer of 2019. In addition, the ECB will continue to reinvest its proceeds from current bond holdings for “an extended period of time.”
The ECB’s actions signal confidence in the economic recovery and provide a timeline for markets to adjust. Despite the end of QE, policies remain accommodative and low borrowing costs should persist into the near future. The central bank remains ready to step in should the region’s economy need further support, but has taken the first steps towards a more normal monetary policy.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
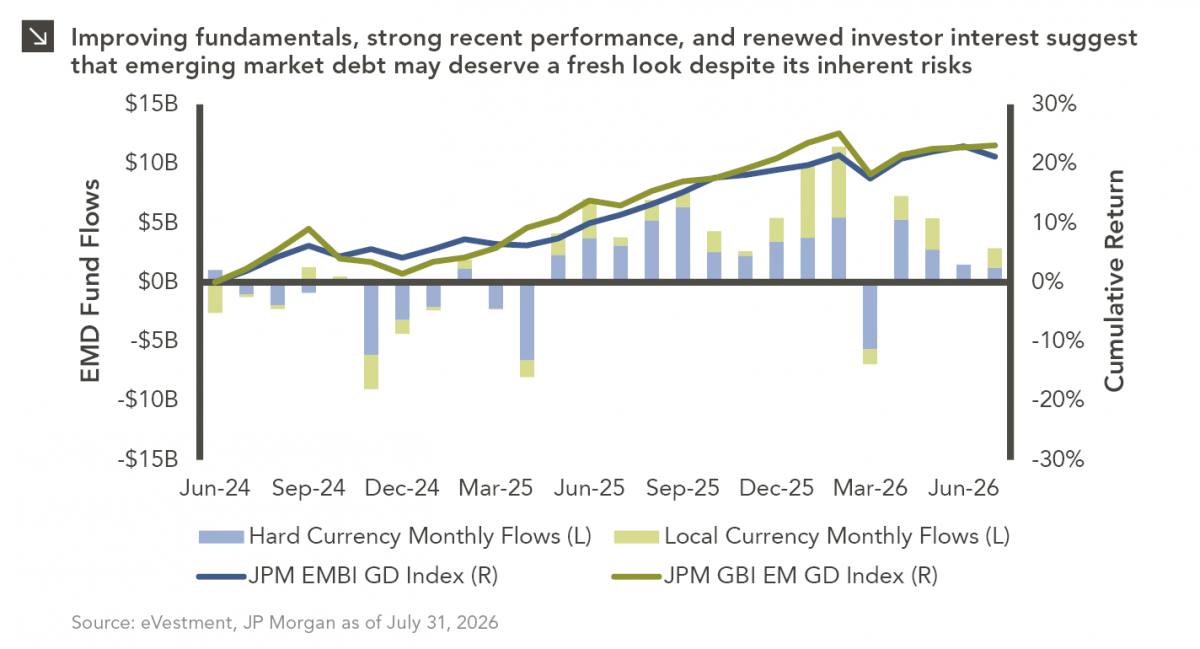
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >