3Q 2026 Market Insights

This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter of 2026 across the economy and various asset classes as well as themes we’ll be monitoring through the remainder of the year.

Our quarterly Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real assets, and private markets, with commentary by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
Frank Valle, CFA, CAIA, Associate Director of Fixed Income
James Torgerson, Senior Research Analyst
Fred Huang, Research Analyst
Catherine Hillier, Senior Research Analyst
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Hayley McCollum, Senior Research Analyst
Chloe Ariss, Associate Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

Will Higher Rates Cramp the Markets?

Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first 20 miles went, it’s really about how each runner can handle the cramps and pain of the remaining course. The outcome tends to be rather binary — it’s either the worst running experience of someone’s life (mine) or when the strongest push through and finish strong (one of our research colleagues in this year’s Chicago marathon).

This year’s market feels similar. Through September 30, most stock indices are headed for their fourth consecutive year of double-digit returns, but the massive run-up of rates in the third quarter reminds us how quickly markets can change. Nothing will be final until we cross the finish line on December 31.

2026 Halftime Market Insights

This video is a recording of a live webinar held July 23 by Marquette’s research team analyzing the first half of 2026 across the economy and various asset classes as well as themes we’ll be monitoring in the coming months.


Our quarterly Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real assets, and private markets, with commentary by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
Frank Valle, CFA, CAIA, Associate Director of Fixed Income
James Torgerson, Senior Research Analyst
Fred Huang, Research Analyst
David Hernandez, CFA, Director of Traditional Manager Search
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Amy Miller, Associate Director of Private Equity
Hayley McCollum, Senior Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

Under the Radar for the Second Half

The usual midyear version of these letters has touched on year-to-date performance as well as the most influential macroeconomic and market-specific variables to monitor over the last six months of the year. This time, however, I enlisted the help of some colleagues — Frank Valle, Evan Frazier, Fred Huang, and Weston Whalen — to identify more subtle yet materially influential factors to watch across the economy and capital markets. Make no mistake: the headline topics of Fed policy, interest rates, geopolitics, earnings, and overall diversification remain paramount to long-term investment success, but the following metrics will likely determine if the positive performance of 2026 continues for the second half of the year.

Wagging the Dog

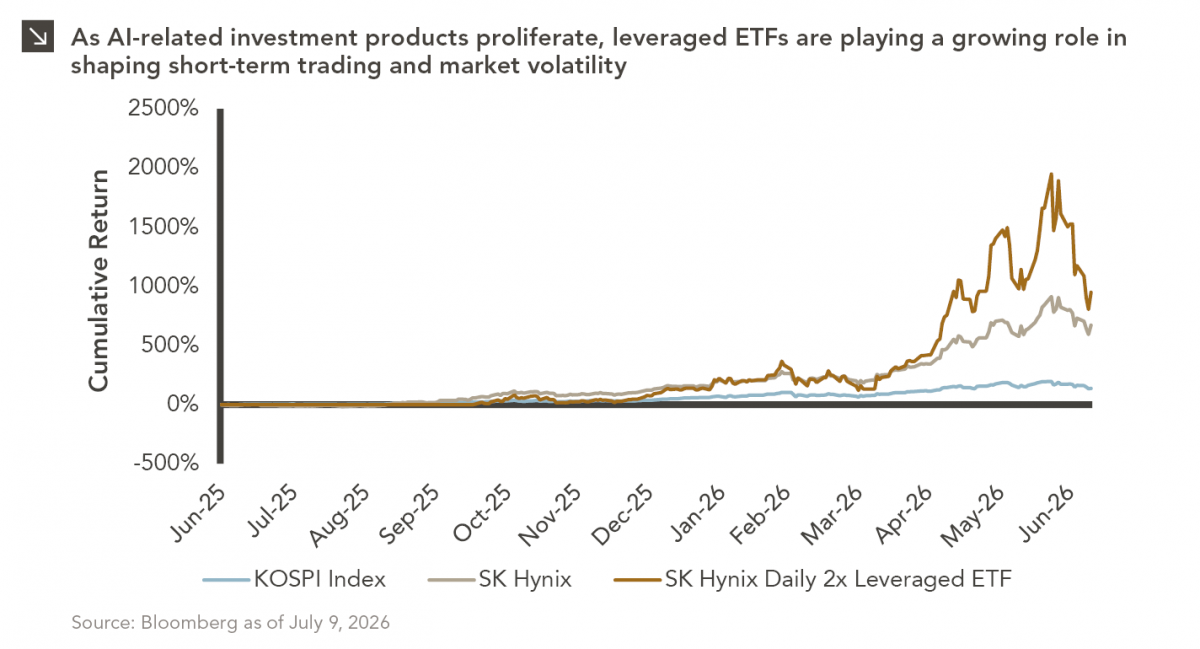
Our most recent Chart of the Week publication discussed how the AI investment opportunity has expanded beyond the large technology platforms to include critical suppliers throughout the semiconductor ecosystem and highlighted the strong performance of SK Hynix. As the AI investment theme continues to evolve, another important development has emerged: the growing influence of leveraged investment products on the trading dynamics of AI beneficiaries. Unlike traditional exchange-traded funds, single-stock leveraged ETFs seek to deliver a multiple of a stock’s daily return, allowing investors to express high-conviction views with magnified exposure. The SK Hynix Daily 2x Leveraged ETF, for example, attracted approximately $13 billion in assets after its October 2025 launch, and its success has prompted a wave of similar products. Indeed, following SK Hynix’s recent U.S. listing, issuers have begun launching leveraged ETFs tied to its U.S.-traded shares, broadening access to investors outside Asia.

The structure of leveraged ETFs creates a notable market dynamic. To maintain target leverage levels, these funds must rebalance their positions at the end of each trading day. When SK Hynix shares rise, the ETF generally needs to increase its exposure by purchasing additional derivatives or shares. Conversely, when the stock falls, the ETF typically must reduce its exposure. As assets in these funds have grown, these daily rebalancing trades have become large enough to represent a meaningful portion of SK Hynix’s trading volume. This creates the potential for feedback loops. During periods of strong momentum, ETF rebalancing can add incremental buying pressure that further supports the stock price. Conversely, market declines can trigger additional selling as the funds reduce exposure. Although company fundamentals continue to drive long-term value, these mechanical trading flows can increasingly influence short-term price movements and contribute to periods of heightened volatility.

Recent events provide a clear example of this dynamic. After an extraordinary rally fueled by optimism surrounding AI infrastructure spending and SK Hynix’s successful U.S. market debut, sentiment reversed sharply. The largest leveraged ETF tied to the company has lost roughly 45% since its debut, while SK Hynix experienced one of its steepest single-day declines in years. The rapid reversal prompted South Korean regulators to publicly question whether single-stock leveraged ETFs had been approved too quickly, highlighting growing concerns that these products can exacerbate market swings during periods of market stress. The implications of this dynamic extend beyond SK Hynix itself, as the company now represents one of the largest constituents of South Korean equity benchmarks and has become an increasingly important holding within the broader MSCI Emerging Markets Index. As a result, pronounced swings in SK Hynix shares can ripple through passive investment vehicles, affecting a much broader universe of global investors. The company’s recent U.S. listing and the expansion of leveraged products tied to both its Korean- and U.S.-listed shares further increase the number of investors participating in these technical trading flows. What began as a niche investment vehicle tied to a single stock has the potential to influence market performance across international equity portfolios.

While the long-term investment case for companies enabling AI infrastructure remains compelling, the rapid growth of leveraged products serves as a reminder that market structure can influence prices alongside fundamentals. The recent reversal in SK Hynix illustrates that leverage is inherently two-sided: the same mechanisms that can accelerate gains during periods of optimism can also amplify losses when sentiment shifts. For long-term investors, distinguishing between short-term technical factors and underlying business fundamentals will remain increasingly important as the AI investment theme continues to mature.

The Modern Gold Rush

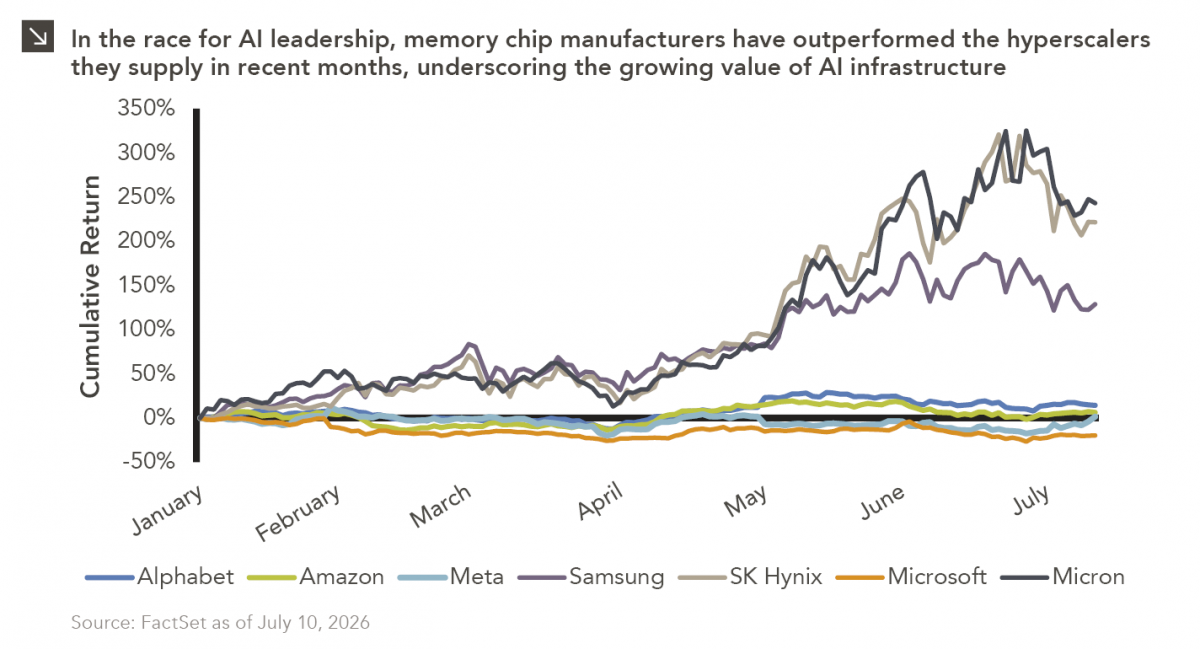
One of the enduring lessons of the California Gold Rush is that the greatest fortunes were often made not by the prospectors themselves, but by the businesses that supplied them with the essential “picks and shovels” needed in their pursuit of gold. As companies such as OpenAI, Anthropic, Alphabet, and others compete to develop increasingly sophisticated large language models, demand for the memory chips and semiconductors that power these technologies has surged, providing a significant tailwind for hardware manufacturers. The surge in demand for AI infrastructure has propelled memory chip manufacturers to record valuations. In 2026, SK Hynix, Samsung, and U.S.-based Micron each surpassed a $1 trillion market capitalization as memory has become one of the industry’s most valuable and sought-after commodities. Collectively, these three companies are now worth more than Saudi Aramco, Exxon Mobil, and Chevron (the world’s three largest oil companies), highlighting the extraordinary value investors are placing on the AI supply chain.

Microsoft, Meta, Amazon, and Alphabet are expected to spend more than $670 billion on AI-related capital expenditures in 2026, up from a combined $410 billion in 2025. This surge in investment has fueled unprecedented demand for memory chips, prompting Samsung and SK Hynix to commit more than $500 billion to expand semiconductor manufacturing capacity in South Korea. As investors continue to assess the winners and losers of the AI race, memory chip and semiconductor manufacturers have emerged as some of the market’s strongest performers.

Let’s Hear It for Latin America

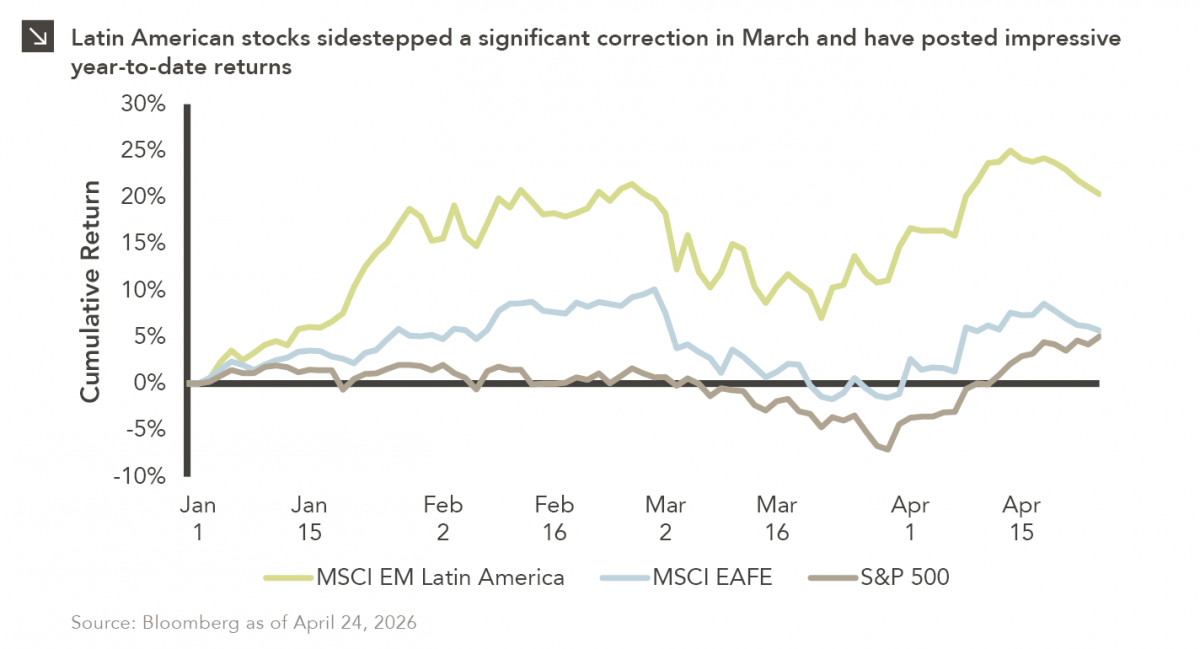
Latin American equity markets have shown remarkable strength in 2026. After a strong start to the year, the MSCI Emerging Markets Latin America Index corrected by only 4% in March amid a broad, more pronounced market pullback due in large part to the conflict in Iran. Brazil, which represents the largest economy in Latin America, was uniquely positioned to handle commodity market disruptions given its status as a net exporter of crude oil and a world leader in renewable energy utilization. Indeed, almost 90% of Brazilian electricity is generated via hydropower, wind, and solar sources, so the nation has been able to withstand recent energy shocks better than many other Western nations. The Central Bank of Brazil also cut interest rates for the first time in two years in March, though additional rate cuts that were anticipated at the start of this year are now more uncertain. Investors have also looked on Latin American financial institutions with favor in recent time, as banks across the region (e.g., Creditcorp in Peru, Itaú in Brazil, and Grupo Financiero Banorte in Mexico) are outperforming their global peers on a year-to-date basis due to attractive earnings projections. Additionally, significant foreign investment in the Brazilian economy has led to higher volumes and earnings for B3, the Brazilian stock exchange.

Global markets have stabilized in April, with the S&P 500 Index now trading near calendar year highs and developed international equities also exhibiting renewed strength. At the same time, Latin American equities have continued their upward trajectory, with the MSCI Emerging Markets Latin America Index now up more than 20% since the start of 2026. Following strong performance in 2025 and after having avoided a major drawdown in the wake of the Iran conflict, investors may want to keep a close eye on Latin American stocks as the year progresses.

We’ve Seen This Before

Diversify. Rebalance. Stay invested. Every one of these letters has concluded with that same advice in some shape or form. It’s not particularly shiny and new, but the best documented path to a successful long-term investment program. The last eight weeks are another data point in support of these practices.

In this edition:

  • Impact of U.S.–Iran conflict on oil prices, interest rates, and equity markets
  • Volatility and drawdowns in the market cycle
  • Equity market rotation
  • Magnificent 7 detraction and increased market breadth
  • Slowdown in non-U.S. equities

1Q 2026 Market Insights Webinar

This video is a recording of a live webinar held April 16 by Marquette’s research team analyzing the first quarter across the economy and various asset classes as well as themes we’ll be monitoring in the coming months.

Our quarterly Market Insights series examines the primary asset classes we cover for clients including the U.S. economy, fixed income, U.S. and non-U.S. equities, hedge funds, real assets, and private markets, with commentary by our research analysts and directors.

Featuring:
Greg Leonberger, FSA, EA, MAAA, FCA, Partner, Director of Research
James Torgerson, Senior Research Analyst
Fred Huang, Research Analyst
David Hernandez, CFA, Director of Traditional Manager Search
Evan Frazier, CFA, CAIA, Senior Research Analyst
Dennis Yu, Research Analyst
Hayley McCollum, Senior Research Analyst

Sign up for research alerts to be invited to future webinars and notified when we publish new videos.

If you have any questions, please send our team an email.


The Passive Performance Podium

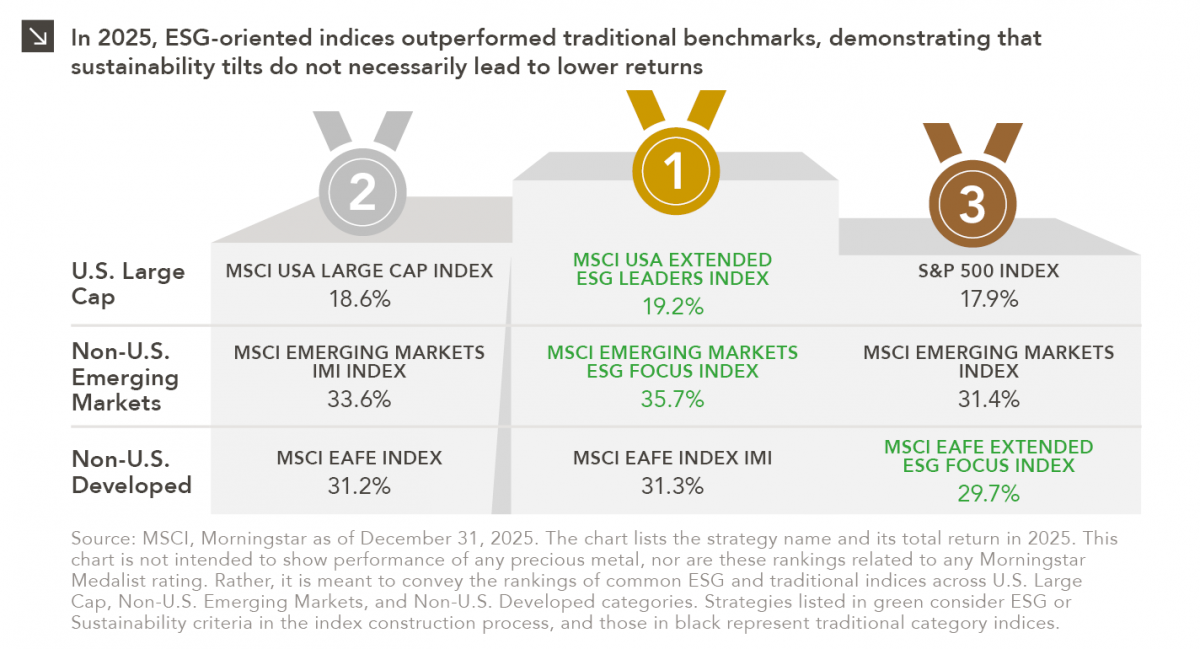
Performance is a key attribute of any investment strategy with a values-based or sustainability focus. As such, analyzing the 2025 returns of traditional indices and those of their ESG-integrated equivalents seemed like a worthwhile endeavor, especially given the 25th Winter Olympic Games currently taking place in Italy. The purpose of this assessment was to evaluate how ESG-oriented indices performed against traditional indices in the U.S. Large Cap, Emerging Markets, and Developed International equity spaces to determine the “passive performance medalists” of 2025.

Before evaluating returns, it is important to outline how ESG-oriented indices are constructed, given that a degree of tracking error is always to be expected from these benchmarks. According to MSCI, each ESG index seeks a risk and return profile that is similar to the broad market index it is designed to track, while also targeting improved sustainability characteristics and avoiding controversies. Of course, nuances exist across different flavors of sustainability indices. For instance, the “ESG Leaders” approach differs slightly from that of “ESG Focused” indices in that it overweights higher scoring ESG names against sector peers and utilizes additional screens. Key examples include the following:

  • MSCI USA Extended ESG Leaders Index: Applies exclusions related to alcohol, Arctic oil and gas production, controversial weapons, nuclear power, palm oil, thermal coal, tobacco, fossil fuel extraction, and gambling.
  • MSCI Emerging Markets ESG Focus Index and MSCI EAFE Extended ESG Focus Index: Both apply exclusions related to civilian firearms, controversial weapons, tobacco, thermal coal, and oil sands.

The time has now come to award the medals. In the U.S. Large Cap space, the ESG Leaders approach landed atop the podium in 2025, as overweight positions in best-in-class Communication Services companies proved fruitful last year. Within Emerging Markets, the MSCI EM ESG Focus Index took home gold with the highest absolute outperformance thanks to positive stock selection effects in sectors including Information Technology, Health Care, and Energy (where being underweight also contributed to excess returns). Finally, a photo finish determined the gold/silver outcome for traditional indices in the EAFE space. The MSCI EAFE ESG Index trailed the two traditional benchmarks due to its weapons-related exclusions and lower exposure to companies in construction and mining spaces, which hampered relative returns given Europe’s increased focus on defense and infrastructure.

The fact that passive ESG indices fared well outside of the EAFE space in 2025 serves as a reminder that funds that track these benchmarks may make sense for the following types of market participants:

  • Mission-aligned investors who do not see their values fully reflected in certain segments of their portfolios
  • Purpose-driven or traditional investors who may consider passive vehicles as placeholders before identifying a viable active manager

It is important to note that understanding the nuances of different ESG-focused products is crucial, as many involve exclusions, additional risk management levers, and screens that will create absolute and relative performance variability. Still, if a lesson can be learned from 2025, it is that investors can enjoy strong performance from passive equity strategies while also tilting toward securities with more sustainable characteristics.