Jessica Noviskis, CFA
Portfolio Strategist, OCIO Services


Silicon Valley Bank (SVB), the 16th largest bank in the U.S. by assets as of year-end 2022, was shuttered by regulators last Friday, March 10. This is the country’s first material bank insolvency since the Global Financial Crisis (GFC) and the second-largest bank failure in U.S. history, behind only the government takeover of Washington Mutual in 2008. The bank’s collapse came as a surprise to markets — both S&P and Moody’s had an investment-grade rating (BBB) on the borrower and equity markets showed few signs of foreseen stress. Additionally, earlier last week, smaller Silvergate Bank announced it would voluntarily liquidate, and over the weekend, Signature Bank was seized by New York regulators, marking the U.S.’s third-largest bank failure.
Over the weekend, the Treasury, Federal Reserve, and FDIC came together to shore up confidence in the U.S. banking system. Via joint statement, the consortium announced that all depositors at SVB and Signature Bank would be made whole, easing concerns that deposits over the FDIC-insured limit of $250,000 would be at risk, and introduced a new $25 billion bank funding program, the Bank Term Funding Program, to make additional funds available to banks at more favorable terms, to hopefully prevent a repeat of the events that led to SVB’s demise. Both initiatives will come at no cost to the U.S. taxpayer. While the measures should help corporations, consumers, and markets breathe a sigh of relief — there was fear over the weekend that SVB clients would not be able to pay employees, which could lead to a downward economic spiral — concerns about possible systemic risk and broader implications for the economy remain.
This newsletter summarizes the impact of SVB’s failure on the markets, including potential for contagion, SVB exposure across asset classes, and expectations regarding Fed tightening from here.
Read > Update on Silicon Valley Bank and the Impact on Markets

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
09.15.2026
Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…

08.24.2026
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…
08.10.2026
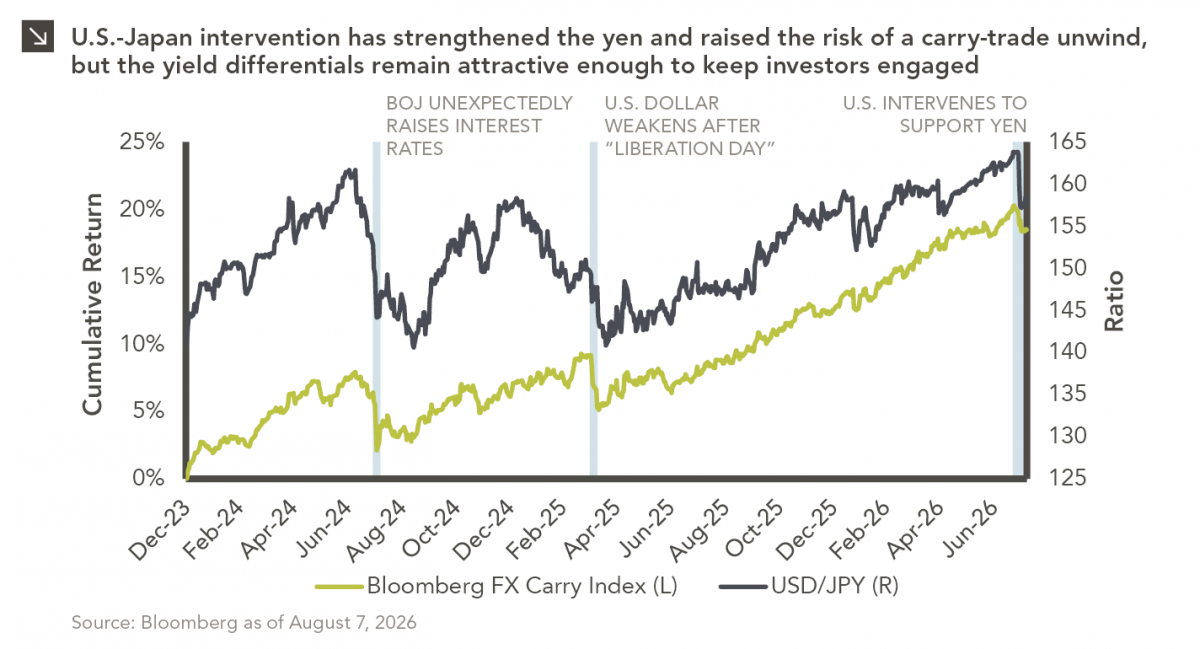
After reaching nearly ¥164 per dollar, its weakest level in roughly four decades, the yen had become a source of…
08.03.2026
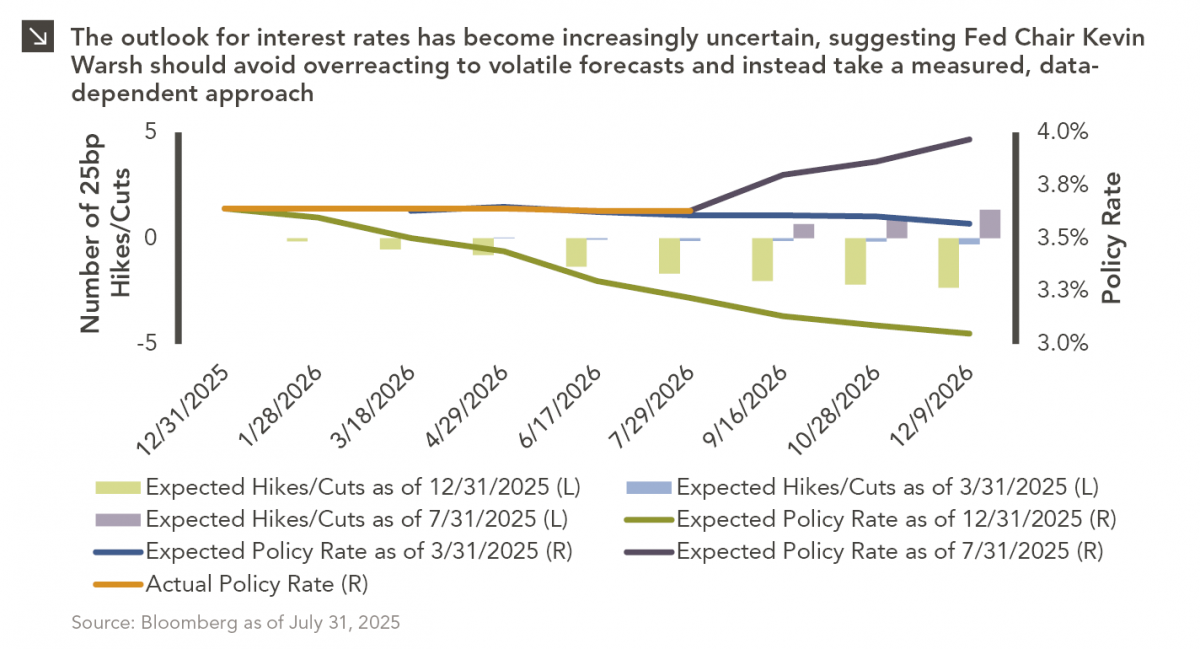
In the cinematic masterpiece Rocky IV, Rocky gets dazed by his opponent, Captain Ivan Drago, and complains that he sees…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >