11.09.2026
C’s Get Degrees (of Pain)
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…


Driven by the stock market’s upward trajectory during the past six months, the yields of various asset classes illustrate a return to riskier asset classes and a change in the landscape for income-driven investors. Our Chart of the Week shows the disparity between this week’s yields and those of roughly six months ago, when we last examined this topic.
Investors’ return to riskier asset classes has caused an increase in Treasury yields and a decrease in the yields of more volatile bonds and equities. Since September 26, 2011, when we last produced a chart of the week on this topic, the S&P 500 Index has increased by 21.5%, from 1,162.95 to 1,412.52 as of March 27, 2012. European debt woes that threatened the global economy throughout the 3rd and 4th quarters of last year have subsided and yields have diminished as investors add risk back to their portfolios. The 10-Year Treasury’s yield has increased by 22 basis points over the past six months and is now greater than that of the S&P 500, which declined by 24 basis points. For the week of March 12, 2012, global bond funds enjoyed their 11th straight week of inflows and emerging market bond funds had their 2nd best week of the trailing year, manifested by the 1.18% drop in the yield of the BarCap Emerging Market Bond Index over the past six months. High yield bond funds have also seen noteworthy inflows over the past six months, which has driven yields down 1.94%. U.S. Treasuries are again becoming more attractive for the income-driven investor as the yields of more volatile asset classes have decreased, and the income-focused portfolio will likely return to a more traditional structure as the yields of various markets move closer to historic averages.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

10.12.2026
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
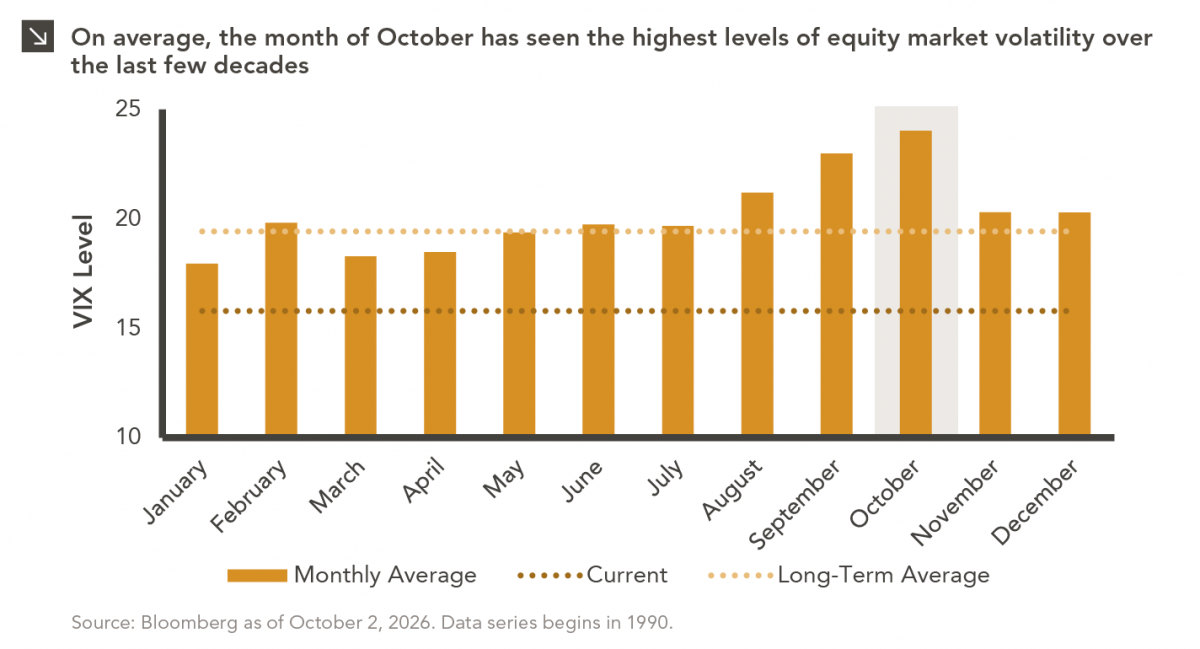
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >