10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


The price of oil as measured by the May WTI futures contract (gray line) fell to negative territory for the first time in history on Monday, plunging to -$40 before expiring at a positive price on Tuesday. Decreased demand for oil due to travel restrictions has caused an abnormal situation where in the short term, oil producers were willing to pay buyers to take their oil as they had limited storage space. Since physical delivery occurs on these future contracts, some were at risk of having purchased oil with no place to put it. However, when we look at the further dated June WTI futures contract (green line), the price change has not been as dramatic and remains in positive territory.
Demand has significantly weakened for oil, and supply cuts have been coming too late which are driving the price down. Price volatility is expected to be extremely high in the near term as gasoline and jet fuel are simply sitting in storage. Oil prices need to be around roughly $20 a barrel for United States domiciled companies to break even. Smaller energy companies with high debt burdens whose revenues are tied to the price of oil are unable to sustain low prices for long and are at risk of bankruptcy and laying off employees, further adding to the economic stress caused by the coronavirus. Such negative outcomes will also weigh on the equity and bond markets — as seen earlier this week — so the price of oil is clearly another economic variable that will be closely monitored through this pandemic.
Print PDF > Why Did the Price of Oil Turn Negative?
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
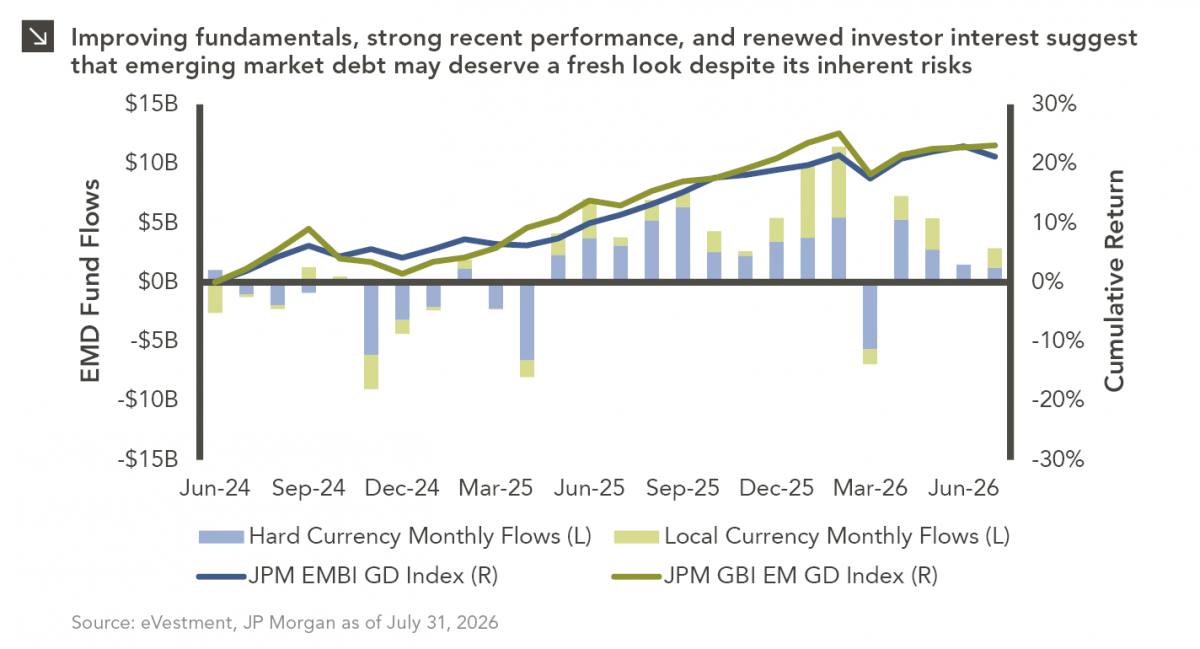
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >