10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


The impressive strength of U.S. equities in recent years has drawn significant investment from both domestic and international investors, but a closer look reveals a shift in how investors are attaining exposure to the asset class. The chart above illustrates the cumulative net asset flows for various U.S. equity investment vehicles since 2009 and indicates that a growing number of investors are embracing passive strategies. To that point, more than $2.5 trillion has flowed from active to passive management in the last 15 years, with most of the dollars having been directed toward ETFs.
There are many factors that have contributed to this trend. First, mobile brokerage platforms and improvements in technology have made investing more convenient and cheaper for retail investors, with thousands of low-cost products now available that track major stock indices like the S&P 500. Second, many institutional investors have reallocated portions of their U.S. equity portfolios to passive strategies to save on fees, while seeking higher returns via active management in other asset classes like private equity. Additionally, many active U.S. equity strategies have struggled to keep pace with the broad market. Specifically, just 15% of active U.S. large-cap managers have outperformed the S&P 500 over the last decade due a small handful of companies (i.e., the “Magnificent Seven”) having been responsible for an outsized portion of U.S. equity market returns in recent years. This trend also aligns with what is often referred to as the “paradox of skill,” which states that as the absolute level of skill in a space increases, the relative skill among the players in that space often decreases. While this framework has been applied to everything from the NBA to chess, it may also be partly responsible for the decrease in the return premiums earned via active management in the U.S. equity market. If true, this trend poses interesting questions related to whether similar alpha compression will occur in fast-growing spaces like private markets.
Print PDFThe opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.21.2026
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
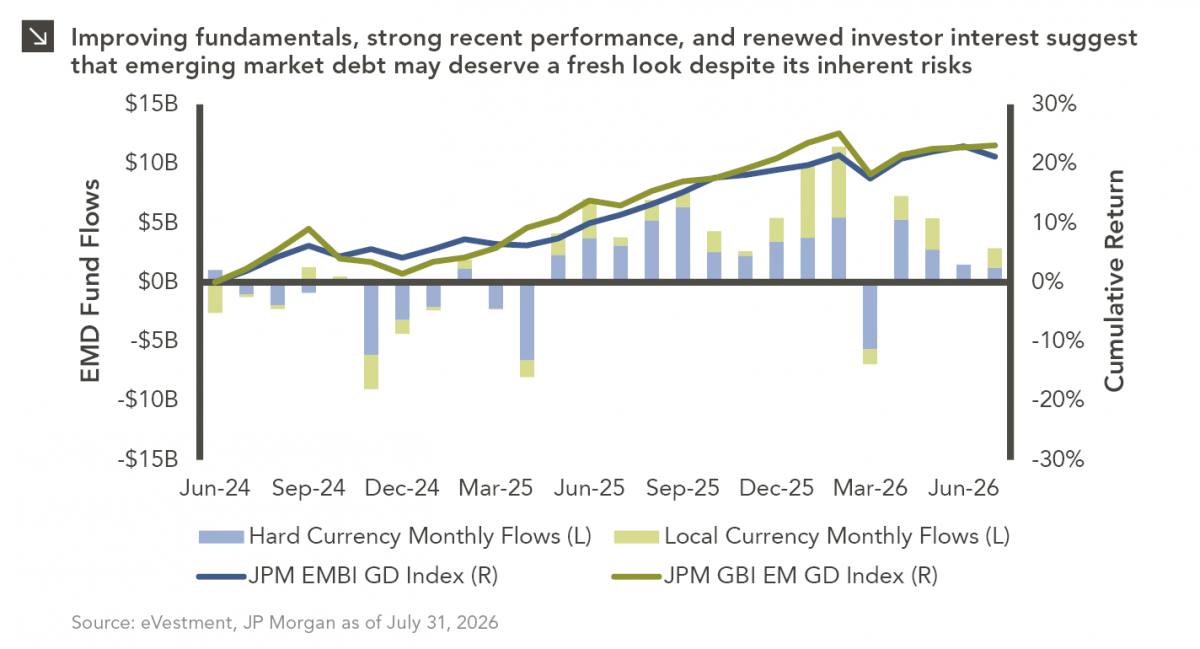
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >