10.26.2026
Smaller Deals, Larger Appeal
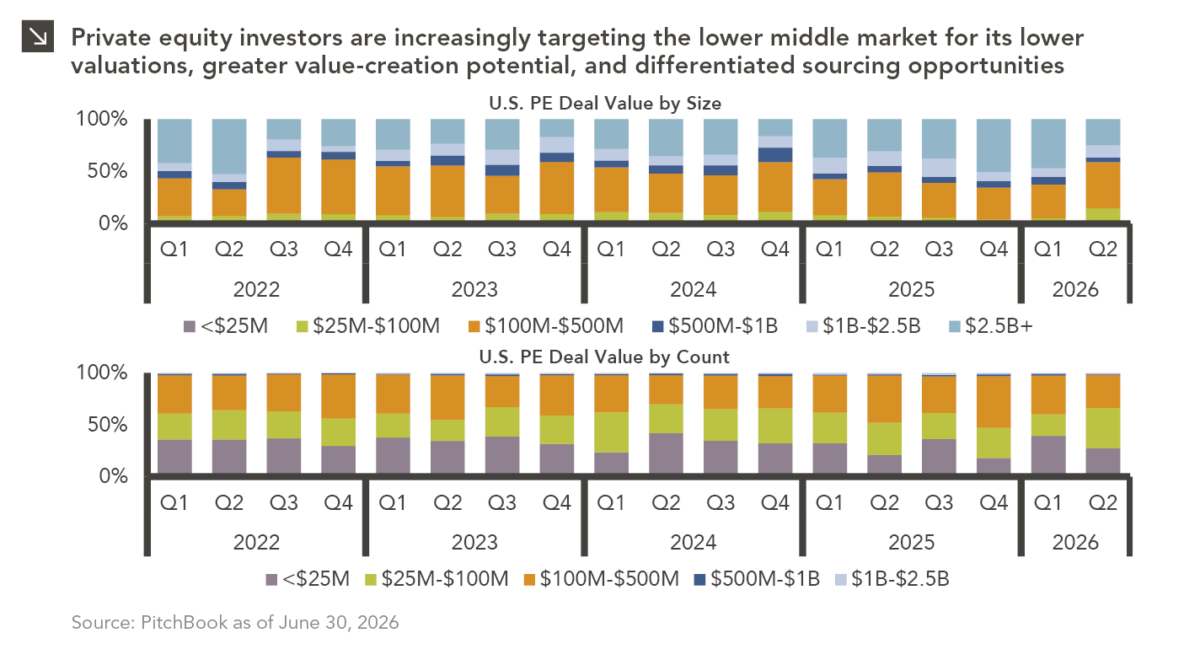
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…


The Taylor rule, proposed by John Taylor, is a formula for determining the target Fed Funds rate. In the Taylor Rule, the Fed Funds rate baseline is set to the target nominal rate (target real rate plus target inflation), and then adjusted based on economic conditions. The rule states that the Fed Funds rate should be raised when inflation is higher than target inflation (“Inflation Gap”), and lowered when economic output is lower than potential output (“Output Gap”). The equation for the Taylor rule is shown below:
Target Fed Funds = Inflation + Target Real Rate + a1(Inflation Gap) + a2(Output Gap)
Though the rule itself is relatively simple, there are many different interpretations of how to implement it. There are of course multiple measures of inflation, and multiple measures of the output gap. In the chart, we use the Core Personal Consumption Expenditures (PCE) deflator, one of the measures favored by the Fed, as our measure of inflation. To measure the output gap, we use the CBO real potential GDP series, a trend line estimate, less actual real GDP.
The other two important components of the Taylor rule are the “weights” placed on the inflation gap and the output gap. These are the terms a1 and a2 in the formula. The larger the weighting, the more the prescribed Fed Funds rate moves in response to changes in inflation and output. In his original formulation, Taylor proposed weights of 0.5 for both inflation and output.
While the Fed does not explicitly follow the Taylor rule, it has proved to be a reasonable approximation of Fed policy. However, the Fed has indicated that it places more “weight” on the output gap than Taylor originally suggested. The graph shows the “original” Taylor rule, as well as an “alternate” Taylor rule with more weight placed on the output gap. In normal times these rules track fairly closely, however, when the output gap is large the alternate rule prescribes a much lower Fed Funds rate than the original rule. This formulation currently suggests a negative Fed Funds rate. Because the Fed Funds rate is up against a zero lower bound, this explains why the Fed engaged in unconventional monetary policy actions such as quantitative easing.
The graph projects out the target Fed Funds rate based on both formulations of the Taylor rule. Real GDP is projected using Bloomberg consensus estimates, and a constant 1.5% inflation rate based on the PCE deflator is assumed. This inflation rate is lower than the 2% target, but higher than the recent reading of 0.9%. Given these assumptions, the alternate rule does not imply an increased Fed Funds rate until 3Q 2012. This is roughly in line with the futures market, which suggests a greater than 50% chance of an increased Fed Funds rate in 2Q 2012.
Finally, this chart is not intended as a forecast, but merely as a template for understanding Fed policy. Any large surprise either to the upside or downside for GDP could impact Fed policy. The more important indicator to watch may be measures of core inflation. The Fed has stated that it favors measures of core inflation (inflation less food and energy), and has described the current commodities led uptick in CPI as “transient.” As long as measures of core inflation remain subdued there is little pressure on the Fed to raise rates until the output gap narrows. Economists should debate why the Fed makes its decisions; investors should only be concerned with how the Fed makes its decisions to determine likely outcomes.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…
10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
10.19.2026
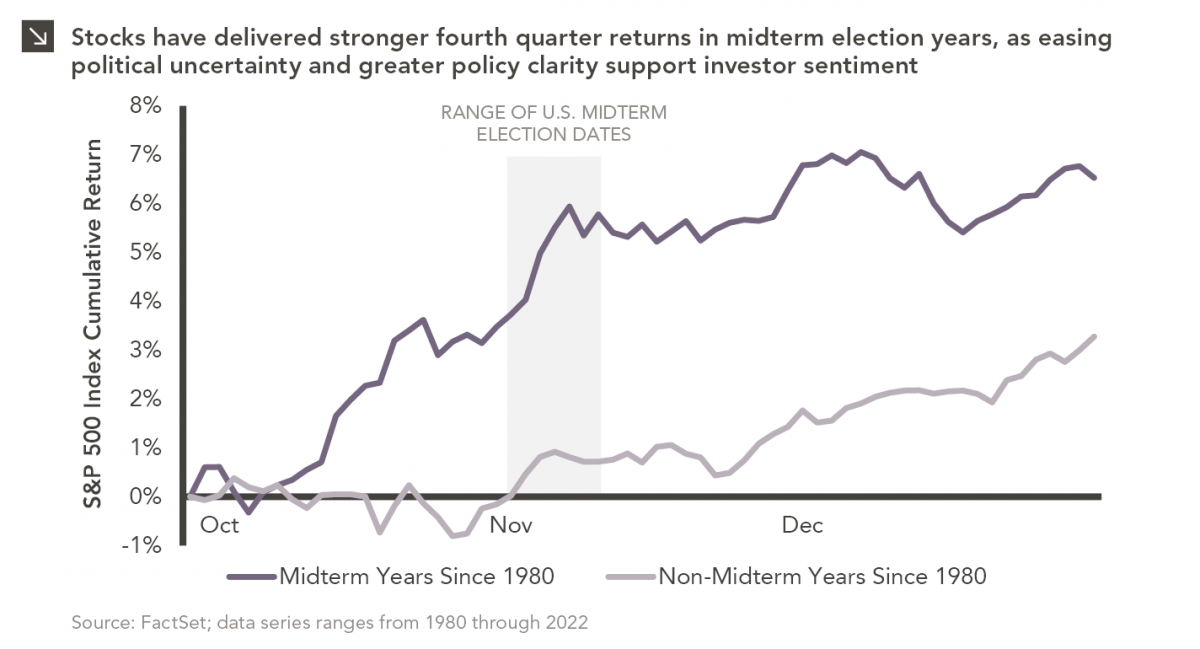
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.12.2026
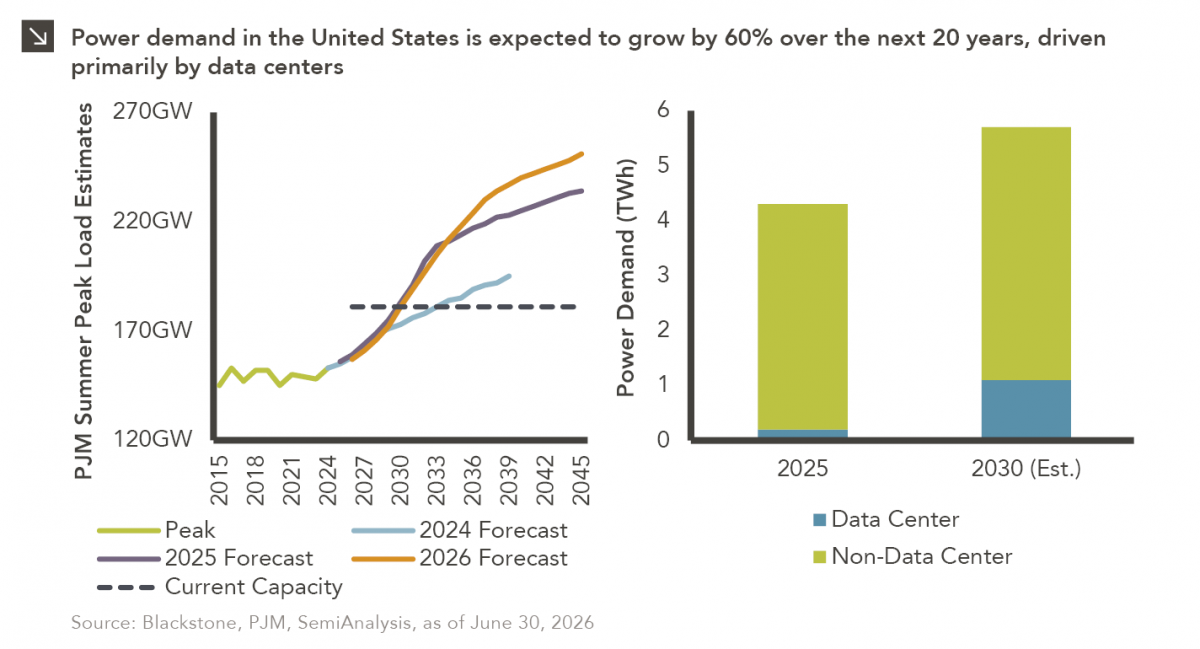
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
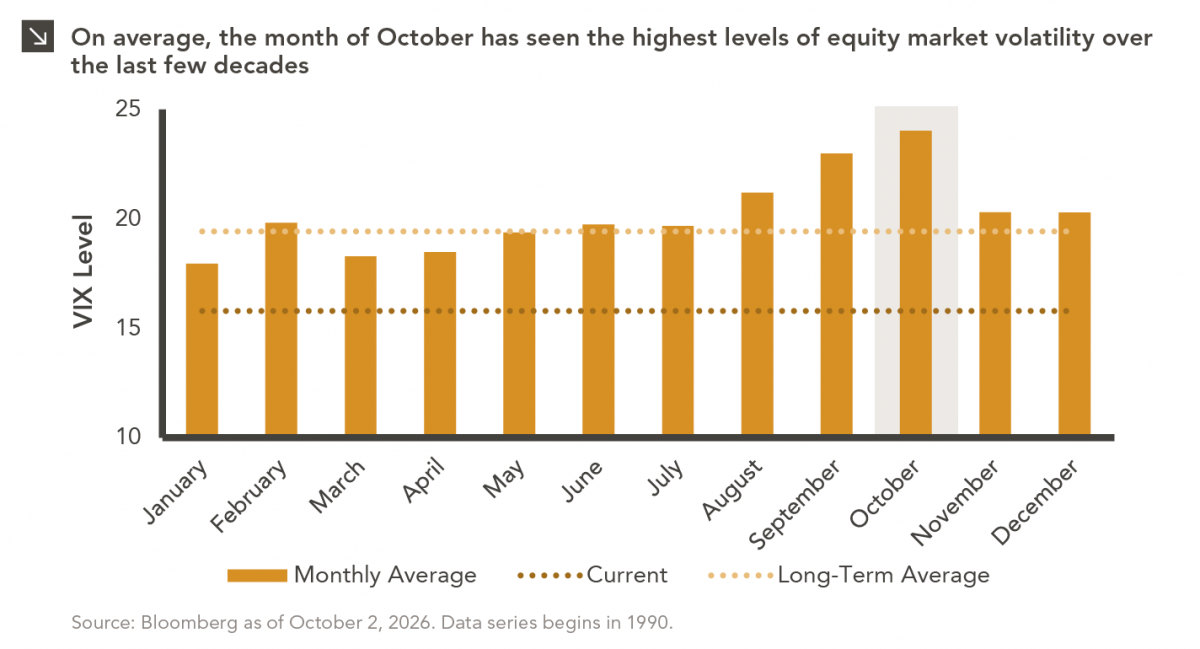
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >