10.08.2026
3Q 2026 Market Insights Webinar
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…


Equity hedge strategies were the best performing hedge fund strategy in 2017, as alpha was generated on both the long and short side. This chart shows that net alpha bounced back nicely from 2016, as the 2017 environment was much better for active management. Alpha was generated on the short side during the first half of the year, but trailed off as the bull market continued to move higher.
Another factor that helped equity hedge strategies was the decline in correlations during the year. An environment with lower correlations among stocks is positive for active managers, particularly those who maintain both long and short positions.
For alpha generation to continue in 2018, correlations between stocks will need to stay low, with meaningful sector dispersion. Coupled with the continued effort to remove global monetary stimulus, we would expect managers to benefit from these conditions.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…
10.05.2026
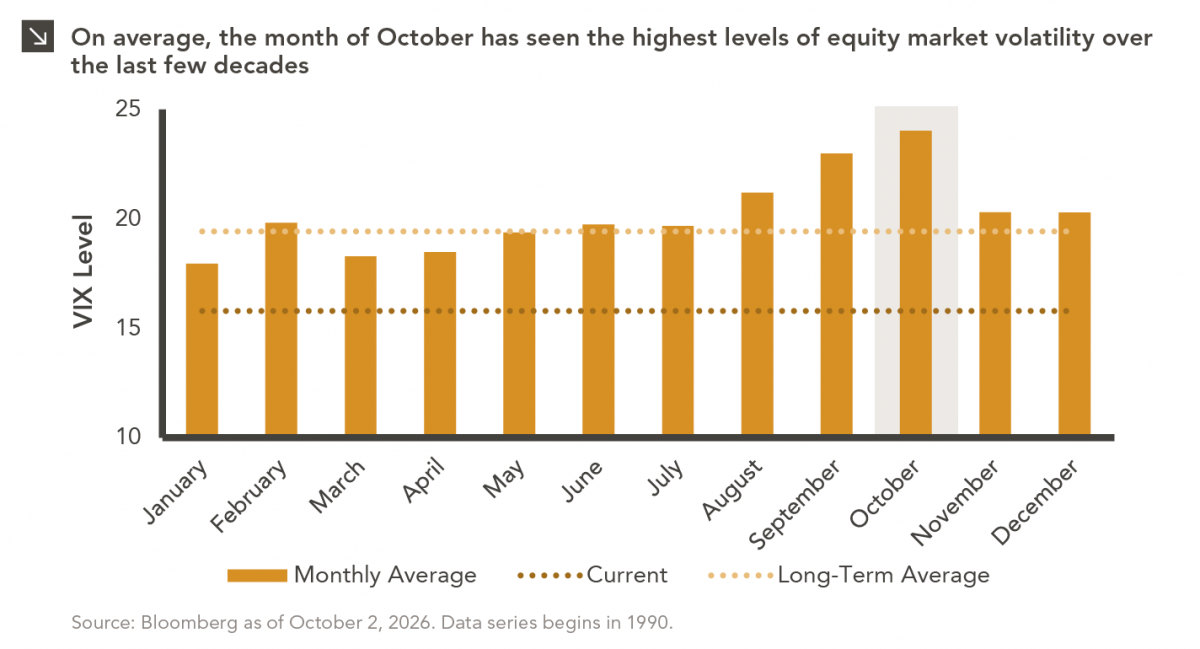
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
09.28.2026
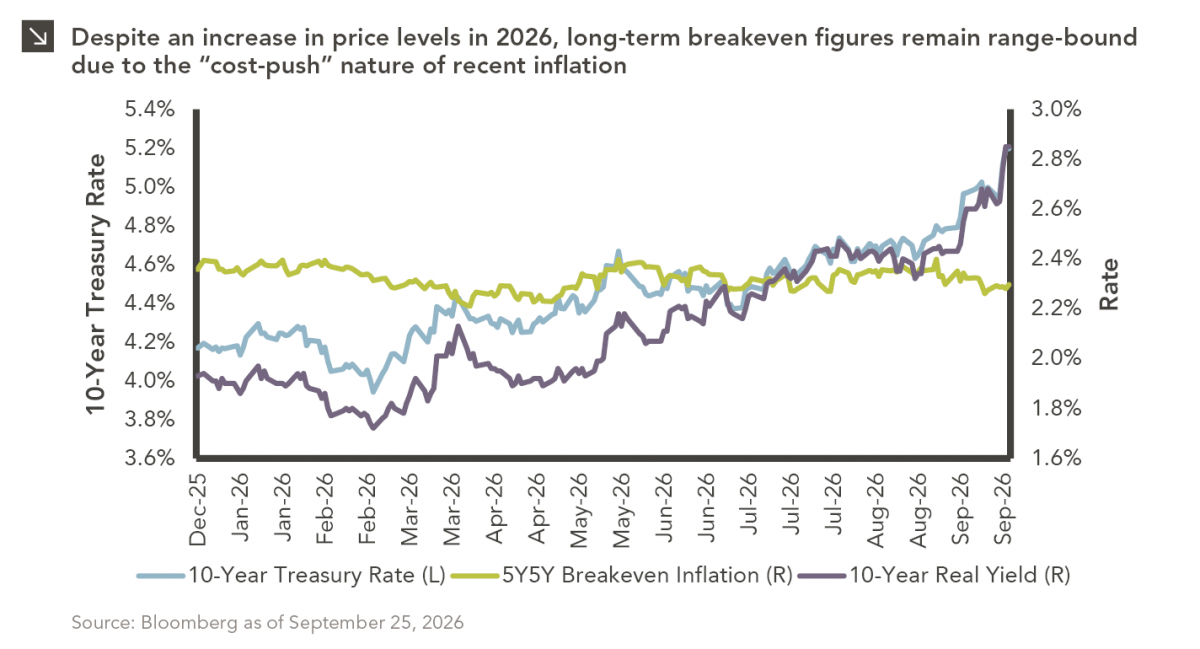
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.21.2026
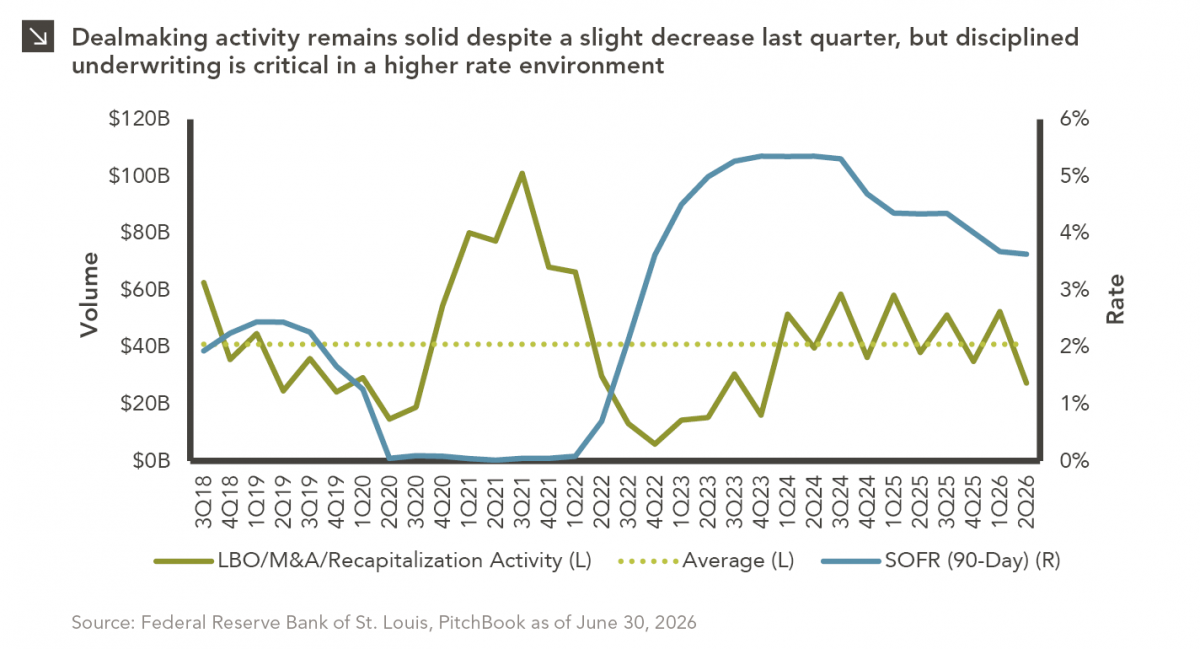
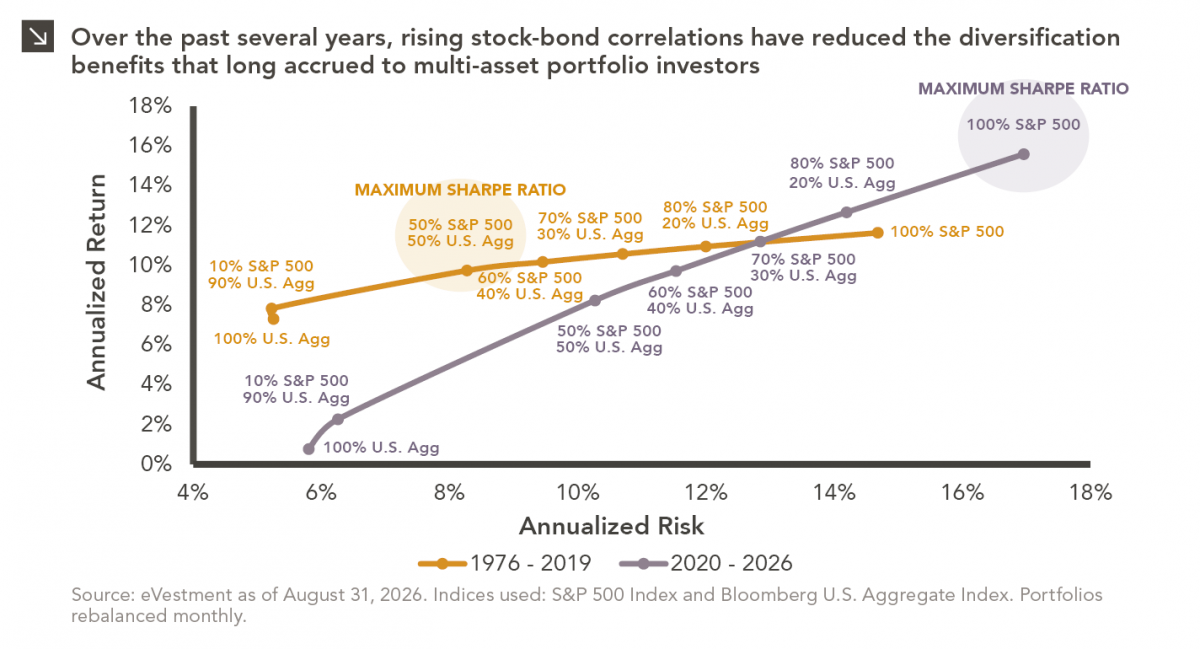
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
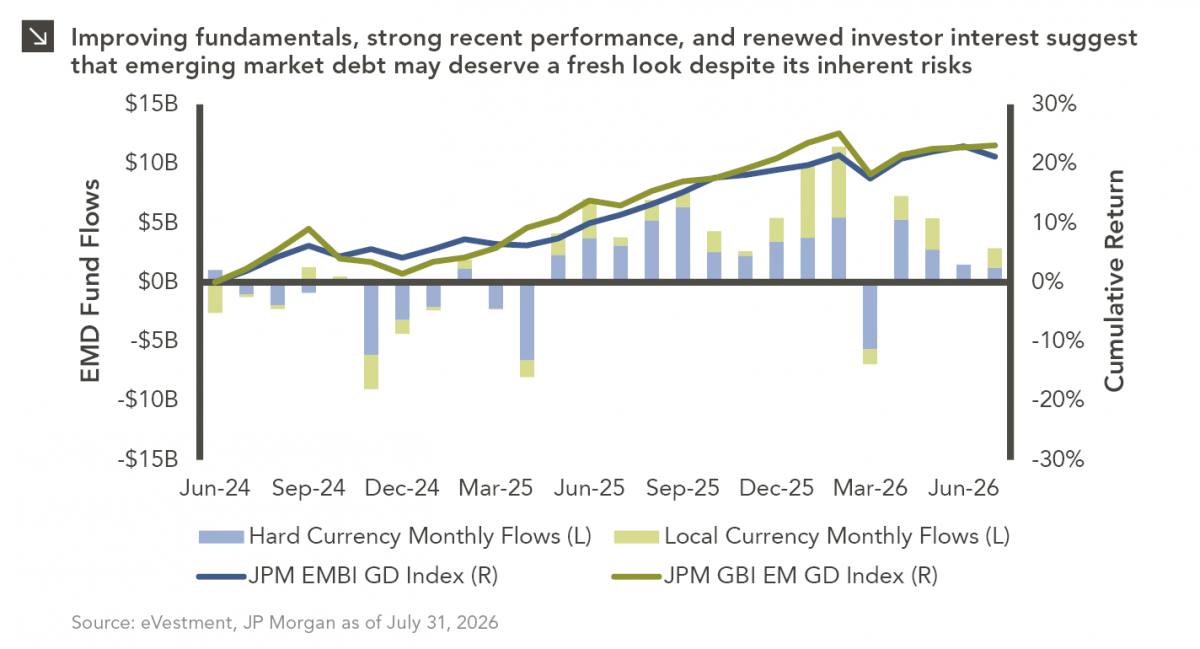
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >