James Torgerson
Senior Research Analyst


Fixed income is the largest global financial market and often one of the largest allocations within institutional investors’ portfolios. A typical fixed income allocation implements an investment grade anchor with a few “satellite” mandates — most commonly high yield bonds, leveraged loans, and emerging market debt — that carry more credit risk but provide higher levels of yield. Fixed income portfolios are often over-exposed to corporate borrowers through both anchor and satellite allocations. Additionally, these satellite allocations usually increase corporate credit risk while reducing equity diversification that fixed income is supposed to provide. Securitized credit provides higher yields and more compelling diversification benefits.
Securitized credit is a large asset class that has been largely ignored by institutional investors due to under-representation in fixed income indices, perceived complexities, and a stigma from its role in the Great Financial Crisis. While factors responsible for under-allocation to securitized credit have merits, these have caused investors to overlook the benefits of the asset class. Securitized credit provides a spread and yield premium relative to similarly rated corporate credit, diversified risk exposure to various credit and market cycles, and lower correlation to both traditional fixed income and equities. Overall, securitized credit’s attributes can help to further optimize portfolio structures.
Read > A Portfolio Needs Structure: An Overview of the Securitized Credit Asset Class
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

10.08.2026
LIVE WEBINAR — OCTOBER 22 Please join Marquette’s research team for our 3Q 2026 Market Insights Webinar…

09.28.2026
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

09.15.2026
Over the past decade, continuation vehicles (“CV”) have become one of the fastest-growing trends in private equity. Private equity funds…

09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
08.24.2026
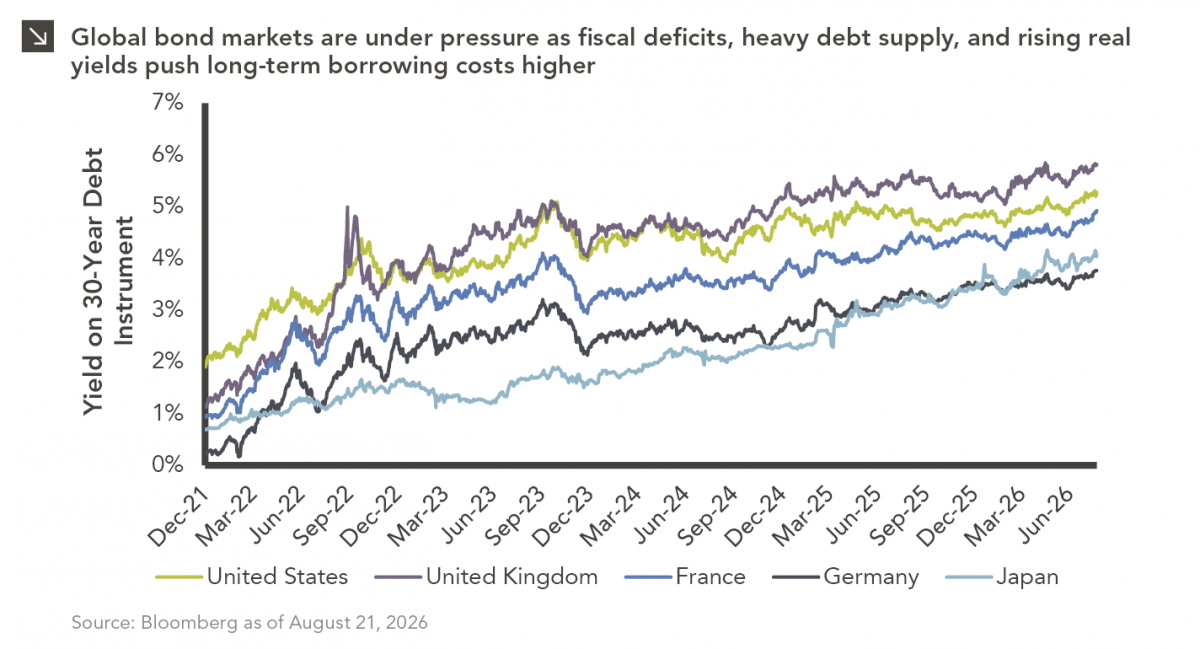
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…
08.17.2026
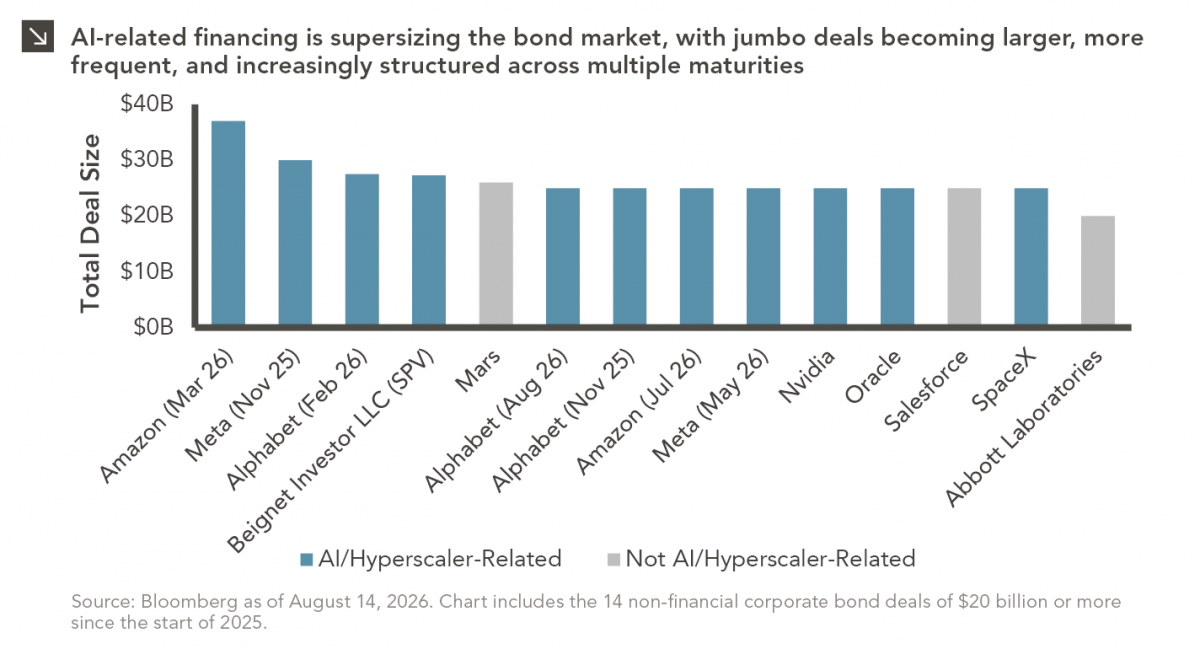
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >