Hayley McCollum
Senior Research Analyst


It has been well documented that private equity has been experiencing pressures over the past two years, marked by declines in both deal activity and recent performance relative to the strong returns generated in prior years. Since the asset class is heavily reliant on leverage to fund deals, the private equity landscape has been impacted by the historic rise in interest rates that has made debt more expensive over the last several quarters. That said, the Federal Reserve has now shifted its policy stance with inflation seemingly contained, and several rate cuts are expected to occur in the near term. But will lower rates drive a rebound in private equity activity?
While a recovery in activity likely won’t occur overnight, private equity firms seem to be preparing for a significant increase in deal making on the horizon. Due to the high financing costs associated with higher interest rates, recent years have seen a shift away from debt-laden leveraged buyouts (LBOs) and towards growth and expansion deals, as those transactions typically require minimal leverage. Over most of the last 15 years, LBOs consistently accounted for a larger share of U.S. private equity deals relative to growth and expansion transactions, but this dynamic reversed in 2023. We do not expect recent trends to continue in perpetuity since lower borrowing costs should usher in a new wave of LBO activity. More broadly, M&A activity appears to be showing signs of turning a corner. To that point, in the first half of this year, North American M&A activity advanced by roughly 13% on a year-over-year basis in terms of both deal count and value (including estimates for unreported deals).
In short, recent shifts in monetary policy may provide tailwinds for the private equity sector. In addition to lower borrowing costs that will likely underpin future deal activity, rate cuts also benefit existing portfolio companies by easing the debt service burdens on their balance sheets. This offers companies the flexibility to pursue new acquisitions, initiate organic growth initiatives, and, ultimately, drive potential returns higher for investors. As always, we continue to closely monitor the emerging trends and their implications for the performance of the private equity asset class.
Print PDF
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
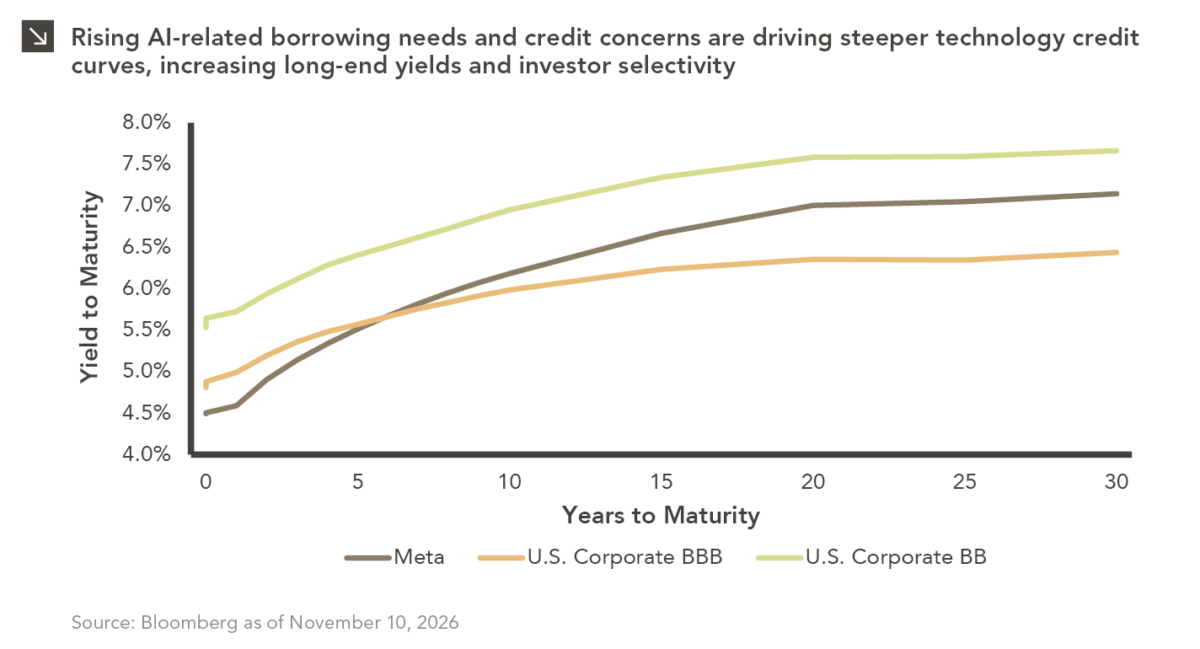
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >