10.05.2026
Spooky Season
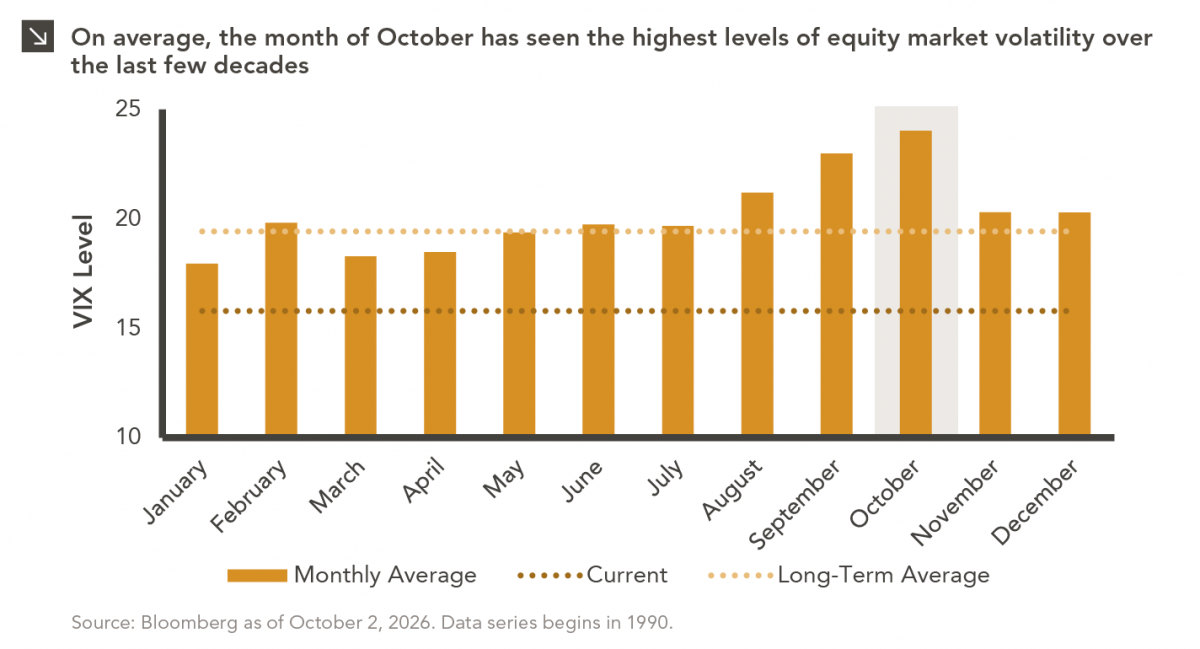
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…


While the United States has historically prioritized public spending on education more than other developed countries, there has been a recent convergence in U.S. education expenditure as a percentage of GDP with that of other countries in the OECD, a group of mostly developed and democratic nations. Specifically, in 2000, the U.S. spent 6.1% of total GDP on education, which was notably higher than the OECD average of 4.9% at that time. That said, the U.S. figure dropped to 4.7% in 2016, which was slightly below the 4.8% OECD average that year. Based on this trend, it should come as no surprise that U.S. students are beginning to fall behind their global peers in key academic areas. To that point, U.S. K-12 students ranked 12th and 28th in science and math, respectively, out of 37 OECD member countries in 2022 according to Pew Research. The U.S. average score for math fell by a whopping 13 percentage points between 2018 and 2022 alone.
While the challenges faced by U.S. students due to the COVID-19 pandemic were significant, the fact that U.S. now spends roughly the same as other developed nations (as a percentage of GDP) has certainly contributed to these lackluster scores. Going forward, a renewed focus on education-related spending and outcomes should serve the U.S. well, as a robust public education system helps drive economic growth, stability, and innovation.
Print PDFThe opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.05.2026
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
09.28.2026
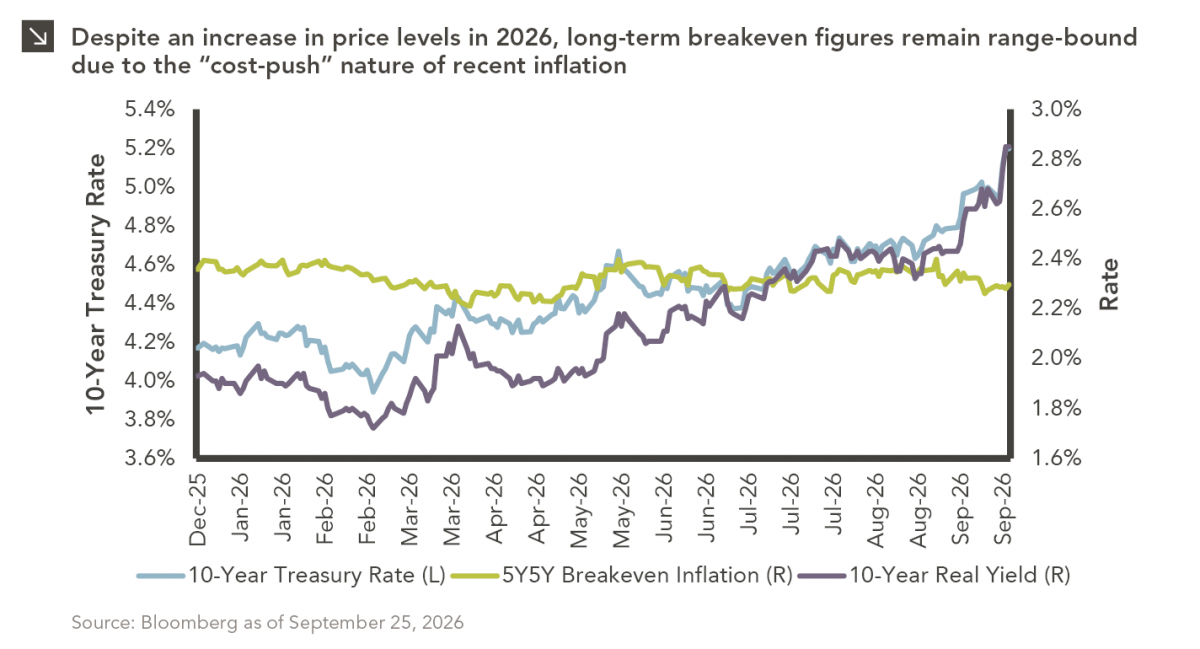
The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….
09.21.2026
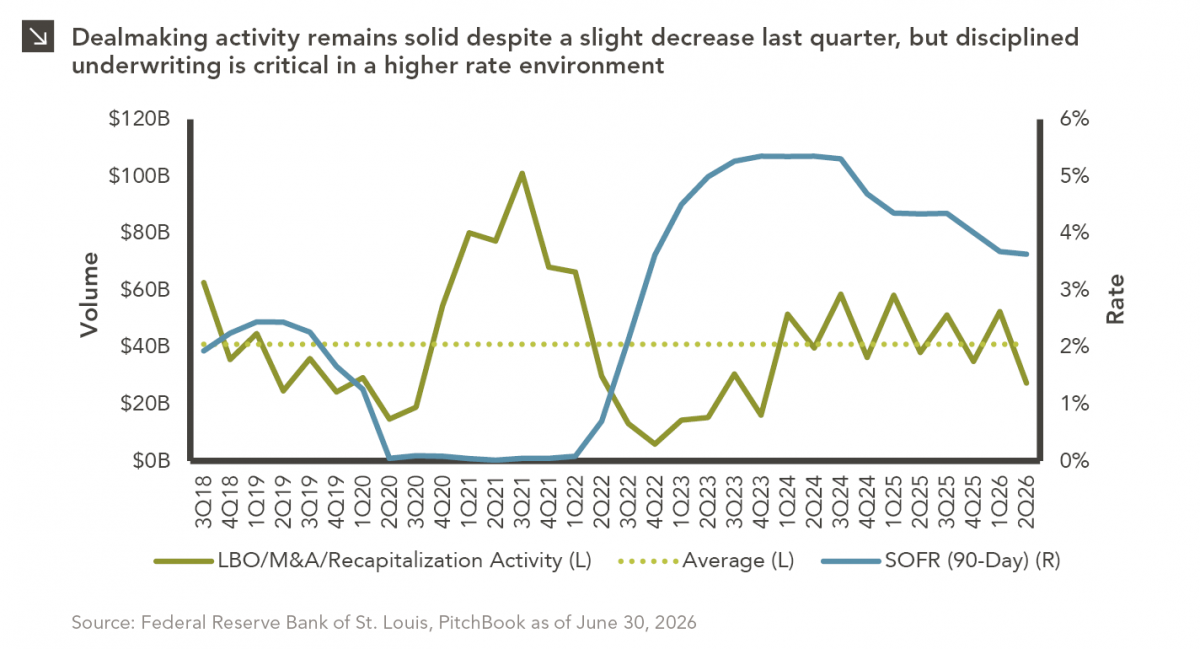
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would…
09.14.2026
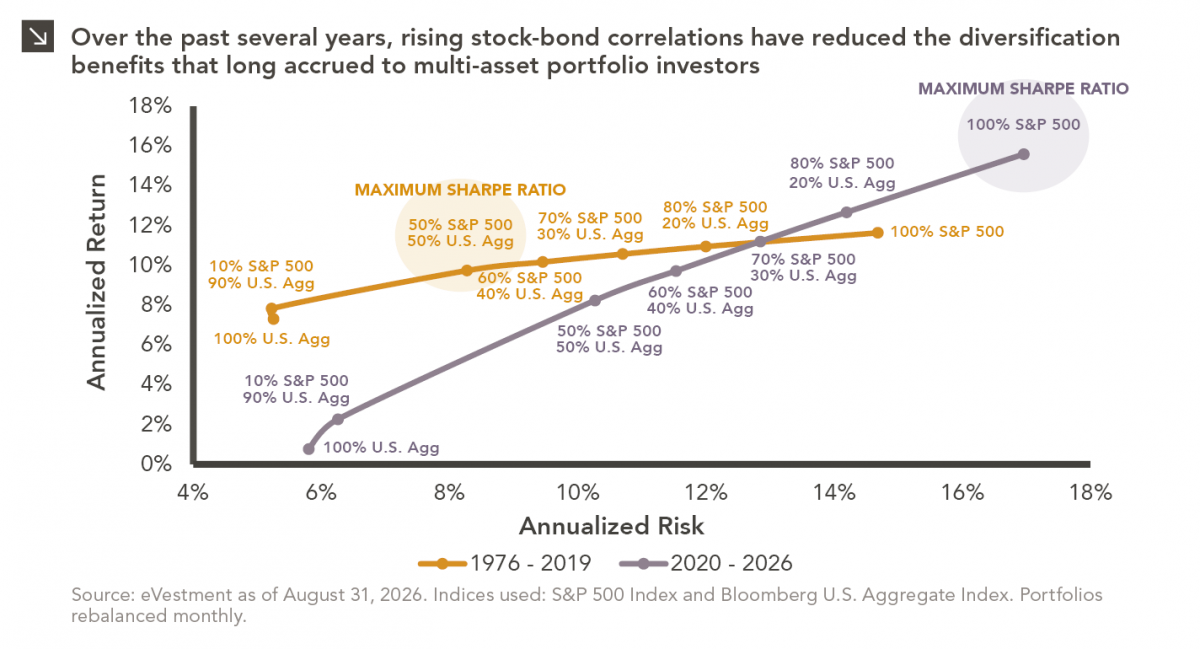
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…
09.08.2026
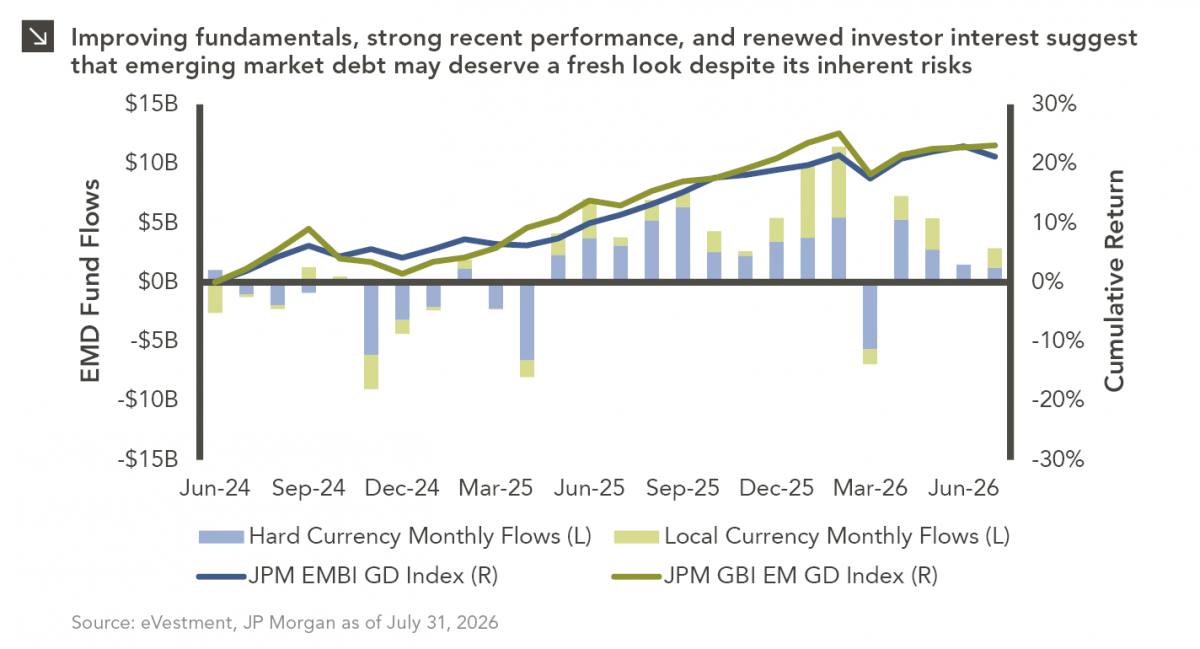
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…
08.31.2026
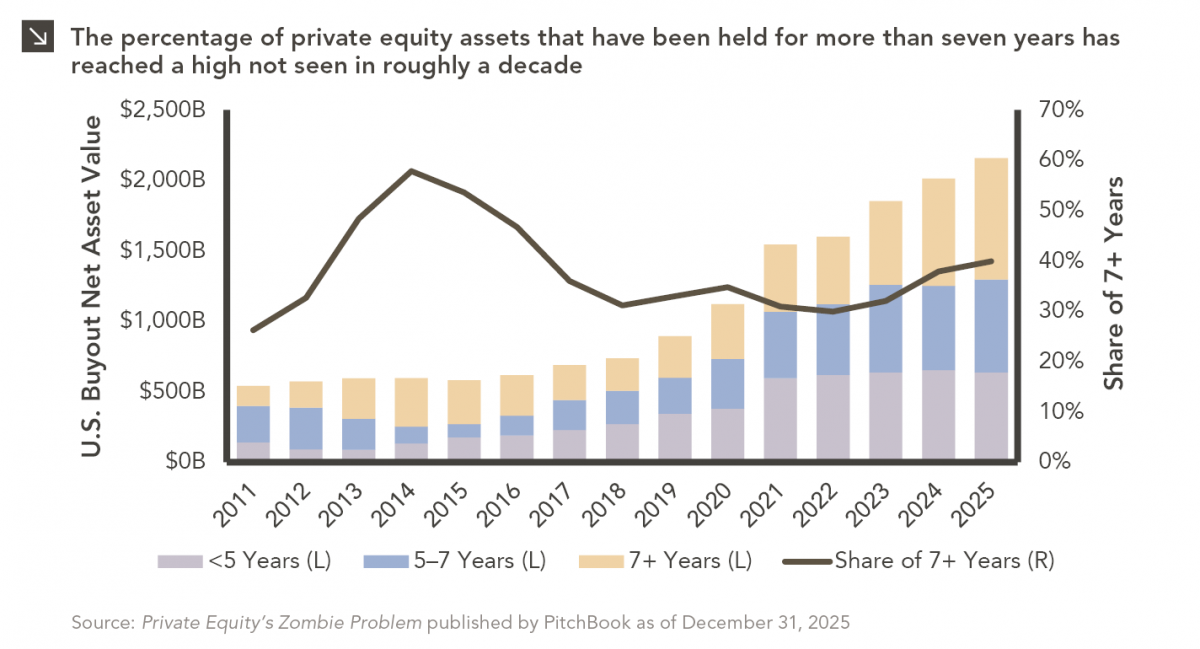
Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >