Amy Miller
Associate Director of Private Equity


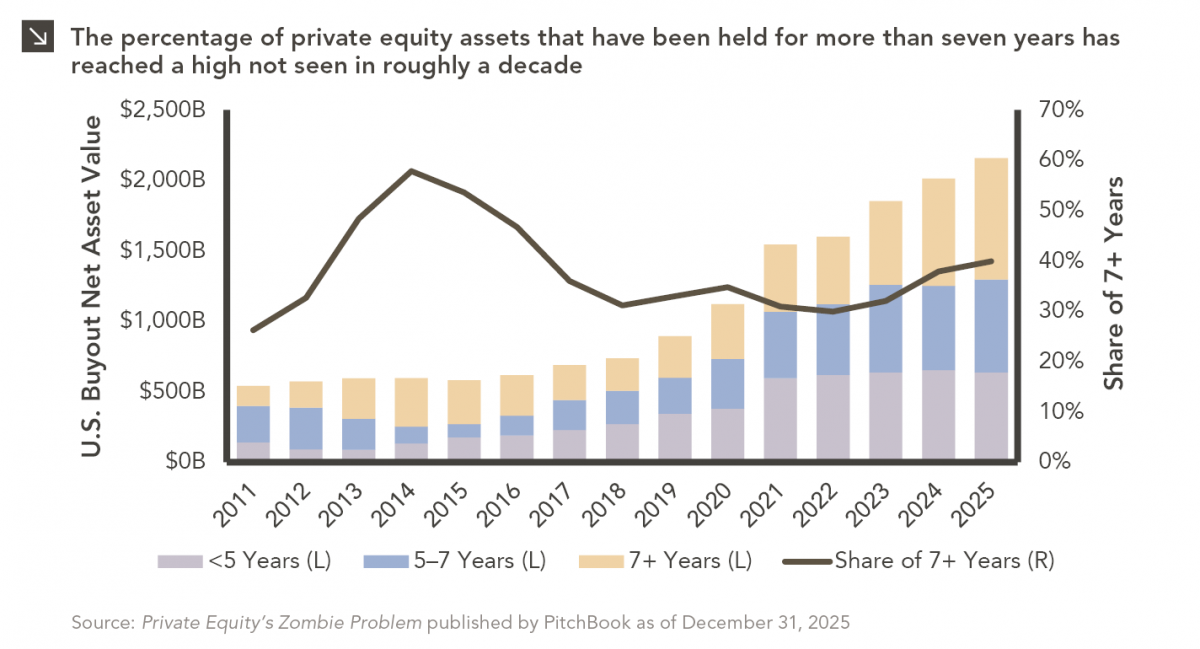
Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears to be hosting an entire zombie convention. The occasional underperformer has given way to a growing pool of aging assets that remain operational and solvent but increasingly difficult to exit. According to PitchBook, more than one-third of U.S. private equity-backed companies have been held for over five years, with hold periods for thousands now exceeding the traditional exit window. The causes of this trend are not mysterious. In hindsight, the industry may have committed the cardinal sin of every market cycle: mistaking favorable conditions for permanent conditions. Between 2020 and 2021, sponsors acquired businesses amid an environment of near-zero interest rates, abundant leverage, and valuation multiples that appeared destined to move only upward. That said, when rates rose and multiples compressed in 2022, two of private equity’s favorite value drivers, cheap debt and multiple expansion, suddenly disappeared. The result was a cohort of companies purchased at EBITDA multiples of 12x or greater that now struggle to justify valuations of 10x or less.
These “zombie companies” tend to share a similar profile. Specifically, they tend to be older assets with extended hold periods, elevated leverage, slowing earnings growth, and limited buyer interest. Further, many have not completed a refinancing, recapitalization, add-on acquisition, or meaningful transaction in years. It is important to note that zombie companies tend not to be bankrupt. In fact, that is part of the problem. Thanks to covenant-lite loans, amend-and-extend transactions, and payment-in-kind interest, companies can survive almost indefinitely without truly improving. In short, these businesses are less “walking dead” and more “comfortably numb.”
For limited partners, the implications of this dynamic are becoming increasingly difficult to ignore. From a liquidity standpoint, DPI (a key performance metric in private equity that measures the cash returned to investors relative to the capital they invested) has lagged historical norms in recent time (particularly for 2018–2022 vintages), while TVPI (a metric that measures a private equity fund’s total return compared to the actual money investors have paid in) has remained stubbornly stable. In plain English, paper value is not turning into cash for private equity investors. Indeed, limited partners expected distributions but have instead received an education on quarterly valuations and continuation vehicles. More subtly, zombies threaten one of private equity’s defining advantages: efficient capital recycling. As managers spend more time extending maturities and defending marks (rather than sourcing exits), capital cannot be redeployed into new opportunities. Continuation vehicles, while often legitimate solutions to liquidity challenges, increasingly risk looking less like a value-creation tool and more like the industry’s version of moving leftovers into a different container.
The good news for limited partners is that the rise of zombie companies appears to be a growth inhibitor for the asset class rather than a systemic crisis, and it is important to remember that most private equity funds are designed to absorb precisely this kind of stress. The bad news is that patience, once considered a virtue, may now be considered a holding strategy. As the living learn, the dead rarely disappear on their own.
Print PDF
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.12.2026
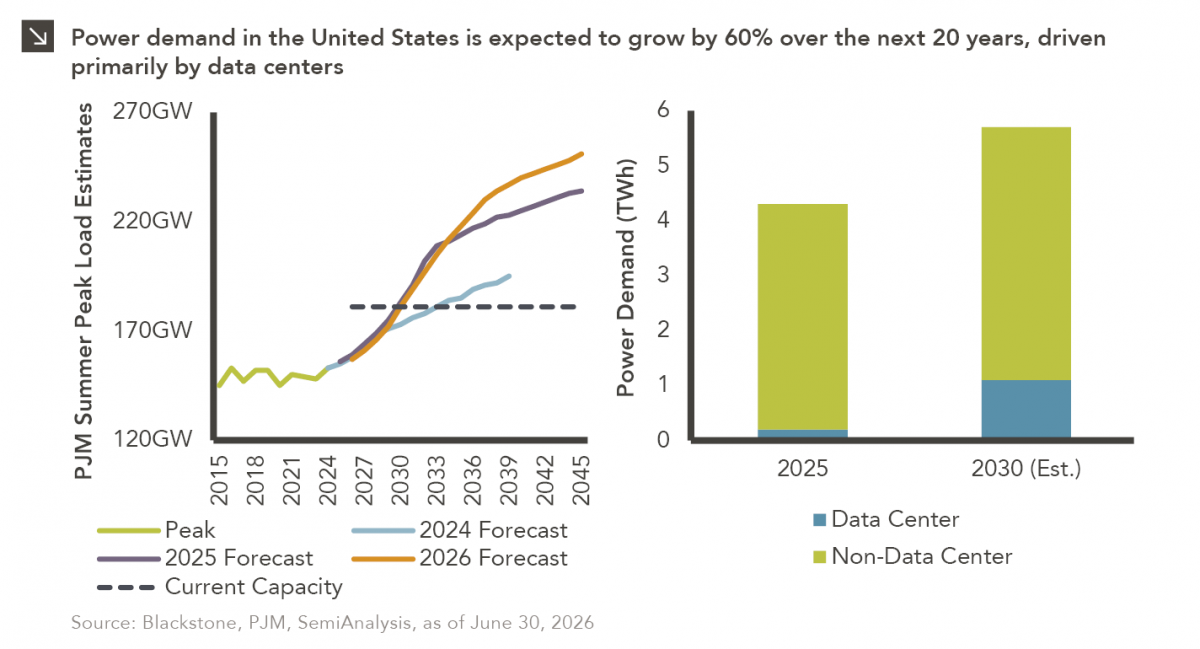
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >