Consumer Sentiment: Harbinger for Recession or a Reflection of Pain at the Pump?

June 01, 2022 | Chad Sheaffer, CFA, CAIA, Associate Director of Private Credit

Two-line chart showing U.S. consumer sentiment and average gas price per gallon. Chart subtitle: Consumer sentiment fell in May to the lowest level in more than 10 years. Chart visual description: Chart has two y-axes. Left y-axis shows University of Michigan Consumer Sentiment Index Level, ranging from 50 to 120, with corresponding line in light purple. Right y-axis shows U.S. National Avg. Retail Gas Price, from $5.00 to $0 (inverted), with corresponding line in slate. X-axis shows years from 1990 through May 31, 2022 (though labels only show through 2021) in two-year increments. Recession periods are shaded in light green. Chart data description: As described in the write-up, since its inception in 1978, the consumer sentiment index has posted a reading below 60 in only three other distinct periods: the late stages of the stagflationary environment in 1980, the Global Financial Crisis in 2008-2009, and a brief period in 2011 when S&P Global Ratings downgraded U.S. Treasury debt. The May reading came in at 58.4, the lowest reading since August 2011. The gasoline price line very closely parallels the consumer sentiment index line across all time shown, with the exception of the Global Financial Crisis, when gasoline prices decreased along with consumer sentiment. May 2022’s average price per gallon was $4.44. Chart sources: University of Michigan, U.S. Energy Information Administration, Bloomberg. End chart description.

U.S. consumer sentiment has become increasingly pessimistic in 2022 as a plethora of macro headwinds have created uncertainty. The University of Michigan Consumer Sentiment Index, a key proxy for consumer confidence, fell to 58.4 in May, the lowest reading since August 2011. The survey aggregates consumer views across a range of questions including personal finances, general business conditions, housing market conditions, spending expectations, and outlook. The overall level of the index and the relative change from prior readings provide an indication as to how consumers feel about the current and future U.S. economy. Since its inception in 1978, the survey has posted a reading below 60 in only three other distinct periods: the late stages of the stagflationary environment in 1980, the Global Financial Crisis in 2008–2009, and a brief period in 2011 when S&P Global Ratings downgraded U.S. Treasury debt.

Despite consumer spending comprising the majority of GDP, extremely bearish consumer sentiment has historically been a poor predictor of recession. Survey readings below 60 have coincided with a recession only 33% of the time (two out of six recessions) since 1978. Consumer sentiment surveys seem to be far more indicative of the current consumer experience than the longer-term economic outlook. As seen in this week’s chart, the University of Michigan Consumer Sentiment Index has shown a strong correlation to gasoline prices — a very visible component of inflation for most consumers — especially during periods of rising gas prices. While current sentiment can have a very real impact on economic growth via consumer spending, it is important to consider this metric alongside other economic measures, many of which still show consumer strength. With the market laser-focused on the health of the U.S. consumer and the risk of recession, we will continue to monitor various economic indicators and advise our clients accordingly.

Print PDF > Consumer Sentiment: Harbinger for Recession or a Reflection of Pain at the Pump?


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Chad Sheaffer, CFA, CAIA
Associate Director of Private Credit

Get to Know Chad

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

Stacked bar chart showing U.S. private equity deal value by deal size from Q1 2022 through Q2 2026. The y-axis shows percentage of total deal value from 0% to 100%, and the x-axis shows quarters by year. Stacked bar chart showing the percentage of U.S. private equity deal count by deal size from Q1 2022 through Q2 2026. The y-axis ranges from 0% to 100%, and the x-axis shows quarters by year. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.26.2026

Smaller Deals, Larger Appeal

Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026

3Q 2026 Market Insights

This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026

Will Higher Rates Cramp the Markets?

Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

Line chart comparing S&P 500 Index cumulative returns for midterm and non-midterm election years since 1980. The x-axis shows October through December, and the y-axis shows S&P 500 Index cumulative return, ranging from -1% to 8%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.19.2026

Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

Chart #1 - Line chart showing PJM summer peak load estimates in gigawatts (GW) from 2015 to 2045. The chart compares historical peak load, current capacity, and forecasts from 2024, 2025, and 2026, showing projected demand rising above current capacity over time. Chart #2 - Stacked bar chart showing U.S. power demand in terawatt-hours (TWh) for 2025 and estimated demand in 2030. The chart compares data center and non-data center demand, showing total power demand increasing over the period.

10.12.2026

The Power Demand Supercycle

This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
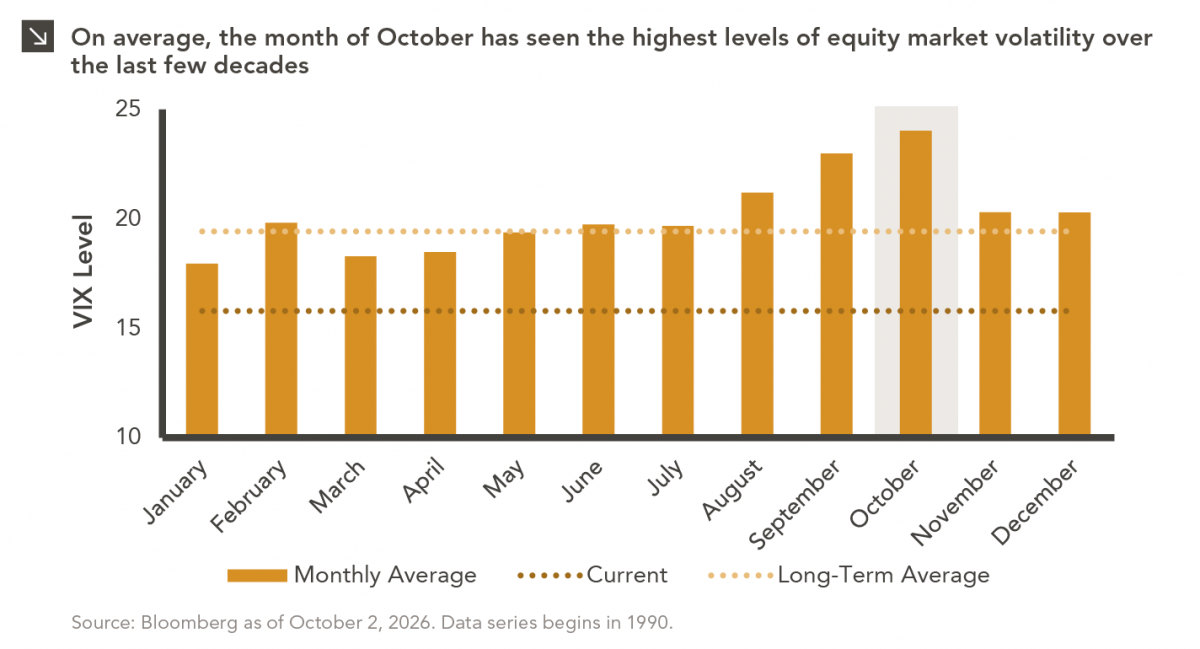
Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >