Taylor Rule Provides Clues to Future Short-Term Rates

Developed by Stanford economist John Taylor in 1992, the Taylor Rule is a mathematical model designed to estimate the level of short-term interest rates consistent with the Federal Reserve’s mandate to promote price stability and full employment. In making its prediction, the model measures current inflation and unemployment data against a set of ideal targets.

Developed by Stanford economist John Taylor in 1992, the Taylor Rule is a mathematical model designed to estimate the level of short-term interest rates consistent with the Federal Reserve’s mandate to promote price stability and full employment. In making its prediction, the model measures current inflation and unemployment data against a set of ideal targets. Currently, the model utilizes the Fed’s stated inflation target of 2% and an unemployment rate of 5.6% as the ideals for a healthy economic environment.

Prior to the great recession, the output of the Taylor Rule proved to be fairly accurate in predicting short-term interest rates. As the financial crisis deepened, however, the Taylor Rule began to suggest that a negative level of short-term rates would be necessary in order to restore economic growth. Bound by zero as the floor for interest rates, the Fed was unable to lower short-term rates to meet the level prescribed by the Taylor Rule. With further interest rate decreases no longer an option, the Fed turned to quantitative easing as a means to further loosen monetary policy. Five years later, with the U.S. economy on more stable ground, the level of short-term rates prescribed by the Taylor Rule has once again turned positive. Not surprisingly, the Fed has begun to slow the pace of quantitative easing with the program scheduled to come to an end altogether later this year. As investors eye Fed clues for the future path of short-term rates, consider the Taylor Rule as a useful guide.

Good News for “Abenomics” and Japanese Wage Growth

In an attempt to revive the long struggling Japanese economy, Prime Minister Shinzo Abe implemented his “Abenomics” strategy which included an unprecedented open-ended asset purchase program. The monetary easing policy was implemented with the goal of spurring domestic spending and increasing exports via a devalued currency.

In an attempt to revive the long struggling Japanese economy, Prime Minister Shinzo Abe implemented his “Abenomics” strategy which included an unprecedented open-ended asset purchase program. The monetary easing policy was implemented with the goal of spurring domestic spending and increasing exports via a devalued currency. Equity investors reacted positively to the plan and the MSCI Japan Index returned 27.4% in 2013. With both corporate profits and business confidence rising, the initial results of “Abenomics” appear promising.

To keep things on course, Japanese companies will need to boost workers’ wages, a phenomenon that has rarely occurred for earners. This week’s chart shows the year-over-year change in wage earnings has been largely negative over the last 24 months. However in recent weeks during the annual wage negotiations (known as “shunto,” which translates to “spring offensive”) between unions and employers, several large companies, including Toyota, Honda, and Toshiba announced significant wage increases for the first time since 2008. Now economists will observe whether medium and small size companies follow suit. A rise in wages will help continue the initial positive momentum created by the monetary easing policies of “Abenomics” and could mean Japanese equities still have some upside left.

Economic Surprise Index Turns Negative

In this week’s chart we take a look at the CITI Economic Surprise Index. As a matter of background, the CITI Economic Surprise Index is a composition of various economic indicators that are released; anything above 0 indicates that economic reports are beating expectations and anything below 0 is underperforming estimates.

In this week’s chart, we take a look at the CITI Economic Surprise Index. As a matter of background, the CITI Economic Surprise Index is a composition of various economic indicators that are released; anything above 0 indicates that economic reports are beating expectations and anything below 0 is underperforming estimates. Since its peak in mid-January, the index has been on a steady decline and just reached its lowest point since June of last year.

The start of 2014 saw several key economic indicators fall short of expectations including retail sales, new jobs, manufacturing, and the consumer confidence index; such trends help explain the decline. On the bright side, many experts have blamed the historically dreadful weather conditions as key contributors to such pull-backs in economic activity, and expect a rebound once spring arrives. Indeed, the market appears to agree: after a negative January (-3.5%), the S&P 500 returned 4.6% in February, shrugging off much of the poor economic data. Given the optimistic outlook shared by most economists for 2014, it is expected that the Economic Surprise Index will swing back to positive territory as winter gives way to spring.

Expect Fed Funds Rate to Remain Unchanged at 6.5% Unemployment

With the unemployment rate (6.6%) approaching the Fed’s forward guidance target of 6.5%, this week’s chart examines two additional labor market indicators: the number of people working part time for economic reasons and the number of individuals who have been unemployed for longer than six months.

With the unemployment rate (6.6%) approaching the Fed’s forward guidance target of 6.5%, this week’s chart examines two additional labor market indicators: the number of people working part-time for economic reasons and the number of individuals who have been unemployed for longer than six months. In her February report to Congress, the new Fed Chairperson, Janet Yellen, identified these two data points as important gauges for evaluating the health of the U.S. job market.

While we have seen steady improvement in the headline unemployment number (down from a high of 10.0%), much of the “recovery” has been due to a decreasing labor participation rate, and overall the labor market remains relatively weak. Many individuals have resorted to working part-time due to poor labor demand and this segment constitutes 5.3% of currently “employed” workers. While below the high (7.0%) it is still above the long-term average of 4.4%. In addition, a large percentage of the unemployed (35.6%) have been so for more than six months. This is above the long-term average of 25.5% yet below the peak of 45%.

With the risk of inflation remaining relatively low, the market expects the central bank to refrain from increasing the fed funds rate at least through the first half of 2014 in an attempt to strengthen the economy and labor market even if the unemployment rate drops below 6.5%.

Price Recovery in Secondary Market for Private Equity

This week’s chart looks at median secondary market pricing for private equity fund interests. Because private equity is an illiquid asset class, investors that have private equity portfolios and need immediate liquidity must sell their interests in existing private equity funds to other investors.

This week’s chart looks at median secondary market pricing for private equity fund interests. Because private equity is an illiquid asset class, investors that have private equity portfolios and need immediate liquidity must sell their interests in existing private equity funds to other investors. This is called the “secondary market”, which has grown substantially since the credit crisis; over $20 billion of fund interests traded hands in 2013 on the secondary market. The above chart shows that in the immediate aftermath of the credit crisis, during 2009, buyers required a steep discount to net asset values to assume the risks of existing fund interests. At the bottom of the market, during the second quarter of 2009, sellers received just $0.30 on the dollar if they decided to sell their private equity investments. However, as the crisis abated those steep discounts vanished. Pricing was particularly aggressive in 2013 with secondary buyers requiring only a 7–10% discount to net asset value. Given these modest discounts, it appears the opportunities in the private equity secondary market are scarce these days.

Youth Unemployment and Aggregate Student Debt

This week we take a look at the unemployment rates among young people and the rising levels of student debt. Following the crash in 2008 the aggregate student debt has more than doubled, rising from $500 billion to over $1 trillion. This is the result of not only traditional students struggling to afford tuition, but also due to many people returning to school in the hopes of improving their skill sets in a tough job market.

This week we take a look at the unemployment rates among young people and the rising levels of student debt. Following the crash in 2008, the aggregate student debt has more than doubled, rising from $500 billion to over $1 trillion. This is the result of not only traditional students struggling to afford tuition, but also due to many people returning to school in the hopes of improving their skill sets in a tough job market. The drastic increase is even more worrisome given the high levels of unemployment facing those who carry the majority of this debt. Workers between the ages of 15 and 24 are significantly more likely to be unemployed than their elders, with their current unemployment rate at 14.2% compared to 6.1% for those ages 25-54.

However, this is not necessarily as bad as it seems. As high as the present unemployment numbers are compared to the rest of the population, they are fairly consistent with historical averages. Additionally, the systematically high youth unemployment is not unique to the U.S. Most recently available data shows this figure in the European Union as 23.3% compared to 10.8% for the total population, and 16.0% and 7.8% respectively, among OECD countries.

Ultimately, there are two primary worries about the massive level of student debt. The first — and most obvious — is a widespread pattern of defaults on this outstanding debt, a potential disruption to the credit markets, and by extension, a headwind for growth. The second — while not as severe but still a threat to economic growth — is a reduction in consumption from students who are spending a larger percentage of their income on debt service, rather than consuming goods and services. Collectively, these two forces could emerge as a drag on economic growth at a time when the U.S. economy seems to need all the help it can get.

The Fragile Five

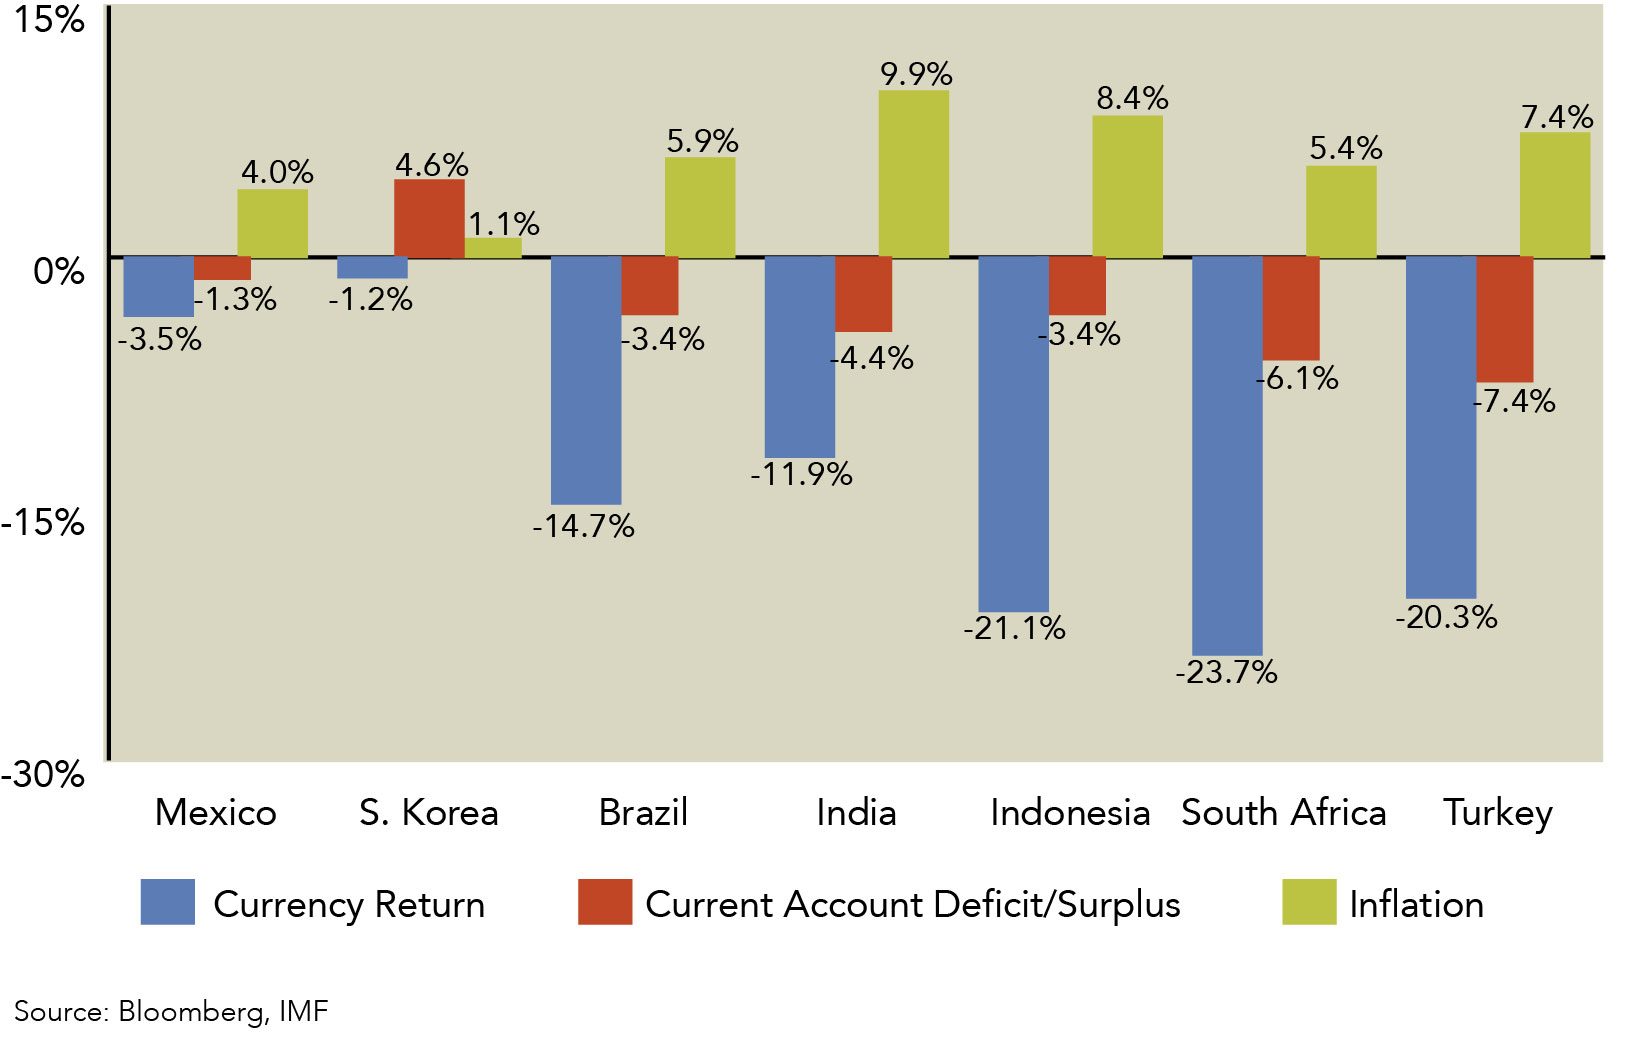
Given the continued poor performance of emerging market (“EM”) investments, this week’s chart examines the structural issues challenging a number of EM countries, namely the “fragile five” (Brazil, India, South Africa, Turkey, and Indonesia). The chart illustrates how countries with high inflation and large current account deficits have seen their currencies decrease dramatically against the U.S. dollar.

Given the continued poor performance of emerging market (“EM”) investments, this week’s chart examines the structural issues challenging a number of EM countries, namely the “fragile five” (Brazil, India, South Africa, Turkey, and Indonesia). The chart illustrates how countries with high inflation and large current account deficits have seen their currencies decrease dramatically against the U.S. dollar. In comparison the currencies of Mexico and South Korea have remained relatively resilient.

As liquidity is gradually withdrawn from the global economy, these structural issues within emerging markets have come to the forefront. Investors are concerned that after years of expansion and unlimited access to cheap capital despite poor policy fundamentals, these EM countries will have a very difficult time implementing the necessary structural reforms, while also maintaining strong growth.

In response, central banks of all the fragile five countries have taken decisive action and increased their benchmark interest rates within the last four months. Furthermore, due to emerging markets’ continued weak performance, valuations are not only attractive for the asset class as a whole, but more importantly for stronger and more stable EM countries such as Mexico and South Korea. While there is still policy and political uncertainty affecting emerging markets, there is no doubt that value is present in the asset class.

*Currency return from January 1, 2013 to February 4, 2014.

Can Continuing Employment Growth Boost Business Spending?

This week’s chart of the week compares business spending (represented by non-defense capital goods orders) to employment (represented by total nonfarm employees) in the United States. As the chart illustrates, both employment and business spending have been steadily rising since the economic recovery began back in 2009.

This week’s chart of the week compares business spending (represented by non-defense capital goods orders) to employment (represented by total nonfarm employees) in the United States. As the chart illustrates, both employment and business spending have been steadily rising since the economic recovery began back in 2009. However, the growth of business spending, which contributed significantly to economic growth in the early stages of the recovery (increasing by an average of approximately $640 million per month from May 2009 through December 2011) has slowed as of late (increasing by an average of approximately $34 million per month from January 2012 through December 2013).

Employment growth, on the other hand, has been fairly steady over the past several years (increasing by an average of approximately 180,000 jobs per month each of the past three calendar years). With the ongoing strength in employment growth, the United States is approaching a new all-time high in total employment (i.e., peak employment). At the current rate of employment growth, the United States should reach a new peak employment this summer. This is a significant development because reaching new peak employment has historically led to significant growth in business spending, as businesses have to purchase new technology, equipment, and space to accommodate a larger workforce.

It will be important to monitor how businesses react once the economy reaches new peak employment. If business spending increases as it has in the past, it will provide another tailwind to an already strengthening economic recovery.

Is the Stock Market Overpriced?

Given the monumental run of the equity markets in 2013, we have frequently been asked if the stock market (as measured by the S&P 500 index) is overvalued heading into 2014. The answer unfortunately is not a simple yes or no, because it depends on the valuation method and measurement period.

Given the monumental run of the equity markets in 2013, we have frequently been asked if the stock market (as measured by the S&P 500 index) is overvalued heading into 2014. The answer unfortunately is not a simple yes or no, because it depends on the valuation method and measurement period. This week’s Chart of the Week looks at one valuation measure, the S&P 500 trailing 12-month price-to-earnings (P/E) ratio. We compare today’s P/E ratio with its 10, 20, 30, and 40-year averages.

As the chart shows, there is no clear cut answer when comparing these different averages to the current value — the analysis is very much contingent on the time period utilized when calculating the long-term average. Based on the 20- and 30-year averages one may conclude that the market is fairly priced, if not underpriced. However, the exaggerated P/E ratios as part of the tech bubble likely provide an upward bias to truly objective “long-term” averages. Fortunately, the 40-year average is sufficient to more effectively smooth out the spikes from the Tech Bubble valuations. Using this time period to determine the long-term average, it does indeed appear that the market is overvalued and expensive by historical means. However, this is far from a guarantee that the market will experience a correction in 2014, though we encourage our clients who experienced outsized gains in their equity portfolios in 2013 to consider rebalancing back to their target ranges. If nothing else, one thing is for sure: in order to sustain this current bull market run, the S&P 500 will need to produce strong earnings growth over the next year.

A Challenging Year for Core Bonds

This week’s chart depicts the challenging environment core fixed income investors faced in 2013. The ten-year Treasury rate jumped causing significant price depreciation while the coupons failed to cover the losses.

This week’s chart depicts the challenging environment core fixed income investors faced in 2013. The ten-year Treasury rate jumped causing significant price depreciation while the coupons failed to cover the losses. The Barclays Agg index declined 2.0% in 2013, the first negative calendar year return since 1999. This performance was made up of a -4.6% price return and a 2.6% coupon return.

Facing the prospects of low income and prices losses, many investors transitioned away from traditional core bonds in favor of higher yields and/or lower interest rate risk. It should be noted that this allocation change generally accompanies an increase in credit risk as there is no free lunch. While the bull market in fixed income is likely over and return expectations have been lowered, traditional bonds still serve an important role as an anchor to diversified portfolios, providing a steady source of income and principal repayment to investors.