11.16.2026
Business in the Front, Party in the Back
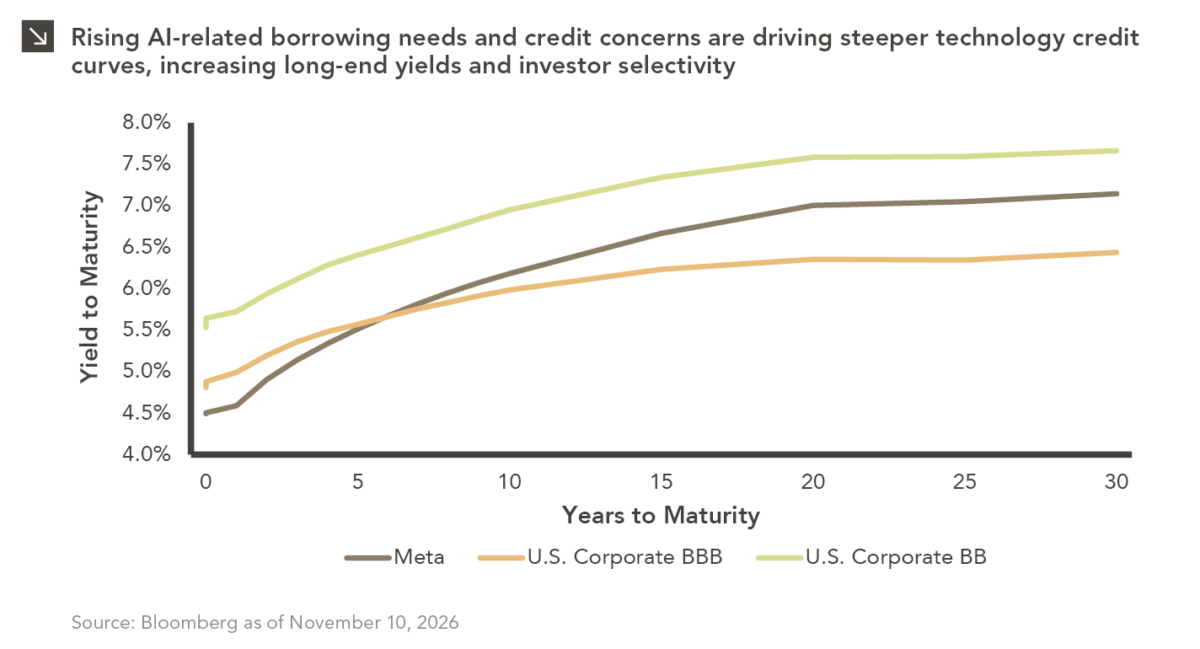
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…


Earlier this month, wildfires broke out across Los Angeles County, California, destroying more than 12,000 homes, businesses, schools, and other structures. Officials recently reported a total of 40,700 acres have burned across the area, with some of the blazes still only partially contained. According to Goldman Sachs estimates, the fires have resulted in roughly $40 billion in losses ($10–30 billion of which are insured) and could lead to a 0.2% drag on first quarter U.S. GDP growth. This potential impact, while significant, would be smaller than those of other natural disasters in U.S. history, including Hurricanes Katrina (2005) and Harvey (2017). These types of events typically result in short-term economic disruptions, but lost economic output is often gradually recovered as federal aid and insurance payouts allow communities to rebuild. As such, the cumulative economic impact of the wildfires may ultimately be lower than current estimates as eventual reconstruction efforts will likely provide a boost to GDP.
The wildfires in California are drawing attention to the availability and price of homeowners insurance, as the state faces frequent disasters, high real estate prices, and an uncertain insurance landscape. To that point, seven of the 12 largest insurance companies have either paused or restricted new policies in California due to the frequency and severity of natural disasters over the last decade. On January 10, the California Department of Insurance announced a one-year moratorium on the cancelation or non-renewal of homeowners insurance policies by carriers in specific areas affected by the wildfires. In coming years, California homeowners may see a shift in property insurance away from standard policies to provide higher risk coverage at higher rates.
Print PDFThe opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
11.16.2026
Corporate bond spreads are not homogeneous, meaning they are rarely consistent across the yield curve. For instance, the Meta curve…

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

11.02.2026
Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >