Tom Neuhardt, CFA
Associate Research Analyst
Get to Know Thomas


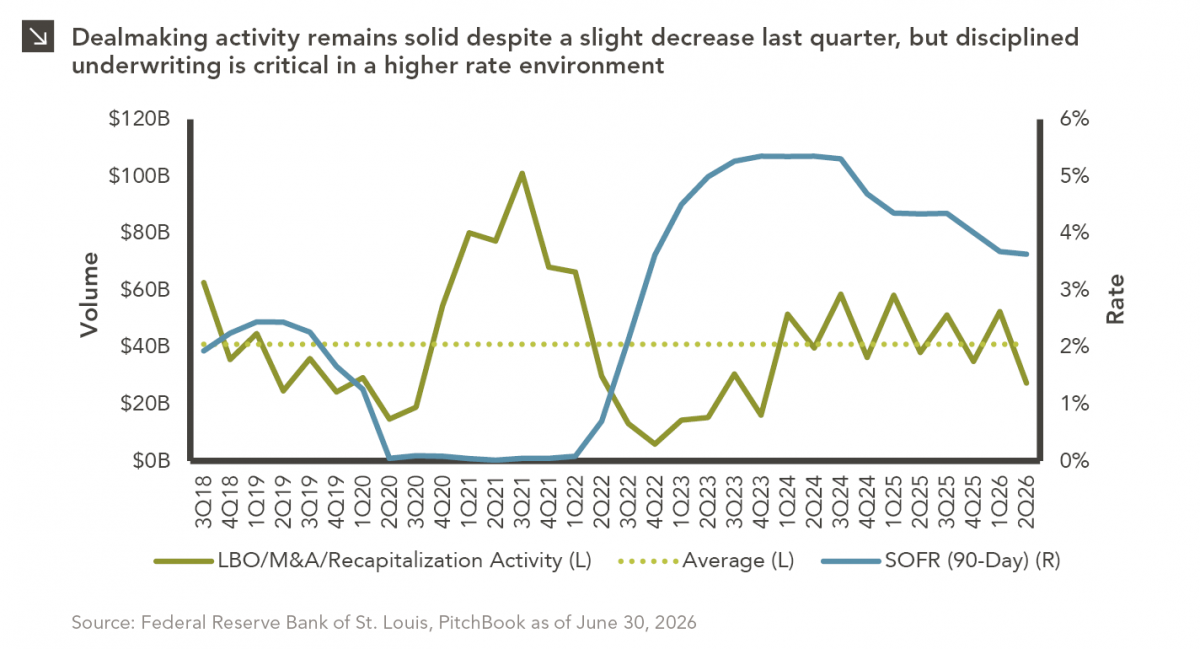
For much of the past several years, the conventional view has been that higher interest rates and stretched valuations would keep buyers and sellers apart within private markets. While elevated base rates did indeed slow transaction activity as the market adjusted to a higher cost of capital, this dynamic did not lead to a structural freeze in dealmaking. To that point, average leveraged buyout, merger, acquisition, and recapitalization volume from the beginning of 2024 through the first half of this year was roughly $44.9 billion, only modestly below the $49.2 billion average exhibited from the third quarter of 2018 through the first quarter of 2022. These data points suggest that buyers and sellers are increasingly finding ways to bridge valuation gaps and transact within a higher cost of capital environment. It is important to note that dealmaking activity declined last quarter due to renewed uncertainty surrounding trade policy, geopolitical risks, and concerns regarding potential disruptions that artificial intelligence may cause within various industries. However, given that deal activity typically varies meaningfully from quarter to quarter, this decline could simply be a function of normal cyclicality rather than evidence of a coming slowdown.
For investors, the current environment presents both opportunities and risks. For instance, elevated base rates continue to support attractive gross yields for direct lenders, while higher debt-service burdens place greater pressure on borrowers and limit the ability of fund managers to financially engineer returns. As a result, underwriting discipline, downside protection, and operational value creation are likely to become increasingly important drivers of investment performance, particularly relative to the low-rate environment during which inexpensive leverage and multiple expansion played a more significant role in generating returns. Going forward, disciplined fund selection will be critical for investors, with manager performance dispersion potentially widening across both the private equity and private credit spaces.
Print PDF
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
10.26.2026
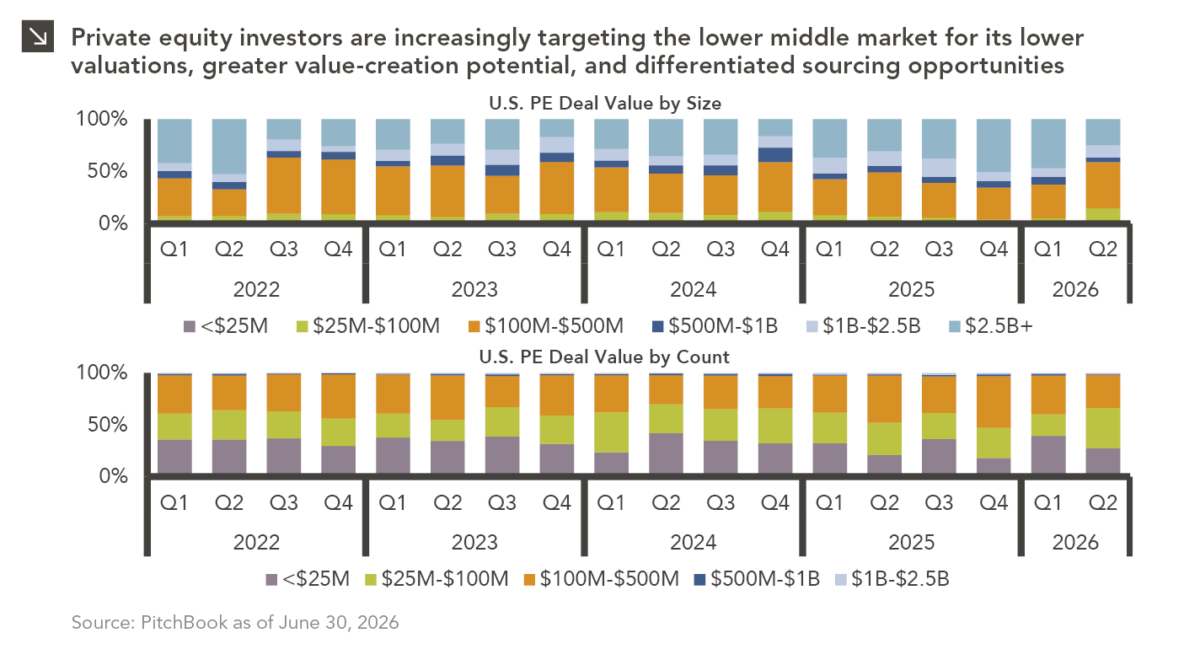
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…
10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…

10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…
10.19.2026
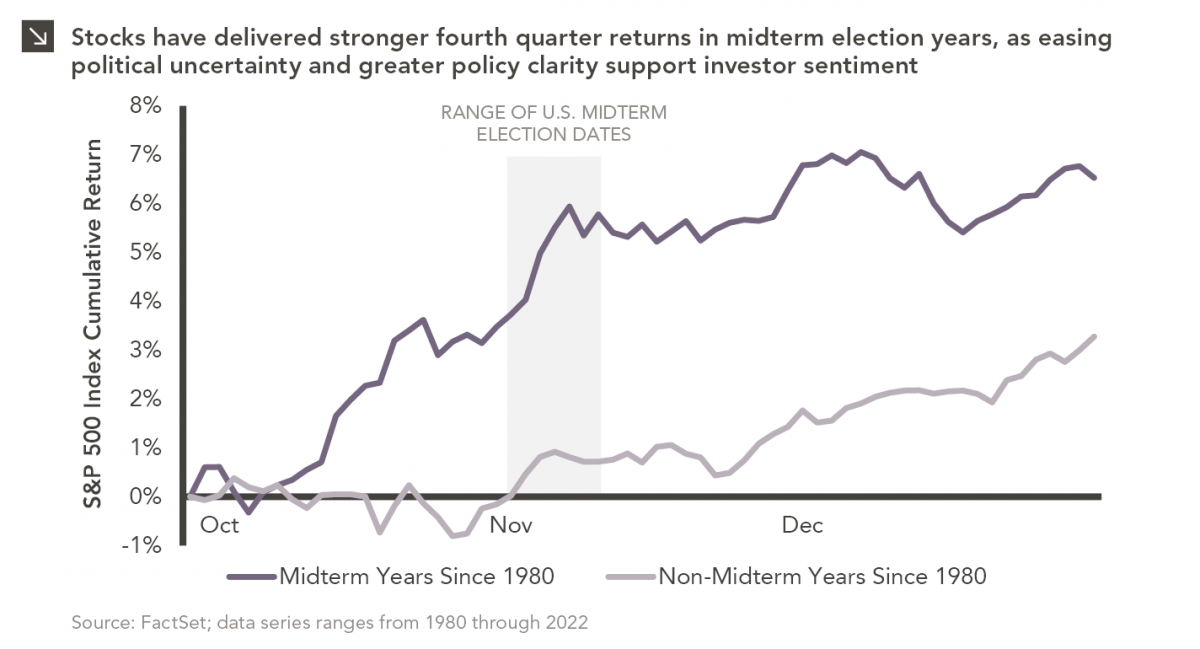
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.12.2026
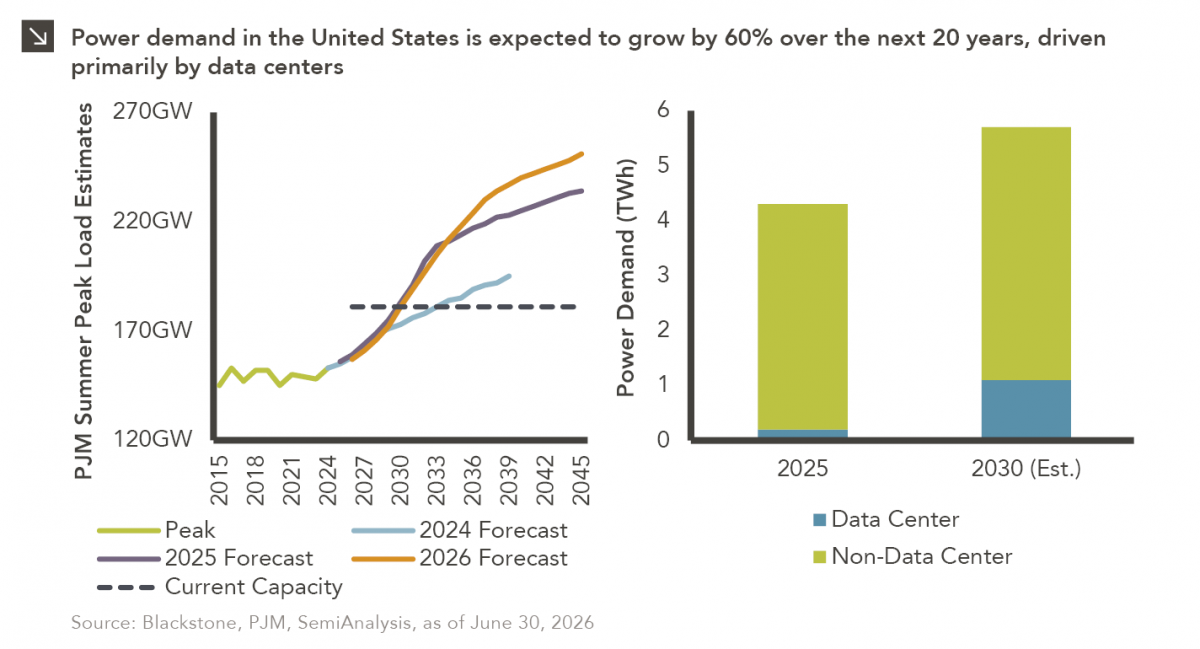
This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
10.05.2026
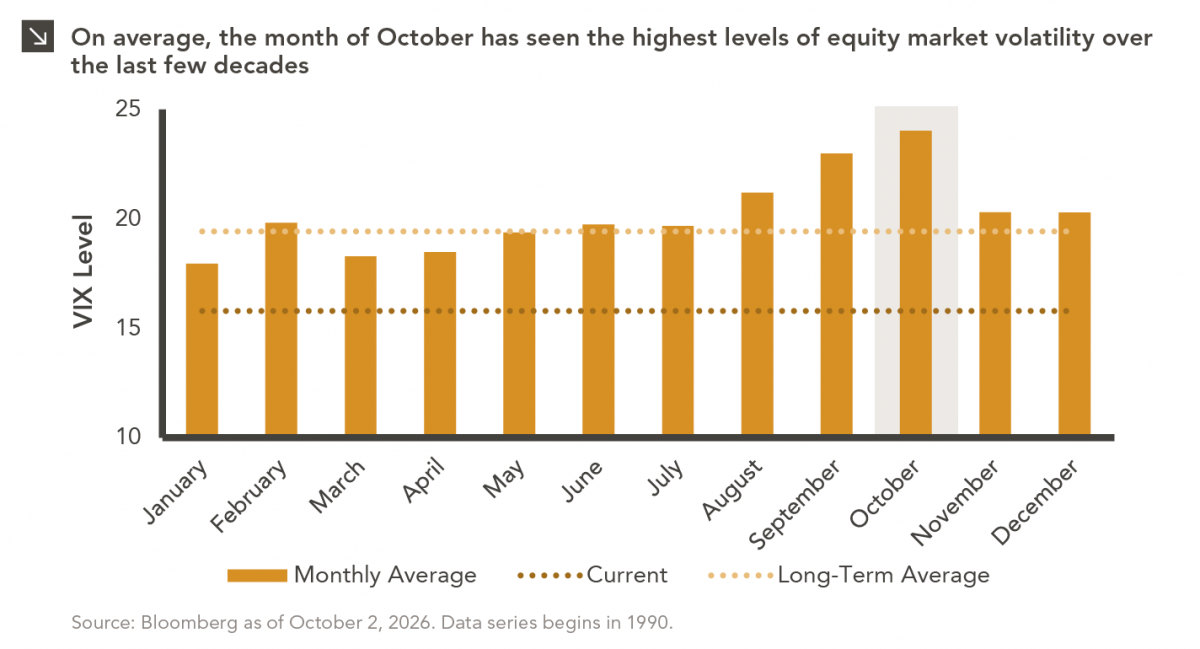
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >