11.09.2026
C’s Get Degrees (of Pain)
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…


With the COVID vaccine’s worldwide distribution and adoption starting last week, many investors are aiming to project an inflation outlook driven by the return of furloughed workers and impending economic recovery and adjust portfolios with inflation protection in mind.
In this newsletter, we examine how key asset classes in institutional portfolios behave in rising or declining inflation environments, and ultimately determine the best asset classes that serve as inflation hedges while also providing strong total return and efficiency ratios. In particular, we investigate if TIPS (Treasury Inflation-Protected Securities) offer superior inflation protection compared to other common portfolio constituents.
Read > Can TIPS Be an Effective Inflation Hedge for Portfolios?
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

11.09.2026
The U.S. distressed debt market is showing increasingly pronounced signs of stress. As of this writing, option-adjusted spreads on CCC-rated…

10.26.2026
Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

10.08.2026
This video is a recording of a live webinar held October 22 by Marquette’s research team analyzing the third quarter…
10.22.2026
Anyone who has run a marathon knows the last six miles are brutal — no matter how well the first…

10.19.2026
Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…
10.05.2026
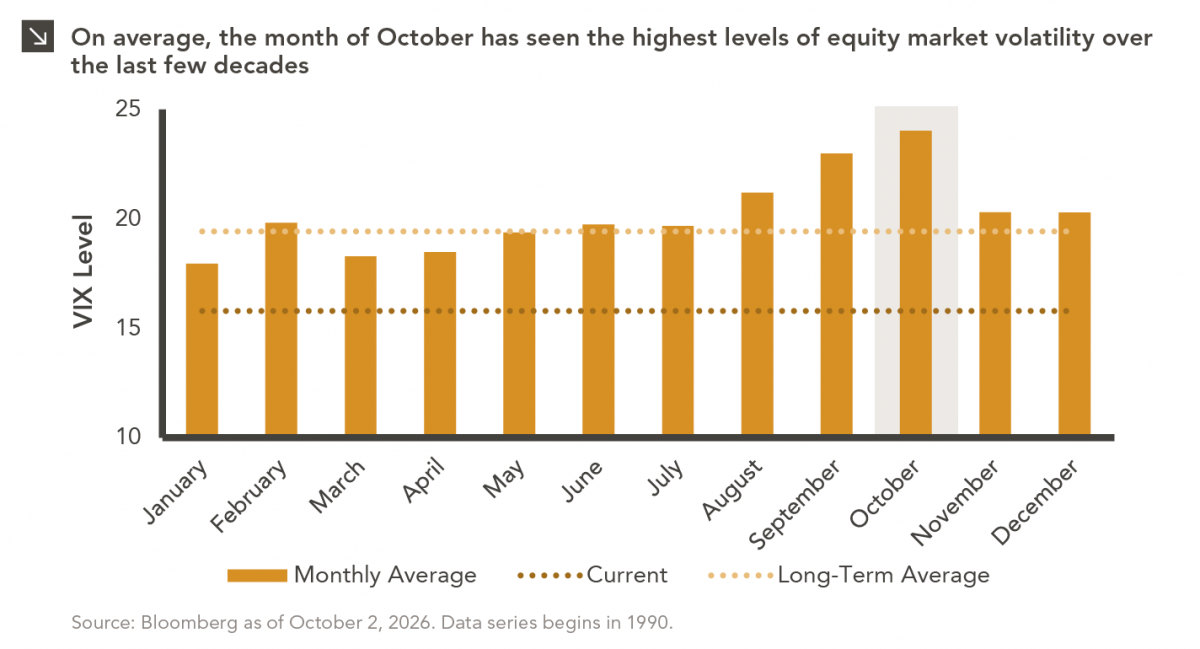
For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >