09.14.2026
No More Free Lunch?
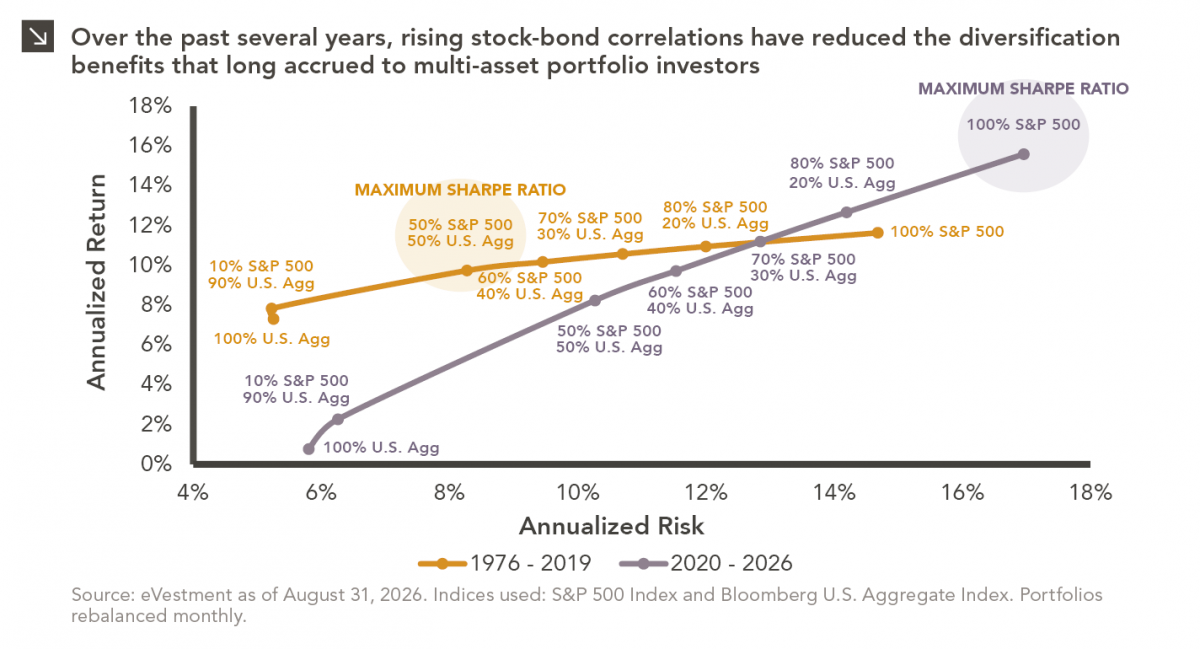
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…


Bitcoin has been under pressure over the past month while Ethereum has held up relatively well, resulting in a large discrepancy in returns between the two largest cryptocurrencies. After a surge in prices from late 2020 through early 2021, a number of factors have weighed on Bitcoin more recently. China reiterated its restrictions on cryptocurrencies and proposed punishments for companies involved in mining Bitcoin in the Inner Mongolia region. Mining rigs have a large energy footprint and have since been banned in order to lower China’s overall energy consumption. China accounts for more than 65% of the world’s total Bitcoin mining due to its cheap energy costs. Elon Musk, a prominent voice in the crypto space, also announced that Tesla would no longer accept Bitcoin as a form of payment due to environmental concerns.
Ethereum also dropped in May, but is still up 83% since March, a stark difference from the -19.8% return of Bitcoin. Ethereum has benefited from increased interest in the underlying technology. Decentralized finance focuses on using Ethereum-enabled smart contracts to optimize transactions. The rise of non-fungible tokens or NFTs has also contributed to Ethereum’s gains. NFTs are digital assets, secured by the Ethereum blockchain, that represent unique ownership of virtual items like art and sports memorabilia. NFT trading volumes in the first quarter of 2021 were up 15X quarter-over-quarter.¹
Cryptoassets are an emerging asset class and this level of volatility should be expected. We recommend interested investors remain diligent and only pursue investments that are appropriate for their risk tolerances.
Print PDF > Volatility in Crypto
¹CoinDesk, Nonfungible.com
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…

09.08.2026
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…

08.31.2026
Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears…

08.24.2026
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…

08.17.2026
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…

08.10.2026
After reaching nearly ¥164 per dollar, its weakest level in roughly four decades, the yen had become a source of…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >