09.14.2026
No More Free Lunch?
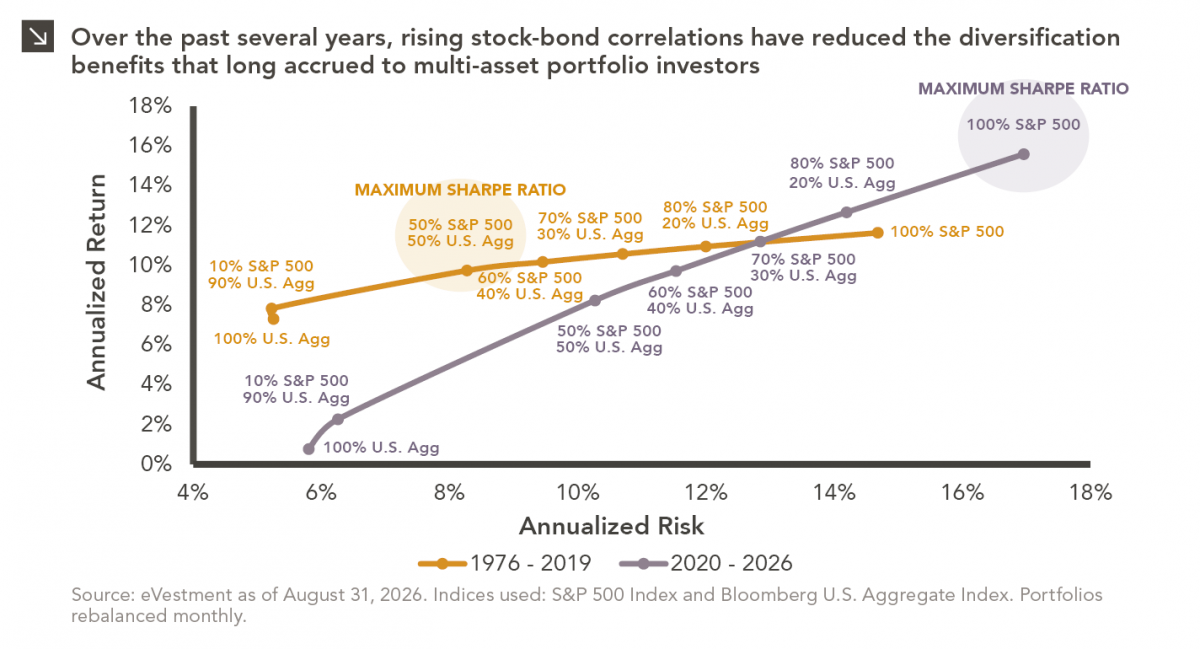
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…


Given the positive news on the weakness of the Omicron variant and its susceptibility to at least some of the COVID-19 vaccines, credit spreads have generally retraced their widening since the first Omicron case in South Africa was reported to the World Health Organization on November 24th, 2021. Our chart this week compares high-yield spreads against two averages using the Bloomberg High Yield index. The lower dotted line is the average spread for the year-to-date period, with current spreads sitting just above of this figure. The higher dotted line is the since-inception average spread (excluding the extreme periods of 2008 and 2009), with today’s spreads still generally extremely tight compared to this long-term average despite the recent Omicron scare. While we assess only U.S. high yield corporate spreads, these are generally representative for investment grade bonds, bank loans, and emerging markets debt as well.
Omicron has quickly spread to at least 57 countries around the world thus far, but spreads tightened across the board last week as President Biden chose to institute stricter COVID-19 testing requirements for travelers entering the U.S. from abroad instead of implementing more lockdowns and broad mask mandates. Additionally, Moderna and Pfizer have been mobilizing to update their vaccines against the Omicron variant. However, the tail end of last week brought with it some widening pressure as Europe tightened its COVID-19 restrictions and the Consumer Price Index saw a 6.8% increase for the month of November on a year-over-year basis, topping the previous month’s 6.2%. This figure raised some concern that the Federal Reserve may accelerate its tapering and rate hike schedule.
Last week, the fully vaccinated rate remained at 60% for the U.S. and rose one point to 45% for the world. With still a long runway to go before herd immunity levels of 80% are reached, and since issuers remain risk-averse as evidenced by benign fundamentals ranging from generally low leverage to use of loan and bond issuance proceeds directed towards refinancings rather than LBOs, we may expect spreads to potentially tighten further. It is worth noting that this tightening may not be without potential dislocations along the way. As of this writing, spreads are very near all-time tights. Marquette will continue to monitor fixed income valuations, fundamentals, and technicals as we progress through the recovery from the pandemic.
Print PDF > Credit Spreads Snap Back from Initial Omicron Surge
The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
09.14.2026
There are many great things about working at Marquette Associates, but “Free Lunch Tuesday” is right at the top of…

09.08.2026
Over the last several years, emerging market debt (EMD) has faced several headwinds, with rising yields across other fixed income…

08.31.2026
Private equity has always had a few portfolio companies that refused to leave the party. Today, however, the industry appears…

08.24.2026
The global bond market is facing renewed pressure as investors demand higher yields to hold long-dated government debt, pushing borrowing…

08.17.2026
As a college football player struggling to put on mass, the “supersizing” deal at McDonald’s was hard to beat. For…

08.10.2026
After reaching nearly ¥164 per dollar, its weakest level in roughly four decades, the yen had become a source of…
Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.
We respect your privacy. We will never share or sell your information.
If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.
Contact Us >