Tech Sector Bubble?

Our Chart of the Week examines the concentration in market cap over time among the five largest stocks in the S&P 500 relative to the total market cap of the index. With growth outperforming value in the current market cycle, it’s not surprising to see the largest stocks by market cap today populated entirely by growth stocks. The strong performance among FAANG stocks (Facebook, Apple, Amazon, Netflix, and Google/Alphabet) have propelled the weighting of these securities within market cap weighted indices over recent years and caused market participants to question how long this historic run can last and if we are currently in a technology sector bubble. With names such as Facebook and Netflix pulling back earlier in the year and Apple hitting a $1 trillion market cap milestone last week, fears of a technology bubble have only continued.

As of June 2018, the largest five stocks in the S&P 500 occupied 15.9% of the total market cap of the index. This concentration is high relative to the current market cycle, but it is important to note that we are still below the March 2000 high of 18.5%. Additionally, the largest five stocks in the S&P 500 have occupied greater than 20% of the total S&P 500 market cap in prior periods such as during the 1970’s.

The technology sector does trade at a premium to the broader market today. However, the sector generates high return on equity, strong earnings growth, and multiple expansion is not as excessive as during the dot-com peak. While the recent rise in technology stock weighting as a percentage of total market cap warrants monitoring, today’s concentration is not without precedence.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Is it Value’s Turn?

This week we examine factor performance from the Russell 1000, with a focus on the dynamic between growth and value stocks. For the month of July, value finally pulled ahead of growth as a contributor to performance. This is a shift from recent behavior as growth leads on a trailing 7-year basis. Typically, growth and value have operated in a cyclical relationship so value’s shift from detractor in 2Q to a positive contributor in July could signal a reversal in relative performance between the two styles.

Financials, particularly banks, did well in July by posting strong earnings; these tend to be value stocks and contributed to the relative outperformance. While tech has been a very strong performer year to date, some of the FANG stocks, namely Facebook and Netflix, hit potholes in July. Facebook encountered more trust and brand issues surrounding privacy and Netflix battled disappointing subscriber growth. These specific company pullbacks likely hurt the growth factor.

Growth has outperformed value since 2011 and the rolling 10-year outperformance is at a high point, now bumping up against two standard deviations from its long-term average. This paired with value’s recent edge above growth may indicate that growth’s outperformance versus value could be coming to an end.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

The Impact of Puerto Rico on Hedge Funds

With the first half of 2018 behind us, our chart of the week touches on one of the more profitable positions for distressed credit hedge funds. Funds invested in Puerto Rican debt due to its misunderstood fiscal story, bondholder protections and a better credit situation than many stressed sovereigns. Following the devastation left from Hurricane Maria and President Trump’s comments on wiping out Puerto Rico’s debt, bondholders saw prices plunge in the latter half of 2017. That late year sell-off led to those bond positions contributing the most significant losses to many distressed strategies.

Thus far, 2018 has seen a recovery of Puerto Rican bond prices for hedge funds. The chart above highlights Puerto Rico General Obligation 2035 bonds. Many hedge funds believe the bonds were oversold last year following the hurricane, and recent revisions to Puerto Rico’s fiscal plan now projects greater primary surpluses, which has caused bond prices to rise. Also, Puerto Rico’s recovery from Hurricane Maria is now making progress which has also given comfort to bondholders. Negotiations for other Puerto Rican bonds will continue throughout 2018, with managers expecting to see more volatility during the remainder of the year.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
Do Rising Rates Mean Lower Returns for EM Equities?

Rising rate environments are typically thought to put downward pressure on equity returns. Specifically for emerging market (“EM”) equities, the common perception is that higher interest rates in the United States will drive EM returns lower and investors away from EM securities. However, in looking at the annualized returns of the MSCI Emerging Markets Index over historical periods of rising rates, this may not be the case.

This week’s chart of the week shows the annualized return of the MSCI Emerging Markets Index in rising rate environments and the Fed Funds Rate at the start and end of those periods. Only one of the time periods — January 1994 to February 1995 — was negative, and the average return for the time periods examined is 14%. In the most recent period — from December 2015 through June 2018 — the MSCI Emerging Markets Index has returned over 11% annually. Contrary to common belief, in periods when rates are rising, EM equities seem to perform well.

What explains this performance? For one, economic fundamentals for EM economies have been strong. The annual real growth rate of GDP for developed markets has averaged 1.9% over the past 5 years, while the same measure for emerging markets has averaged 4.9%. The more recent poor EM performance is mostly due to an appreciating dollar, which makes exports from EM countries cheaper to purchase in the U.S. Longer term, however, the data suggests that EM returns could be positive as rates climb higher in the U.S.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.
Goodbye Telecommunications Services Sector and Hello Communications Services Sector!

On November 15, 2017, S&P Dow Jones Indices, a leading provider of financial market indices, and MSCI Inc., a leading provider of research-based indices and analytics, conducted their annual review of the Global Industry Classification Standard (GICS). As a result, the pair decided to broaden and rename the Telecommunications Services sector to the Communications Services sector. The thought process is that over the past several years consumers and businesses have fundamentally transformed the way in which they communicate and access content.

In some ways, this trend started when Comcast, a cable company, announced its intention to purchase a stake of NBC Universal, a television network and content provider, in 2007. The latest example of the convergence between communications and media is the on-going asset fight between Fox, Comcast, and Disney for Sky PLC, a European satellite broadcaster. Moving away from traditional communications and media companies, firms like Alphabet through its Google search engine and YouTube, Facebook through its ever-expanding social media platform, and Netflix through its direct-to-consumer streaming content, have changed the way the world communicates and accesses content. The lines have officially blurred and S&P along with MSCI decided to take action.

What impact will this have on investors?

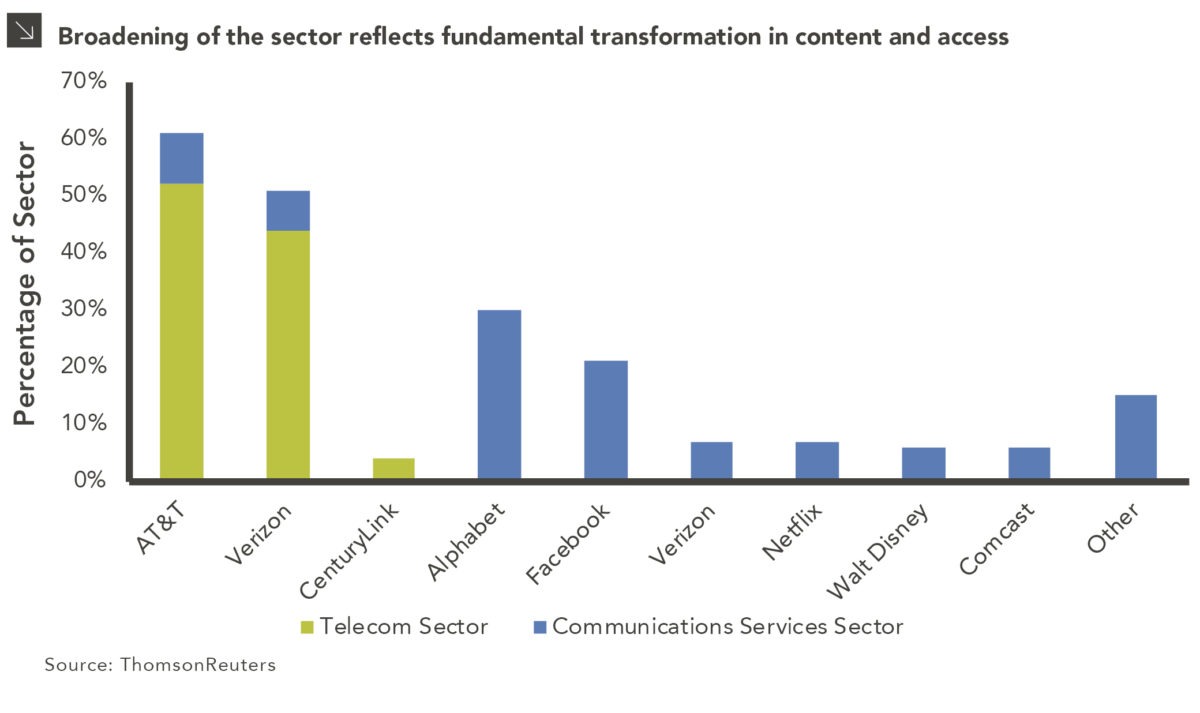
On September 21, 2018, the Telecommunications Services sector, the smallest sector at a 2% weight in the S&P 500 will quintuple in size to become the fourth largest sector in the index at the expense of the Information Technology and Consumer Discretionary sectors. This change is much larger than GICS’s creation of the Real Estate sector in 2016, which affected approximately 3% of the index’s market cap. Sleepy firms like AT&T, Verizon and CenturyLink will be grouped in the same sector as Alphabet, Facebook, and Netflix, just to name a few. Most notably, a sector classified as 100% value will be primarily growth-oriented.

The composition change is shown in the above chart; the formerly dominant names of AT&T, Verizon, and CenturyLink of the Telecom sector (shown in green) will now occupy a much smaller percentage of the new Communications Services sector, as shown by the considerably smaller blue boxes in the graph.

Luckily, most investment managers select stocks based on their investment merits and not their GICS sector classification. An investment manager that owns Alphabet (Google), which is currently classified as an Information Technology stock, on September 21st will continue to hold it on September 22nd. Much like the creation of the Real Estate sector in 2016, there is no action needed on the part of investors. We will continue to monitor new developments as S&P and MSCI finalize the change over the coming months.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Is Emerging Markets Debt Oversold?

Almost halfway through the year, emerging markets debt (“EMD”) returns are negative for the year, due to a variety of economic and political events. The most commonly cited explanations include the following:

  • The ongoing Fed rate hikes, including the first two this year in March and June, and also those expected in September and December as well as two more next year;
  • As discussed in our chart last week, the European Central Bank (“ECB”) will end its quantitative easing program in October;
  • The ongoing protectionist sentiment among the U.S., China and other countries that may stifle global commerce and potentially, global growth;
  • Italy’s two populist parties’ inability to initially form a coalition, which stoked fears of Italy’s exit from the EU — but they have since formed a coalition and selected a prime minister;
  • A truckers’ strike in Brazil that paralyzed many of the country’s major roads;
  • Turkish President Erdogan’s claim that higher interest rates cause inflation, and finally;
  • A run on the Argentine peso that exacerbated further downward pressure on the currency, resulting in a $50 billion emergency IMF loan.

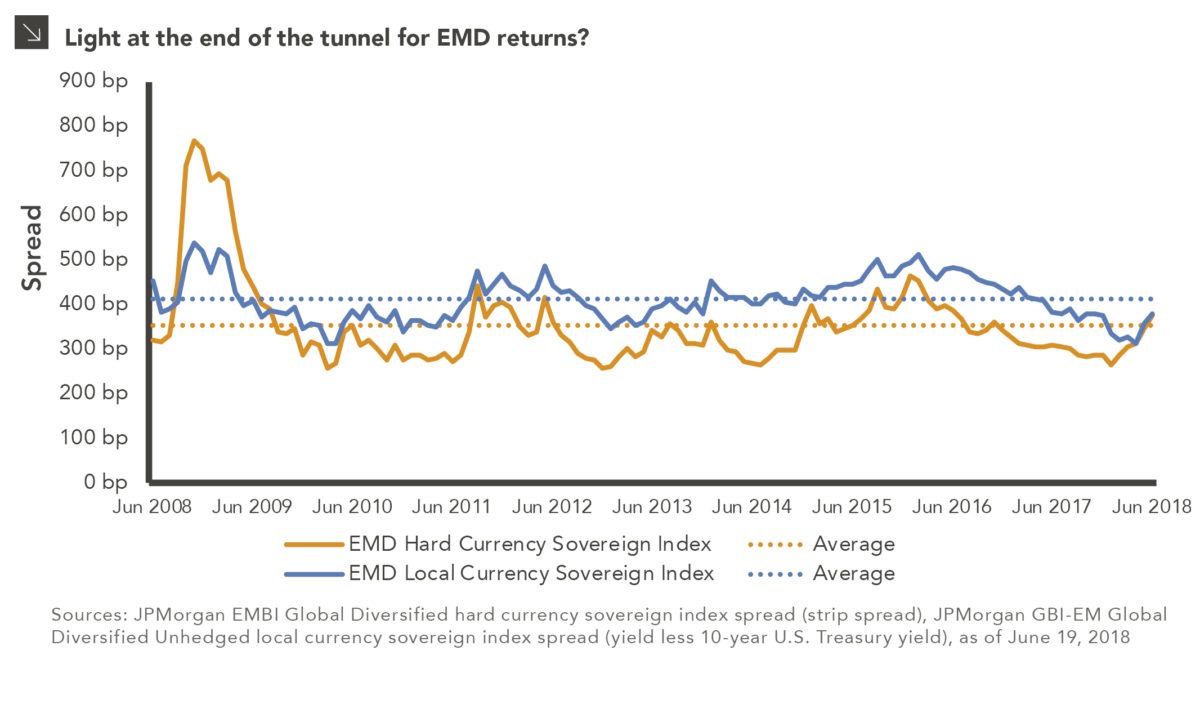
The chart above illustrates how spreads have risen, which has led to higher yields and thus losses for EMD strategies so far in 2018. More specifically, the chart shows the spreads for the hard currency sovereign and local currency sovereign indices versus their averages. The hard currency sovereign index tracks bonds issued by emerging markets countries denominated in U.S. dollars or euros. The local currency sovereign index tracks bonds issued by emerging markets countries denominated in the issuer’s local currency, such as the Brazilian real or Malaysian ringgit.

Looking ahead, it could be argued that tightening by both the Fed and the ECB may slow global growth, raise interest rates, and strengthen currencies in both the U.S. and Europe, none of which would be favorable for EMD returns. However, at this point these moves may already be priced into current yields, and the worst of their impact on returns has already been felt. If so, what’s left are “idiosyncratic” headlines, which should theoretically have less of an impact on future returns.

Ultimately, despite the EMD market’s sensitivity to headlines, EM fundamentals remain strong. Leverage among issuers remains low on an absolute basis and is lower than developed market issuers. GDP growth remains high and is higher than developed market issuers. Furthermore, current account balances and inflation rates are generally improving. These strong fundamentals may suggest an impending reversal in the second half of the year for EMD returns.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

The ECB Ends QE

Late last week the European Central bank (ECB) announced an end to its quantitative easing (QE) program. Over the last three years the ECB purchased 2.4 trillion euros in bonds to help boost the region’s economy. In October of this year the monthly bond purchases will be halved to 15B euro and move to zero at the end of the year. The ECB balanced this hawkish move with a commitment to keep interest rates at current levels at least through the summer of 2019. In addition, the ECB will continue to reinvest its proceeds from current bond holdings for “an extended period of time.”

The ECB’s actions signal confidence in the economic recovery and provide a timeline for markets to adjust. Despite the end of QE, policies remain accommodative and low borrowing costs should persist into the near future. The central bank remains ready to step in should the region’s economy need further support, but has taken the first steps towards a more normal monetary policy.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Do Private Markets Offer More Attractive Opportunities?

Across the private equity industry, valuations have continued to trend higher over the past few years with U.S. buyout valuation multiples reaching 11.8x EV/EBITDA in 2017. These elevated multiples have been supported by an environment of strong economic growth, favorable private market fundamentals, and significant levels of capital available to finance transactions. While buyout multiples may appear elevated relative to their historical averages, EV/EBITDA multiples are still 30% below the average valuation for U.S. small cap companies in the public market. Throughout this growth cycle private valuations have not risen as significantly as they have in the public markets. This valuation discount has provided value-sensitive investors a relative value trade as they seek to rebalance their portfolios.

Going forward, the significant reduction in U.S. corporate taxes that went into effect in 2018 will most directly benefit small U.S. companies as nearly all of their revenues are generated domestically. Throughout the first five months of 2018 we have seen strong growth from both public and private companies, which has led to an acceleration of earnings and cash flow generated by these companies. With less taxes to pay for every dollar of EBITDA, the growth of earnings has made private multiples even more attractive to institutional investors, and will likely drive even greater interest in private equity allocations.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

MSCI Dips Toe into China A-share Pool

On May 31, 2018 MSCI decided to add 226 China large-cap A shares to the MSCI Emerging Markets (EM) Index. What is an A share? They are shares of Chinese companies that trade on local Chinese stock exchanges. Historically, foreign investors have had limited — if not zero — access to these markets. Three years ago, China launched its Stock Connect program, improving the accessibility to A shares and prompting their inclusion in the broad EM index. If A shares were just recently added, what constitutes the current 30.5% exposure to China? The China portion of the index is mainly comprised of the following:

  • H Shares – Chinese companies incorporated in China and listed on the Hong Kong stock exchange.
  • Red and P Chip – Chinese companies incorporated outside of China and listed on the Hong Kong stock exchange.
  • Overseas – Chinese companies listed on an overseas exchange, for example Alibaba which is listed in the NYSE.

By September 2018 China A-shares will constitute 0.8% of the index. This exposure represents a 5% inclusion rate of the A Share market and is tiny compared to the 16.2% exposure if MSCI used a 100% inclusion rate. While currently small, investors should expect A shares to become a larger portion of the index over the coming years, increasing the EM opportunity set.

Print PDF


The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

And the Winner is… Commodities?

Through the end of May, 2018 has featured volatility and uncertainty across financial markets leading to some disappointing performance. Fixed income investments struggled as the yield curve rose with both core bonds and high yield slightly negative year to date. Broad U.S. equities are only up 2.5% after a rocky start to the year while international equities are negative following an exceptionally strong 2017. All this, along with fears about inflation, led to a surprising result: commodities are the best performing asset class in 2018. Despite this, the asset class is still by far the worst performer over both a 5 and 10-year period.

This week’s chart shows how difficult it is to time the market and why maintaining a consistently well-diversified portfolio is so important. The argument could be made that commodities were due to outperform (i.e. buy low and sell high) given their recent struggles. However, in 2014 commodities were down over 33%; investors hoping for a nice rebound the following year were in for a shock as commodities fell another 32.9% in 2015. On the flip side, last year emerging market (EM) equities was the top performing asset class, but those looking to chase this return now find themselves in the worst performing asset class YTD. There is little correlation between returns year to year and therefore we encourage clients to stick with long term allocations and avoid portfolio decisions based solely on recent returns.

Print PDF

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.