The Changing Composition of Consumption

While traditional “active” consumer spending undoubtedly makes up a large percentage of G.D.P., increased spending on health care (through Medicare and Medicaid) over time has likely overstated this popular statistic.

It is common to hear that consumption contributes 65 to 70% of total GDP, hence its importance to economic growth. More insightful, though, is to understand the underlying components of consumption and how accurately it truly reflects consumption on behalf of consumers. To do this, we use the Personal Consumption Expenditures (PCE) data which is the source of that 65 – 70% number. Critically, one must understand the elements of PCE data: in addition to the traditional consumption items (clothing, electronics, food and drink, housing, transportation, etc.), non-profit spending and expenditures made “on behalf” of consumers, such as Medicare and Medicaid, are also included. While traditional “active” consumer spending undoubtedly makes up a large percentage of G.D.P., increased spending on health care (through Medicare and Medicaid) over time has likely overstated this popular statistic.

Indeed, this is reflected in the historical data: in 1959, over 73% of consumer spending was spent in four main traditional consumer spending categories: housing, transportation, food and drink, and personal care/clothing. Over the last 50 years, the percentage spent on these four categories decreased to just over 50% of all spending in 2011. The biggest reason for the change is increased spending on healthcare – it accounted for less than 6% of overall PCE in 1959, while today it accounts for nearly 20%. This massive increase has certainly decreased the percentage of total PCE that is attributable to traditional, active consumer spending choices.

PCE is not a great indicator of average consumer expenditures, because the “spending” on Medicare and Medicaid is not distributed evenly among consumers, nor is it an “elected” expenditure in that consumers freely choose to spend or not spend on the two items. So if consumers aren’t actually spending 20% of their expenditures on healthcare, what are they buying? To get a sense for what consumers are actually spending their money on, the Bureau of Labor Statistics performs a survey called the Consumer Expenditure Survey that attempts to collect data on the spending habits of American consumers. Based on these results, healthcare accounts for less than 7% of annual spending for the average consumer.

Category % of Avg. Annual Expenditures
Food 12.7%
Housing 34.4%
Apparel and services 3.5%
Transportation 16.0%
Healthcare 6.6%
Entertainment 5.2%
Cash contributions 3.4%
Personal insurance and pensions 11.2%
Other 7.0%


Delinquency Rates

This week’s Chart of the Week examines four types of loans and their delinquency rates over the past twenty years. A loan is considered to be delinquent if it is past due by thirty or more days. The delinquency rate is the percentage of loans that are considered to be delinquent.

This week’s Chart of the Week examines four types of loans and their delinquency rates over the past twenty years. A loan is considered to be delinquent if it is past due by thirty or more days. The delinquency rate is the percentage of loans that are considered to be delinquent.

The chart shows all four delinquency rates are on a noticeable decline from their peaks as the economy has made some improvements over the last two years. In fact, three of the four rates have fallen below their respective twenty year averages. Business loan delinquency rates have followed the pattern of the business cycle therefore it is not surprising to see the rates go down as we emerge from recession. Consumer and credit card delinquency rate declines are due in large part to commercial banks writing off bad debt, a tightening of lending standards, and consumers deleveraging. More individuals are no longer paying their mortgages, thus freeing up money to pay off other debts.

The delinquency rate for single family mortgages remains considerably higher than its twenty year average. Many homes are now valued significantly lower than their loan balances. This fact, coupled with a challenging job market, has contributed to the high delinquency rate. The potential that these delinquent properties will eventually end up in foreclosure make it an even more challenging environment for residential real estate. Foreclosures will increase the supply in an already oversupplied market and exacerbate the downward pressure on home prices. As discussed in our 2012 Market Preview, this environment has led to a boom for owners of rental units: the apartment sector has benefitted because individuals are now turning to rentals rather than purchasing homes.

Correlation Doesn’t Tell the Whole Story

Over the past five years, as globalization has become more pronounced and economies more intertwined, correlations have certainly increased to all time high levels. But since correlation does not capture magnitude of returns, investors should continue to utilize an asset allocation model that takes potential risk and return into account.

This week’s Chart of the Week covers increased correlations among asset classes. Correlation is a statistical measure showing how two variables move in relation to each other. It can range anywhere from -1 to1, and refers only to the direction of changes. Perfect negative correlation (-1), implies that two items move in completely opposite directions and perfect positive correlation (+1), implies that two items move in lock-step. The chart above shows the five-year correlations between the S&P 500 and a broad set of sample asset classes. As evident, all risk-assets have had a very high positive correlation to the S&P 500 over the past five years. Referring to the chart, aside from the three Treasury indices, no other asset class has a correlation less than .90, which is extremely high.

However, correlation only tells part of the story: just because two asset classes have high correlation does not mean that their returns will end up being the same. In fact, this will most likely never be the case. For example, over the time-frame captured above, despite very high correlations, emerging markets, the S&P 500, and the REIT index have annualized returns of 2.8%, -.56% and -3.48% respectively. Over the past five years, as globalization has become more pronounced and economies more intertwined, correlations have certainly increased to all time high levels. But since correlation does not capture magnitude of returns, investors should continue to utilize an asset allocation model that takes potential risk and return into account.

Good News From the ISM Index?

On Tuesday, the ISM factory index for December was released, with last month’s level reaching 53.9, the highest since April. Perhaps more importantly, this was above expectations of 53.5, thus providing an unexpected surprise to the upside to kick off 2012.

On Tuesday, the ISM factory index for December was released, with last month’s level reaching 53.9, the highest since April. Perhaps more importantly, this was above expectations of 53.5, thus providing an unexpected surprise to the upside to kick off 2012. Stocks and commodities rose in reaction to the better than expected data, and while the economy is far from back to full health, this was welcome news to kick off the 2012 year in the financial markets.

Unemployment in Context

In the most recent November employment survey, the unemployment rate fell significantly further than expected, to 8.6%. This seeming improvement, however, masks continued weakness in economic growth. Calls for a U.S. recession now seem premature, but, so too do calls for a return to robust growth.

In the most recent November employment survey, the unemployment rate fell significantly further than expected, to 8.6%. This seeming improvement, however, masks continued weakness in economic growth. Calls for a U.S. recession now seem premature, but, so too do calls for a return to robust growth. In November, the economy added an estimated 120,000 jobs. This is roughly the number of jobs that must be added each month to simply keep pace with population growth. Thus, the majority of the improvement in the unemployment rate came from a decline in labor force participation, shown in the Labor Force Participation chart.

The labor force participation rate measures the number of people who are employed or seeking employment as a percentage of the total population. Notably, the participation rate has increased over time as more women have joined the workforce. Currently, the labor participation is at the same level as during the double dip recession of the 1980’s. Improvements in the unemployment rate due to a decline in the participation rate imply little relative improvement in a country’s economic condition. Ultimately, either participation stays low, which permanently lowers output potential, or participation increases as the economy improves, which increases the unemployment rate.

Due to the long duration of unemployment after the most recent recession, more workers may continue to drop out of the labor force. This makes the unemployment rate a less relevant measure of the output gap between the economy’s current and potential output. Ideally, for robust growth to take hold, the number of jobs created would have to be in excess of those needed to keep up with population growth. In this scenario, there may or may not be a decrease in the unemployment rate, depending on how the participation rate changes. However, there would be an improvement in the employment to population ratio. This measure, in the Employment to Population Ratio chart, has languished at depressed levels since collapsing during the most recent recession.

Intraday Volatility

This week’s chart depicts the intraday percentage change of the S&P 500 index over the trailing ten years. Several outlying events have been highlighted, however, we will focus on 2011.

This week’s chart depicts the intraday percentage change of the S&P 500 index over the trailing ten years. Several outlying events have been highlighted, however, we will focus on 2011. In the first six months of 2011 (125 trading days), the average intraday percentage change was 1.05%. From July 1, 2011, through December 5, 2011 (109 trading days), the average intraday percentage change was 2.33%. If you were to translate the intraday percentage change into points, the S&P 500 index has traveled 4,717 points to net a year to date return of 1.91%. Given the recent market volatility, it is important to not overreact to short-term market volatility and have your asset allocation guide your decision making process.

Bailout for Italy?

This week’s Chart of the Week deals with the sovereign debt crisis in Europe. It is an update of a Chart of the Week from January, 2011 when yields on Portuguese bonds were trending towards 7% and there was much speculation in the market that Portugal was in need of a bailout package from the EU. Since then, Portugal received a bailout package from the EU and IMF and the fiscal situation in Italy has become the focus of attention in the markets.

This week’s Chart of the Week deals with the sovereign debt crisis in Europe. It is an update of a Chart of the Week from January, 2011 when yields on Portuguese bonds were trending towards 7% and there was much speculation in the market that Portugal was in need of a bailout package from the EU. Since then, Portugal received a bailout package from the EU and IMF and the fiscal situation in Italy has become the focus of attention in the markets. Over the past week or two there has been speculation that Italy will be the next country to require a bailout package. Yields on Italian government bonds have been steadily rising throughout the course of the past year, and in recent weeks the yield on the Italian 10-year bond has been trending towards 7%.

The 7% threshold is significant because Greece, Ireland, and Portugal were all forced to request a bailout package from the EU shortly after yields on their 10-year bonds exceeded 7% (based on a rolling 10-day average). The yield on Greek 10-year bonds broke through the 7% threshold on April 16, 2010, and Greece requested a bailout package on April 23, 2010. The yield on the Irish 10-year bond broke through the 7% threshold on November 15, 2010, and Ireland requested a bailout package on November 21, 2010. The yield on Portuguese 10-year bonds broke through the 7% threshold on January 31, 2011, and Portugal requested a bailout package on April 7, 2011. After the November 30 announcement of a coordinated action by six central banks to provide additional liquidity to financial institutions if necessary, yields on Italian 10-year bonds have backed away from the 7% threshold. Given that Italy has very little debt maturing in the final weeks of 2011, it is likely not in immediate need of a bailout package. However, Italy is still facing major fiscal issues over the near term. It has a high debt to GDP ratio (118% as of 12/31/10), a high unemployment rate (8.2% as of 9/30/11), and a low growth rate (0.8% as of 6/30/11). In addition, Italy has over €320 billion in debt maturing in 2012, and unless the market perceives a material improvement in Italy’s fiscal situation, it will be difficult for the yield on its 10-year bonds to stay below the 7% threshold.

Post-Recession Employment Growth

This week’s chart analyzes job growth after the last four recessions by examining employment levels 60 months after the start of each recession. The data focuses on private employment, not government employment. Ellipses on the chart represent the end point of each recession, whereas squares represent the beginning of job growth.

This week’s chart analyzes job growth after the last four recessions by examining employment levels 60 months after the start of each recession. The data focuses on private employment, not government employment. Ellipses on the chart represent the end point of each recession, whereas squares represent the beginning of job growth.

The 1982 recession lasted seventeen months. After its cessation, it took only nine months for employee growth to emerge. While the 1990 recession lasted nine months, it endured an additional 26 until job growth began. The length of the 2001 recession was again brief lasting only nine months, but it withstood 30 months until growth mode. The most recent recession began in December of 2007 and lasted nineteen months. At 27 months and counting, we are still waiting for job growth to commence.

Five years after the ’82, ’90, and the ’01 recessions, private sector job levels were well ahead of their pre-recessions levels. Unfortunately, it is difficult to paint a happy picture on the current status of employment: while there has been progress in recovering lost jobs, substantial headwinds remain, as 6.3 million more jobs are needed to return to pre-recession levels.

Recessions and Income Declines

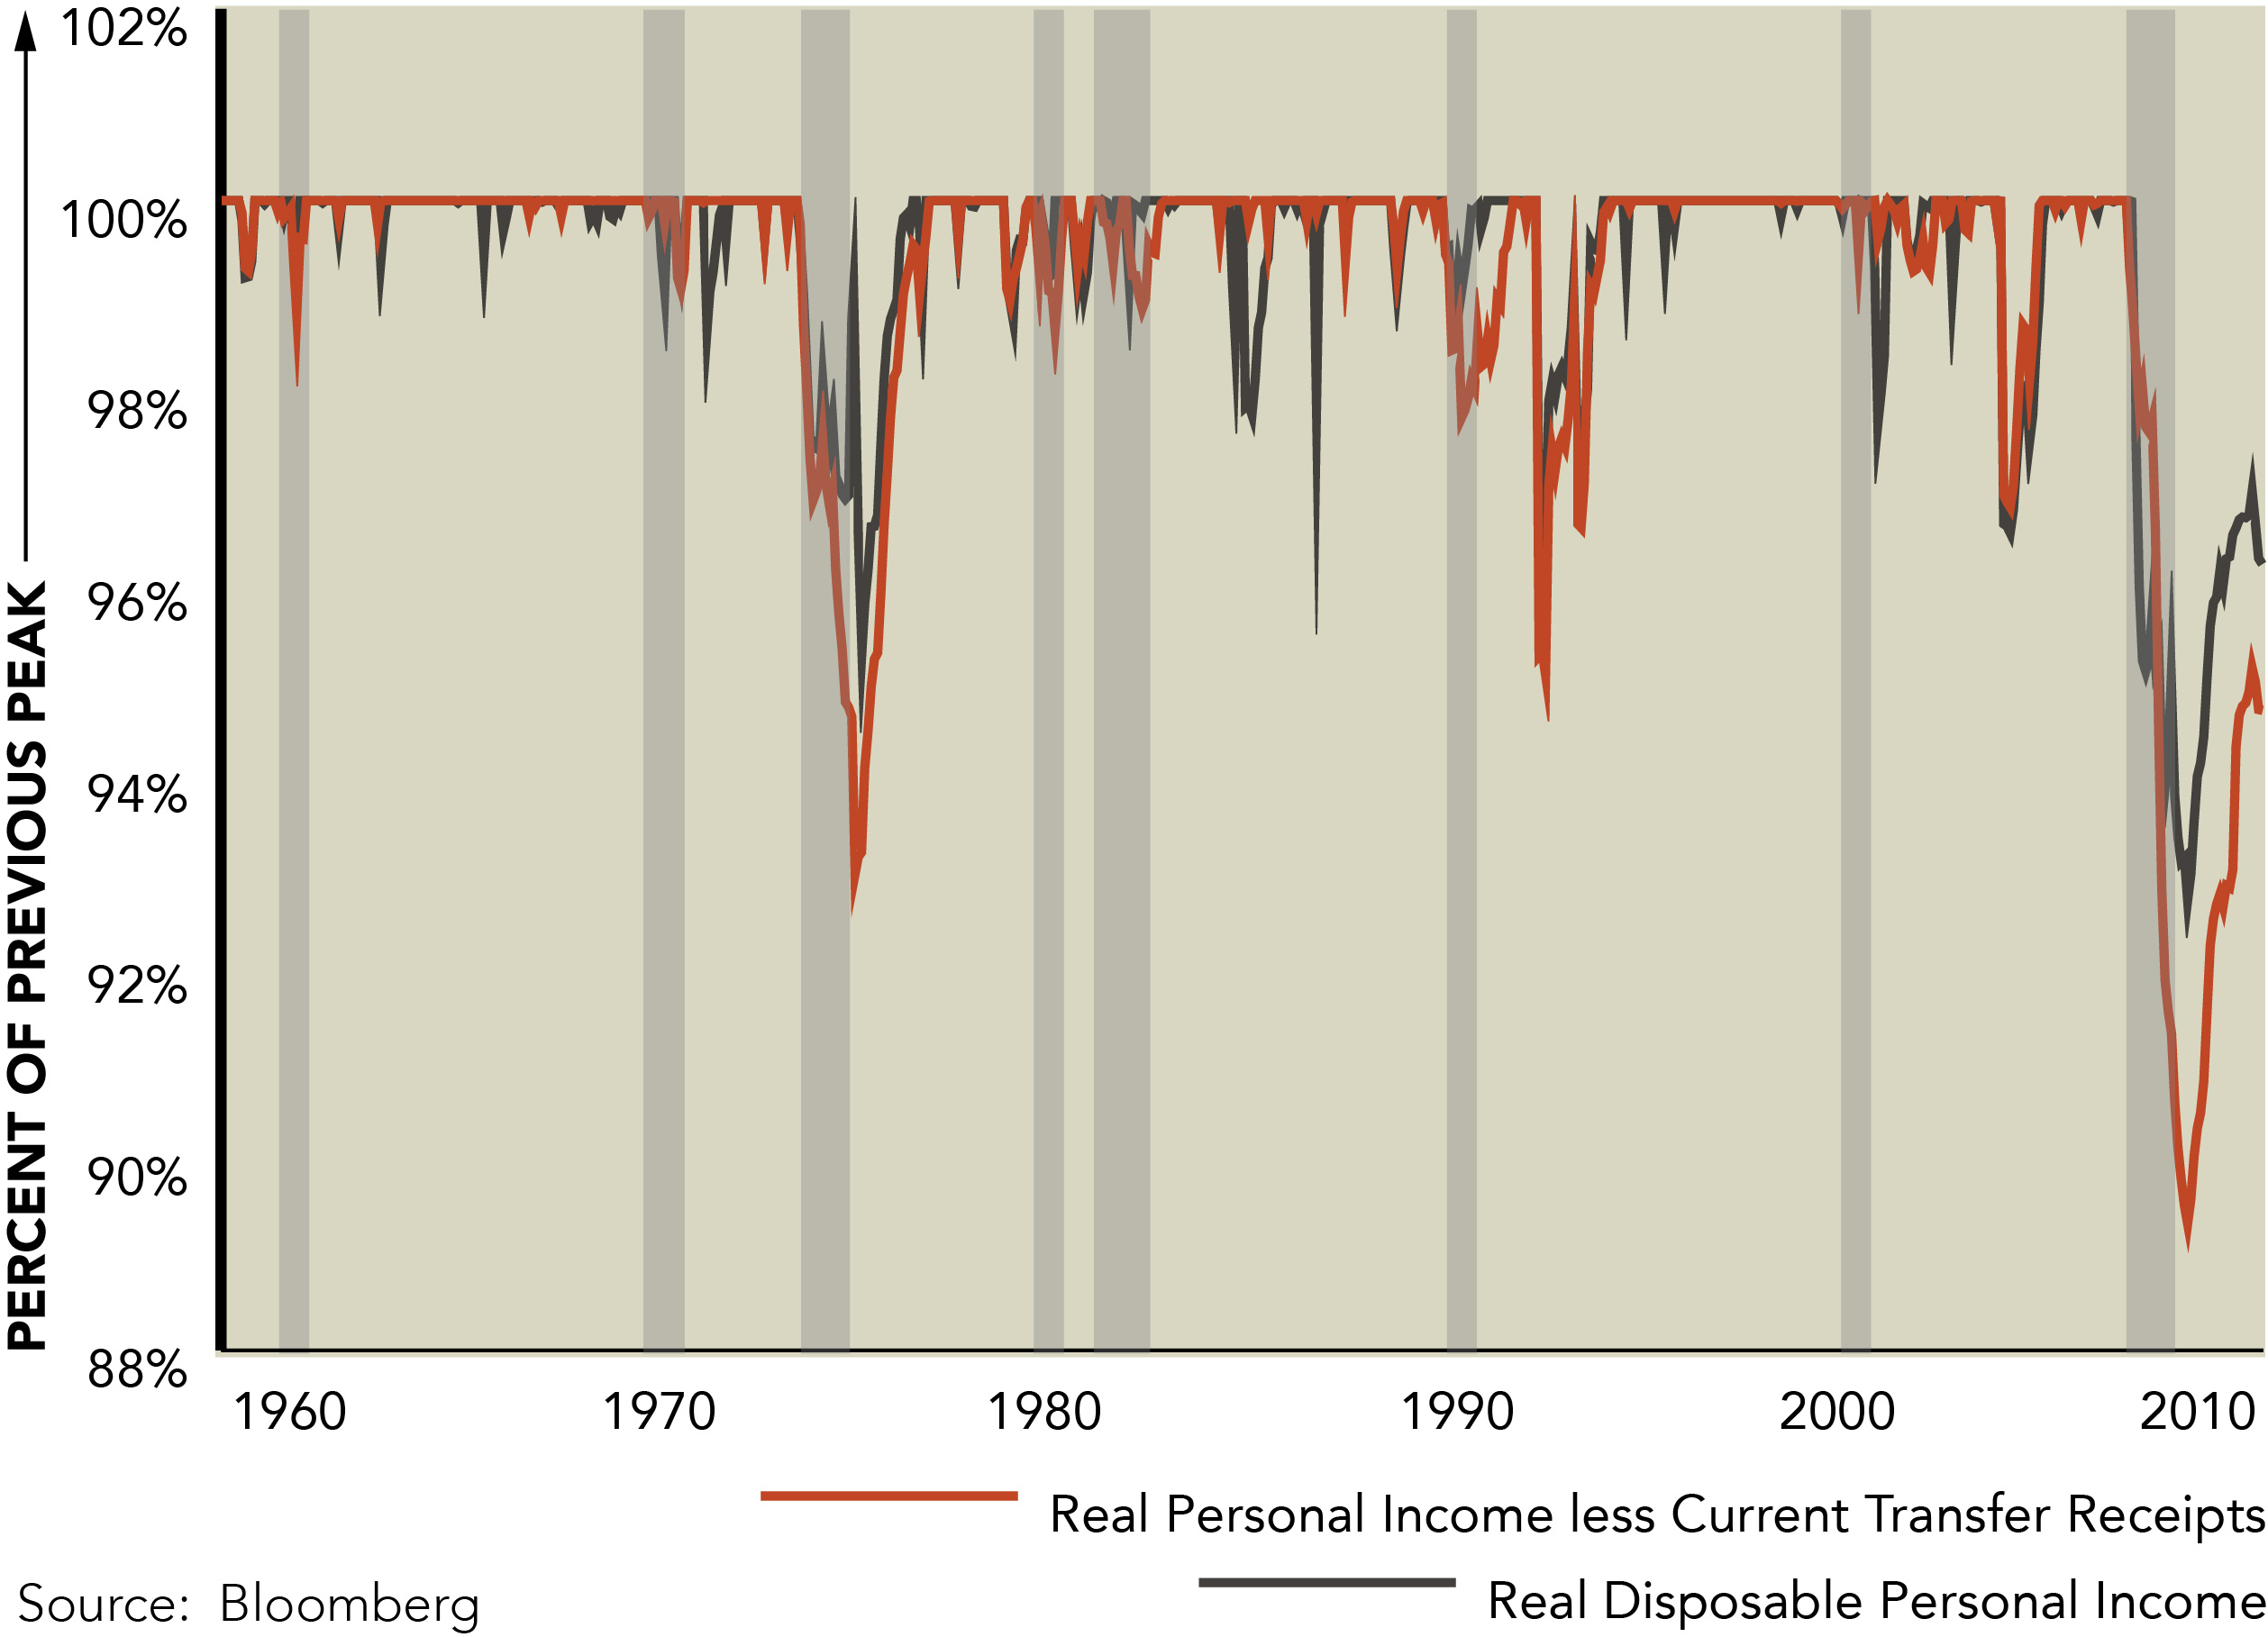
This chart looks at the drop and recovery in real personal income during recessions over the last 50 years (personal income is shown as a percentage of the previous peak to look at prior recessions on an apples-to-apples basis).

This chart looks at the drop and recovery in real personal income during recessions over the last 50 years (personal income is shown as a percentage of the previous peak to look at prior recessions on an apples-to-apples basis). The red line (Real Personal Income less Current Transfer Receipts) shows inflation adjusted after-tax disposable income not including government support (i.e. net social security receipts, unemployment insurance, etc.). The gray line (Real Disposable Income) shows inflation adjusted after-tax disposable income including government support.

A few things stand out. First is the depth of the 2008 – 2010 recession, which was far worse than any prior drop in U.S. incomes. Second, this chart shows the role of government support during recessions, as the drop in real disposable income is far less than would otherwise be expected, due to government support. Thirdly, the drop in real disposable incomes over the last three months is a worrying trend. This is especially true given the growing talk in Washington over reducing government support of disposable income through higher taxes and/or lower spending.

Falling real incomes and less government support does not bode well for U.S. economic growth over the coming quarters.

Too Important to Fail?

SIFIs are financial institutions deemed large and complex enough that their failure would cause ripple effects throughout the financial system. This week’s chart shows CDS spreads on SIFIs of select countries. For countries with multiple banks on the list, the average CDS spread of available data is taken.

The Financial Stability Board (“FSB”) recently released a list of global systemically important financial institutions (“SIFIs”). Based on information from its website, the FSB was established in 2009 and acts to promote financial stability. The current Chair of the FSB is Mario Draghi, the new head of the European Central Bank (“ECB”).

SIFIs are financial institutions deemed large and complex enough that their failure would cause ripple effects throughout the financial system. Of the twenty-nine banks on the FSB’s list, nine are American, and seventeen are European. The full list is shown below:

Asia

  • China: Bank of China
  • Japan: Mitsubishi, Mizuho, Sumitomo Mitsui

Europe

  • Belgium: Dexia
  • France: Banque Populaire, BNP Paribas, Credit Agricole, Societe Generale
  • Germany: Commerzbank, Deutsche Bank
  • Italy: Unicredit
  • Netherlands: ING
  • Spain: Santander
  • Sweden: Nordea
  • Switzerland: Credit Suisse, UBS
  • United Kingdom: Barclays, HSBC, Lloyds, Royal Bank of Scotland

North America

  • United States: Bank of America, Bank of New York Mellon, Citigroup, Goldman Sachs, JP Morgan, Morgan Stanley, State Street, Wells Fargo

This week’s chart shows CDS spreads on SIFIs of select countries. For countries with multiple banks on the list, the average CDS spread of available data is taken.

Rises in the CDS spreads of SIFIs represent growing concerns about systemic risk. Because these financial institutions are large, opaque, and interconnected, rising investor worries about the European debt crises can lead to rising investor concern about the financial health of SIFIs.

As seen in the chart, CDS spreads on Italian banks (Unicredit) began to widen in June. In July, 10-year yields on Italian government debt leapt from 5.0% to nearly 6.0%. The ECB began purchasing Italian bonds on August 8, quickly bringing 10-year Italian yields back down to 5.0%. CDS Spreads on Italian banks continued to rise, however, ending August up 43 bps.

In August, despite the apparent effectiveness of the ECB’s intervention, CDS spreads on U.S., French, German, and Swiss SIFIs increased dramatically. CDS spreads on Spanish and UK SIFIs increased from already elevated levels. French banks, for example, entered August with CDS spreads of 168.6 bps. They ended September up over 100 bps, at 281.9.

During this time, risk assets were pummeled, with the S&P 500 dropping 14.2% in August and September. High yield spreads widened from 540 bps to over 800 bps. Since September, both stocks and high yield bonds have recovered significantly, though high yield spreads remain elevated. Importantly, while CDS spreads on SIFIs are below their peaks, they are still much higher than they were in July. This indicates that despite the recovery in risk assets, investors are still wary of global systemic risk.

In this environment, all risk assets are exposed to global event risk, likely emanating from the EU. For example, the wrong headline out of Greece or Italy could ripple through the global economy causing drops in U.S. stock and corporate bond prices. Financials remain high risk, with potentially high reward. As Jeffries showed, investors may sell first and ask questions later. Attractive opportunities to add risk may present themselves, as the baby gets thrown out with the bathwater.