Checking in on Bitcoin’s Fair Value

March 27, 2025 | Nic Solecki, CBDA, Research Analyst

In May of 2024, we published a Chart of the Week titled “Is Bitcoin Fairly Valued?” At the time, bitcoin and the broader digital asset space demonstrated mixed performance amid heightened market volatility, shifting liquidity conditions, and geoeconomic uncertainty. Recognizing the challenges in determining bitcoin’s fair value, we applied standard valuation principles to estimate bitcoin’s fundamental value at that time. While bitcoin and the broader digital asset space have once again exhibited mixed performance amid a shifting macroeconomic backdrop, much has changed over the last year and recent developments suggest that a reassessment of bitcoin’s fair value could be timely.

To better understand why this reassessment could be relevant for institutional investors, here is a brief and non-exhaustive recap of the key developments in the U.S. crypto space this year:

  • On January 23, the Trump administration issued Executive Order (EO) 14178, Strengthening American Leadership in Digital Financial Technology, signaling a new approach to digital assets and revoking the frameworks and directives established by the Biden administration.
      • Within 180 days, the President’s Working Group on Digital Asset Markets, currently chaired by David Sacks, will evaluate and recommend proposals for a federal framework to govern the issuance and operation of digital assets.
  • On February 5, FDIC Acting Chair Travis Hill and Federal Reserve Governor Michelle Bowman released statements signaling the ongoing reassessment of their organizations’ postures toward the crypto industry — sentiments echoed in recent weeks by officials from the Treasury, DOJ, and SEC.
  • On March 6, President Trump signed the EO to establish a U.S. Strategic Bitcoin Reserve and a separate Digital Asset Stockpile; both to be administered and maintained by the Department of the Treasury.
      • Both are to be initially funded with assets seized or forfeited in criminal and civil cases.
      • Without further executive or legislative action, additional Stockpile assets can only be acquired through forfeiture proceedings and civil money penalties imposed by a government agency.
    • The Secretary of the Treasury and the Secretary of Commerce may develop budget-neutral strategies for acquiring additional bitcoin.
  • As of March 24, 20 states have active legislation advancing the establishment of digital asset reserve funds or diversification of existing public funds with prominent digital assets — with some proposals specifying potential allocations up to 10% of fund assets.

Unsurprisingly, crypto markets responded enthusiastically to the news. By the end of January, the MVDA 10 Index and the MSCI Global Digital Asset Index were both up roughly 10% as bitcoin traded north of $100,000. Then, February arrived, bringing a notable shift in broad market sentiment and volatility, causing digital asset prices to fall alongside public equities. By the end of February, bitcoin was down roughly 18% while some broad crypto indices were down as much as 28%. So where does bitcoin currently stand?

Applying the discounted cash flow (DCF) method used in our prior analysis, bitcoin’s fair relative value range¹ is illustrated above in light teal, with its upper and lower bounds highlighted, respectively, in orange and green. While bitcoin appears to have closed February at undervalued levels, as of March 24, bitcoin appears to be slightly below and advancing toward its fair value range. That said, it is important to clarify that this point-in-time DCF method is just one of several potential valuation approaches, and other estimates may vary. Valuations for both floating fiat currencies and cryptocurrencies are dynamic, constantly adjusting to inflation, nominal yields, and broader macroeconomic conditions. Going forward, future inflation trends and market dynamics will provide further opportunities to validate this fundamental approach.

1The discounted terminal values of bitcoin are based on a discounted cash flow model that incorporates U.S. Treasury yields, inflation rates, and imputed risk premiums. 

Print PDF

Nic Solecki, CBDA
Research Analyst

Get to Know Nic

The opinions expressed herein are those of Marquette Associates, Inc. (“Marquette”), and are subject to change without notice. This material is not financial advice or an offer to purchase or sell any product. Marquette reserves the right to modify its current investment strategies and techniques based on changing market dynamics or client needs.

Related Content

Bar chart comparing October and year-to-date 2026 returns for Korea, Taiwan, Brazil, India, China, and the MSCI Emerging Markets Index. October returns are below zero for most markets, while year-to-date returns range from negative to positive. For full dataset, please contact marquettemarketing@marquetteassociates.com.

11.02.2026

The Haunting of Emerging Markets

Emerging markets faced a challenging October, with the space declining by around 8.3% amid renewed concerns over the sustainability of…

Stacked bar chart showing U.S. private equity deal value by deal size from Q1 2022 through Q2 2026. The y-axis shows percentage of total deal value from 0% to 100%, and the x-axis shows quarters by year. Stacked bar chart showing the percentage of U.S. private equity deal count by deal size from Q1 2022 through Q2 2026. The y-axis ranges from 0% to 100%, and the x-axis shows quarters by year. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.26.2026

Smaller Deals, Larger Appeal

Private equity activity is increasingly shifting toward smaller transactions, with total deal value for transactions of $100 million or less…

Line chart comparing S&P 500 Index cumulative returns for midterm and non-midterm election years since 1980. The x-axis shows October through December, and the y-axis shows S&P 500 Index cumulative return, ranging from -1% to 8%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.19.2026

Divided We Rise?

Since 1980, the S&P 500 Index has generally performed well in the weeks surrounding U.S. midterm elections. Specifically, the index…

Chart #1 - Line chart showing PJM summer peak load estimates in gigawatts (GW) from 2015 to 2045. The chart compares historical peak load, current capacity, and forecasts from 2024, 2025, and 2026, showing projected demand rising above current capacity over time. Chart #2 - Stacked bar chart showing U.S. power demand in terawatt-hours (TWh) for 2025 and estimated demand in 2030. The chart compares data center and non-data center demand, showing total power demand increasing over the period.

10.12.2026

The Power Demand Supercycle

This week’s chart highlights the accelerating growth of electricity demand in the U.S., which has been driven primarily by the…
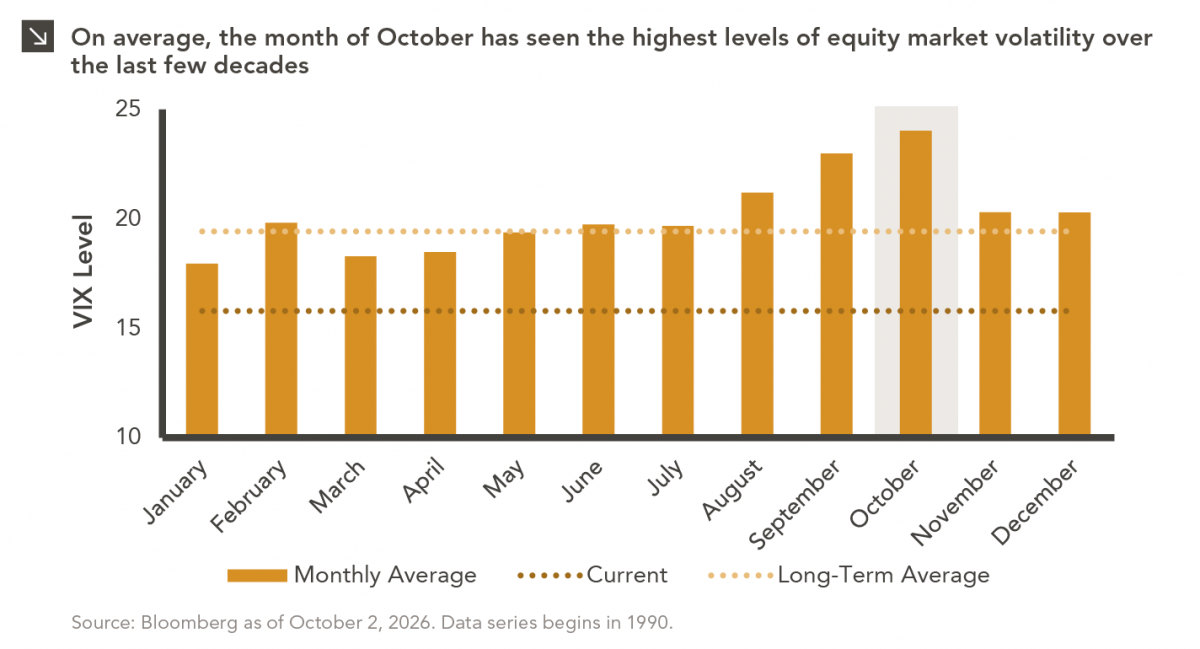
Bar chart showing average monthly VIX levels from 1990 through October 2026. The x-axis displays months of the year from January through December, and the y-axis displays VIX level. October has the highest average VIX level among all months, while April has the lowest. The chart also includes a current VIX level and a long-term average VIX level for comparison. Source: Bloomberg as of October 2, 2026. Data series begins in 1990. For full dataset, please contact marquettemarketing@marquetteassociates.com.

10.05.2026

Spooky Season

For investors, the spookiest thing about October might not be the ghosts and monsters that are bound to show up…
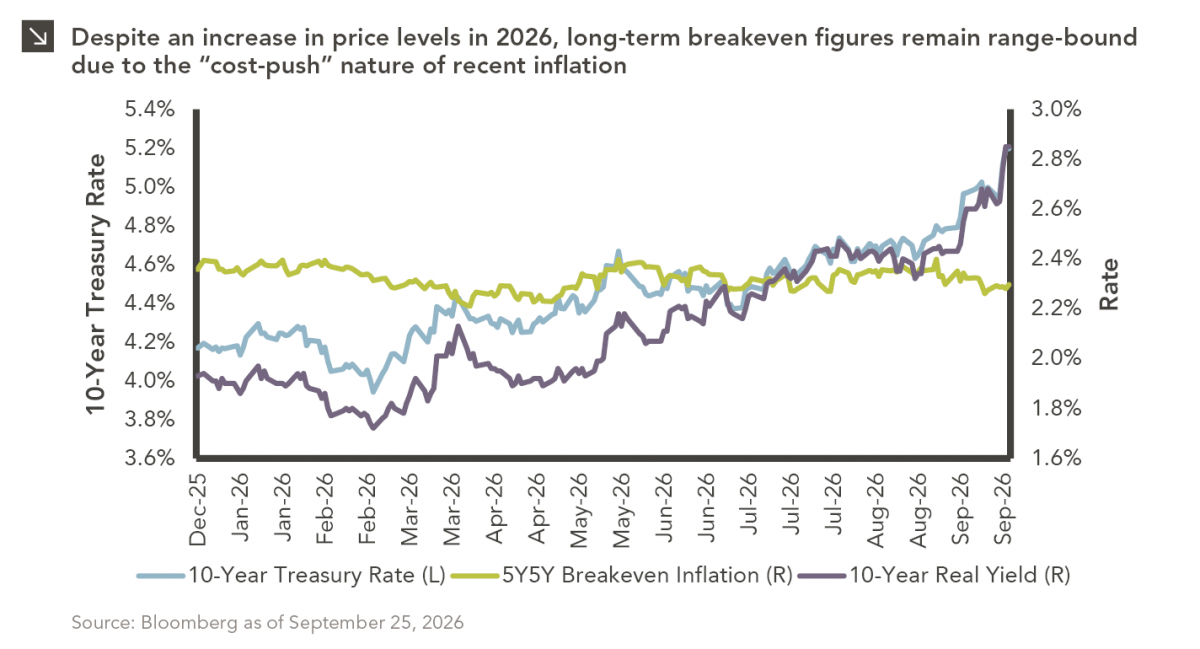
Line chart showing 10-year U.S. Treasury rate, 5-year/5-year breakeven inflation rate, and 10-year real yield from December 2025 through September 2026. The left axis shows rates from 3.6% to 5.4%, and the right axis from 1.6% to 3.0%. The Treasury rate and real yield rise notably in late 2026, while the breakeven inflation rate remains relatively range-bound around 2.3%–2.4%. For full dataset, please contact marquettemarketing@marquetteassociates.com.

09.28.2026

Getting Real on Inflation

The phrase “expectations of higher inflation” has become a staple in financial news to explain the increase in nominal U.S….

More articles

Subscribe to Research Email Alerts

Research Email Alert Subscription

Research alerts keep you updated on our latest research publications. Simply enter your contact information, choose the research alerts you would like to receive and click Subscribe. Alerts will be sent as research is published.

We respect your privacy. We will never share or sell your information.

Thank You

We appreciate your interest in Marquette Associates.

If you have questions or need further information, please contact us directly and we will respond to your inquiry within 24 hours.

Contact Us >